China’s financial system near ‘peak stress,’ but spillovers yet to come: analysts

China’s financial system near ‘peak stress,’ but spillovers yet to come: analysts

China’s economic markets are nearing “peak stress” ranges, with concerns mounting above its highly leveraged home sector as the saga all around troubled developer China Evergrande Team performs out.

And investors should not count on a sustained bounce in the country’s fairness current market right up until the credit rating cycle turns for the better, explained analysts at Danske Bank.

But belongings indirectly connected to the world’s 2nd-largest economic system have still to feel the spillover consequences of China’s financial slowdown, they also warned, in a Friday observe.

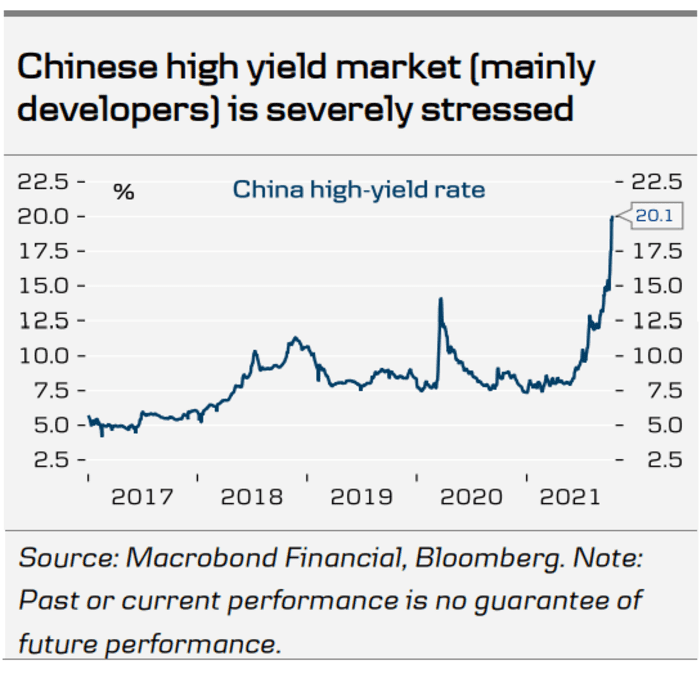
“While Chinese fairness marketplaces have been more stable currently, the worry in credit rating markets for developers have ongoing unabated with rates on large produce credit history achieving new highs by the working day,” wrote Copenhagen-primarily based Allan von Mehren and Lars Sparresø Merklin (see chart down below).


Danske Lender

Evergrande
708,
+4.63{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996},
the highly leveraged developer with a lot more than $300 billion in personal debt, has been in the highlight, reportedly missing numerous coupon payments in modern months and in threat of remaining declared in default as grace intervals for those payments run out. Evergrande’s chief government, Xia Haijun, was holding talks in Hong Kong with lenders and buyers around a restructuring and probable asset revenue, Reuters reported Friday, citing two persons familiar with the make any difference.

A selloff past 7 days for dollar-denominated bonds of Chinese developers was activated immediately after luxury developer Fantasia Holdings Team Co. unsuccessful unexpectedly to repay $206 million in dollar bonds that matured on Oct. 4.

Amid fears of a spillover, China’s central lender on Friday piped up to say that threats to the money system from the residence sector, which are believed to account for practically 30{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of the country’s gross domestic solution the moment upstream and downstream links are taken into account, had been controllable, The Wall Road Journal claimed, citing condition media outlets.

Zou Lan, head of financial markets at the People’s Financial institution of China, stated officers ended up urging Evergrande to velocity up asset disposals and resume tasks to secure the interests of dwelling purchasers, the report explained. The formal reported economical authorities, the housing ministry and nearby governments would perform alongside one another to offer funding support so stalled jobs could restart.

The Shanghai Composite
SHCOMP,
+.40{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}
fell .6{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} this week, whilst the broader CSI 300
000300,
+.38{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}
eked out a minor acquire. The Shanghai Composite is up 2.9{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} for the yr to day, but down additional than 4{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} from its 2021 peak set in February. The CSI 300 is down 5.4{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} for the calendar year and has tumbled virtually 17{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} from its 2021 superior.

The big-cap U.S. benchmark S&P 500
SPX,
+.75{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}
is up extra than 19{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} so significantly this year, while the blue-chip Dow Jones Industrial Ordinary
DJIA,
+1.09{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}
has obtained far more than 15{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

The Danske analysts noted that large state financial institutions had been explained to to ease limits on mortgage loan lending and have been allowed to securitize loans once more, in an work to underpin home revenue.

They stated Beijing will most likely choose steps before long to “unfreeze” credit history markets, “as pretty handful of builders can endure this type of funding and liquidity squeeze for extensive.”

Among the selections, the PBOC could slice the reserve need ratio and immediate large point out banks to start out purchasing substantial-yield bonds, they said. The analysts argued that if conditions quiet, obtaining bonds at 20{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} would very likely flip out to be a “quite favorable” investment decision for the financial institutions, while personal traders would also be inspired to get started shopping for if the authorities will get associated.

They also see more direct financial institution lending to builders, with authorities very likely to loosen rules that crimped financial loans previous yr.

On the other hand, the Danske analysts and other China watchers have argued that Evergrande and the residence sector have been not likely to threaten a “Lehman second,” a reference to the 2008 collapse of Lehman Brothers that quickly froze international credit score marketplaces and marked the bleakest stage of the world financial crisis. Which is since the government’s capability to dictate the actions of creditors and many others give Beijing more overall flexibility.

But the crackdown on excesses in the residence sector and other aspects had been continue to possible to make certain a continued slowdown in China’s financial state.

“Even pursuing an orderly restructuring of the worst-affected builders with nominal contagion to the money process, development activity would however just about inevitably gradual a lot further. As we have warned for some time, that’s the sensible consequence of the ‘three crimson lines’ coverage imposed on builders past 12 months, as well as the huge demographic headwinds that the sector faces,” said Oliver Jones, senior markets economist at Funds Economics, in an Oct. 12 take note.

The Danske analysts emphasized that there is a prolonged way to go from peak money stress to restarting the credit rating cycle.

“For Chinese equities, this may simply be a interval of time wherever we see more sideways moves, awaiting the subsequent large cyclical reboot of credit rating,” they wrote. “For assets which are more indirectly connected to Chinese property and the credit score cycle, we suspect this will imply minor.”

For case in point, the euro
EURUSD,
-.01{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}
is probably to carry on slipping versus the greenback “as the results of historic Chinese tightening moves as a result of the worldwide production
chains.”

Nashville again seeking new finance director | Local News

Nashville again seeking new finance director | Local News

Right after several several years of upheaval in its finance division, the Town of Nashville is acquiring back on track and is wanting for a new finance director.

Samantha Sanchez, the town’s newest finance director, resigned productive Sept. 17. She had served in the position comprehensive-time for approximately two years but is transferring on to a new position in the finance department for the City of Wake Forest, Nashville Town Supervisor Randy Lansing explained in a modern interview.

“She has been an great finance director, and we actually loathe to shed her,” Lansing stated. “We had a whole lot of things on the publications that desired to be cleaned up. Ms. Sanchez took time to function with the auditor and get us again on keep track of.”

Nashville is now off the Nearby Govt Commission Watchlist just after investing the very last quite a few decades less than scrutiny. In a recent assertion, Condition Treasurer Dale Folwell introduced that the Community Governing administration Commission experienced taken off 38 entities from its Unit Assistance Record, a monitoring gadget that flags and tracks regional governments and public authorities battling money and governance challenges.

The Town of Nashville was amongst the 27 towns, eight counties and a few utility districts commended for their development. These entities, the statement reported, “had designed these kinds of sizeable advancements that they ended up no extended included on the list.”

“This is extremely superior news for individuals area governments since it provides balance to their operations,” Folwell explained in the assertion. “By maximizing governance, transparency and stewardship of the revenue entrusted to them, these models have demonstrated a route forward that some others can design.”

The city experienced faced censure for particular accounting techniques that placed it on the check out record. In a letter dated Jan. 28, 2020, the fee pointed out improvement but nevertheless experienced worries.

“The team of the Local Governing administration Commission analyzed the audited economical statements of the City of Nashville for the fiscal yr ended June 30, 2019,” the letter said. “We observe that the municipality has created development. Our workplace has obtained the audit for the fiscal year finished June 30, 2019 … We commend the governing board, team and citizens for this improvement. On the other hand, there are continue to major fiscal and operational troubles that have to be addressed in purchase to further more your attempts to strengthen the municipality’s fiscal operations.”

The letter famous special fears about the way transfers ended up manufactured from the town’s drinking water and sewer fund, noting that some ended up unbudgeted transfers manufactured opposite to condition regulation.

There was also concern about the timeliness of document-keeping and reviews throughout the recent interval of upheaval in the Nashville Finance Section.

“We noted different weaknesses about your municipality’s inner controls that were communicated in crafting to you by the auditor,” the letter mentioned. “We are in particular anxious that the auditor noted as a material weak point that reconciliations of considerable accounts were being not performed in a timely way. This item noted by the auditor was identified to support the Board in improving upon the municipality’s total accounting technique. We notice that you have developed a corrective motion program to eradicate these weaknesses. The corrective motion approach that was recognized was insufficient.”

At that level, the auditor’s office environment acknowledged that modern workers troubles in the finance section have been element of the issue but ended up not an justification.

“Despite turnover within employees, lender reconciliations should really be reconciled accurately to the standard ledger monthly. We really encourage the board to keep an eye on the municipality’s progress in applying this strategy and urge you to build a corrective motion prepare to get rid of the other objects discovered by the auditor,” the letter said.

The city has confronted a good deal of turnover in the finance division since previous finance director Linda Modlin was fired at approximately the exact time that former city supervisor Hank Raper was dismissed in June 2018. Modlin served as the town’s finance director from Aug. 19, 2014, to June 29, 2018, but was on administrative leave for the very last handful of months of her tenure.

In accordance to details furnished by Nashville Human Source Director Lou Bunch, Lynne Hobbs served briefly as interim deputy finance director from June 4, 2018, right up until Melonie Bryan was hired to provide as interim finance director on July 30, 2018. Hobbs now is a Nashville town councilwoman.

Bryan served as the town’s interim finance director for the future year. For the duration of this time, Russell Langley was employed as the assistant finance director on Feb. 26, 2019, and was qualified with the intention of owning him get on the posture of finance director subsequent a probation interval.

Even so, Langley resigned on Aug. 26, 2019, ahead of assuming the job, Bunch claimed.

Sanchez was hired on Sept. 30, 2019, and has served as the town’s finance director at any time considering the fact that. In the course of that time, she was mostly responsible for the town’s removal from the LGC enjoy list, Lansing stated.

The city is now promoting for a new finance director. According to the advert posted by the city on its website, city officials are searching for anyone who “is trying to find an seasoned expert with powerful interpersonal and monetary competency skills to oversee the city’s $15 million budget.”

The city also is looking for a person with three to 5 decades of “progressively dependable governmental accounting and fiscal administration knowledge, preferably in a local government environment and supervisory experience.”

The income assortment supplied for the place is $65,000 to $97,418. For a lot more information and facts or to utilize, go to the town’s website.

Stocks End Higher, Giving S&P 500 Its Best Week Since July | Business News

Stocks End Higher, Giving S&P 500 Its Best Week Since July | Business News

By STAN CHOE and ALEX VEIGA, AP Small business Writers

Wall Avenue added to its the latest gains Friday as stocks shut increased, driving the S&P 500 to its finest 7 days due to the fact July.

The S&P 500 rose .7{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} for its third straight acquire and finished the 7 days 1.8{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} larger. The Dow Jones Industrial Regular rose 1.1{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} and the Nasdaq composite obtained .5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

The most recent rally arrived as traders welcomed encouraging quarterly report cards from a number of providers. Top the way for the S&P 500 was freight deliverer J.B. Hunt Transportation Expert services, which jumped 8.7{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} just after reporting more powerful revenue for the summertime than Wall Road predicted. Goldman Sachs rose 3.8{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} and Alcoa surged 15.2{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} just after it defeat earnings expectations and announced a dividend payment and buyback of its inventory.

The good company earnings dovetailed with a report demonstrating folks invested much a lot more at U.S. vendors last month than Wall Road envisioned. Gross sales at retailers, eating places and other retail establishments rose .7{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} from August as a substitute of falling, as economists forecast.

Political Cartoons

“We saw retail gross sales this morning occur in pretty powerful,” stated Sameer Samana, senior international marketplace strategist at Wells Fargo Financial investment Institute. “(Shares) are even now at pretty fair valuations with another earnings period obtaining just ticked on, and hence far at minimum, some pretty great success.”

The S&P 500 rose 33.11 details to 4,471.37. The Dow attained 382.20 details to 35,294.76, and the Nasdaq rose 73.91 factors to 14,897.34.

Friday’s attain follows up on a 1.7{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} bounce for the S&P 500 Thursday, its ideal working day considering that March, which was driven by more powerful-than-predicted earnings reviews and encouraging info on the task sector.

It is a turnaround from a shaky handful of months, when the benchmark index fell as significantly as 5.2{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} from its file established on Sept. 2. Anxieties about stubbornly substantial inflation, lowered help for markets from the Federal Reserve and a slowing financial state assisted to knock inventory price ranges all over. The S&P 500 is back again within 1.5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of its all-time large.

Earnings reporting year has just started, but early indicators are encouraging. All but a person of the 19 providers in the S&P 500 that documented quarterly final results this week topped analysts’ gain forecasts. This kind of toughness is vital soon after climbing interest premiums heightened problems that inventory costs had developed much too expensive relative to profits.

The much better-than-predicted stories on the overall economy also enable tranquil chatter about “stagflation,” which is the feared marriage of a stagnating economic system and significant inflation.

Of course, all is not apparent but. A report on Friday displaying consumer sentiment was weaker than envisioned amid inflation problems aided restrict the market’s gains.

Continue to, stocks of organizations whose profits are most closely tied to the energy of the financial system, together with suppliers, automakers and journey-similar organizations, led the way higher Friday. Amazon rose 3.3{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, Tesla included 3{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} and Marriott Global received 3.1{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

Other than monetary organizations, which benefited from the far better-than-expected financial gain reports from various big-name financial institutions, industrial and wellness treatment firms were also amongst the strongest gainers. Caterpillar rose 2.4{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, although UnitedHealth extra 1.8{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

Johnson & Johnson gained .7{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} right after a Foods and Drug Administration panel endorsed booster doses of the firm’s solitary-shot COVID-19 vaccine. The panel said Friday that the booster should be offered at minimum two months right after immunization but didn’t counsel a agency time.

Treasury yields also rose adhering to the a lot more powerful-than-envisioned report on retail revenue. The generate on the 10-yr notice climbed to 1.57{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} from 1.52{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} late Thursday.

“The biggest surprise on costs continues to be how minimal they are relative to all the anecdotal proof and all the info about inflation that we see,” Samana stated.

Better Treasury yields in the latest weeks have been keeping back technological innovation and other substantial-progress stocks lately. When bonds are paying additional in fascination, investors usually are not as keen to wait around as lengthy a time for major income development anticipations to come to fruition or to pay out as superior rates for them.

Tech stocks in the S&P 500 fared a very little better Friday, matching the broader marketplace with a .8{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} acquire, while the conversation-providers sector that includes several online firms slipped .1{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

Inventory markets abroad also notched gains. In Europe, Germany’s DAX returned .8{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, and France’s CAC 40 acquired .6{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}. The FTSE 100 in London rose .4{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

In Asia, Tokyo’s Nikkei 225 extra 1.8{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, Hong Kong’s Cling Seng climbed 1.5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} and Seoul’s Kospi advanced .9{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

The price of benchmark U.S. oil rose 1.2{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $82.28 per barrel, continuing a highly effective run that has sent it up additional than 70{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} this calendar year and fanned problems about large inflation. The world benchmark for crude climbed 1{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, while the price of U.S. pure gasoline fell 4.9{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

AP Company Writer Elaine Kurtenbach contributed.

Copyright 2021 The Involved Press. All rights reserved. This substance may perhaps not be revealed, broadcast, rewritten or redistributed.

How agile financial management can facilitate frontline delivery

How agile financial management can facilitate frontline delivery
agile financial management
© Dvmsimages

Simon Gray, Head of Finance and Operations at Agilisys, discusses how fashionable agile fiscal management units can enrich strategic selection generating in the general public sector

If modern functions have taught us one particular matter, it is the actuality that the planet can turn upside down in double-rapid time. When major uncertainty stays around the extensive-phrase impacts of the pandemic – and what this will indicate for the public sector – finance leaders will require to aid their organisations digest new facts and act speedily as situations modify.

The have to have for responsiveness is acute. If you just cannot make well timed conclusions, then you’re generally guiding the curve. Monetary issues are all over the place. The critical is getting authentic-time entry to related data so priorities can be established for allocating budgets and economic administration.

As a citizen, I want to know that when my council agrees on its hottest finances, it is factoring in potential challenges in the long run. To do this, modelling is crucial. Income is fairly static, as are sure statutory providers that have to be sent this kind of as environmental well being, waste assortment and avenue cleansing. These account for a selected level of shell out. The large dilemma, on the other hand, is all over what you do with the rest of the cash.

All about the details

The truth is, if you never have the details to demonstrate how finest to utilise the readily available funds, you can’t make those selections. Even further, you simply cannot talk the reasoning powering individuals conclusions to citizens. Finance methods are all about info. The ordinary neighborhood authority has hundreds of techniques whole of monetary info covering arranging, highways, grownup social treatment, children’s care, faculties and so on. Effective finance methods just take that information, normalise it and let a spending plan holder to determine what they can – or can not – do with their out there funds.

Scenario preparing offers the opportunity for finance to help the organisation with a vital strategic overview. This in turn permits knowledgeable selection building in a well timed fashion. For case in point, if you are going to start off switching off some library solutions in the neighborhood, what have you well balanced that in opposition to in phrases of priorities? What are you heading to invest the cash on as an alternative? Appropriate up to executive amount, that’s the type of facts they count on to make those people decisions.

Dynamism and adaptability

There is no doubt that there is a great deal of urge for food for modern, dynamic economical programs. However, it mustn’t be a knee jerk response. It is vital that community authorities function with suppliers that have in-depth technical Microsoft Dynamics 365 Finance know-how to simplicity their transformation strategies. Only then can they make the technologies-enabled finance team that community sector organisations crave.

People community authorities that have adopted these solutions are already starting to reward from the adaptability in the way techniques can be configured to produce circumstance setting up. They are taking pleasure in the capability to in good shape devices to their exceptional demands and effectively locate approaches to produce efficiency to workers and citizens alike. Cell, portal-centered remedies that are effortless to obtain at any time, anywhere are specifically resonating specified the want for flexible doing the job.

Up in the cloud

The adoption of cloud-to start with insurance policies is one more essential aspect in the shift to modern, SaaS-centered enterprise analysis arranging (ERP) answers. Invest in to spend, get to dollars, expenditures, challenge accounting and payroll are just some of the parts that advantage from a complete cloud ERP experience. This is then supported by robust analytics and reporting with versatile on-demand from customers performing that adapts to organisational requirements.

Microsoft Dynamics 365 Finance integrates all pertinent processes throughout a regional authority, such as finance, task management, getting and shopper romantic relationship management as perfectly as billable hours and spending plan administration. All the details is immediately readily available, enabling the workforce to carry out a thorough investigation and changes that ensures business enterprise agility, minimised price tag, optimised expending throughout departments and procedure automation.

4 traces of sight

Today’s neighborhood authority finance chief has four strains of sight: hindsight and oversight, concentrated on financial monitoring and historical figures, as nicely as perception and foresight, concentrated on anticipating the long term and evolving to meet the desires of stakeholders like the board, investors, and the group at significant.

Lively economic preparing enabled by the modern finance methods in depth earlier mentioned, presents these 4 strains of sight. They aid financial directors obtain data-pushed insights into the prospective impression of several scenarios, though agile fiscal management allows shift the concentration toward successful resourcing advancements for frontline delivery. They also enable finance leaders offer with uncertainty and disruption an critical requirement as we emerge from the COVID-19 pandemic.

Editor’s Advised Article content

Goldman Sachs cashes in on M&A wave to cap stellar quarter for U.S. banks

Goldman Sachs cashes in on M&A wave to cap stellar quarter for U.S. banks

Oct 15 (Reuters) – Goldman Sachs Team Inc (GS.N) on Friday claimed a 66{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} surge in third-quarter profit that smashed anticipations, as Wall Street’s greatest expense lender rode a history wave of M&A activity and initial general public choices.

The bank posted gains of $5.28 billion up from $3.23 billion a 12 months in the past, capping a stellar quarter for Wall Street lenders which have benefited from a rebounding U.S. economic climate, unstable fairness markets and a world deal-earning bonanza.

Shares of Goldman Sachs were being up 2{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} in mid-morning trading.

World-wide M&A volumes have shattered all-time documents, with offers truly worth in excess of $1.5 trillion inked by the world’s most significant investment banks in the third quarter, in accordance to Refinitiv knowledge.

Goldman comfortably held its leading rating on the league tables for around the globe M&A advisory, in accordance to the Refinitivdata whichranks economic expert services firms on the total of M&A charges they make.

Those surging M&A service fees drove Goldman Sachs’ total money advisory profits up 225{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $1.65 billion, whilst underwriting profits, which has been boosted by a rush of non-public companies looking to go public, surged 33{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $1.90 billion.

All advised, Goldman’s investment financial institution boasted its second-best quarter at any time, with overall earnings of $3.70 billion, and executives mentioned they assume revenues to continue on to be strong.

“I continue being optimistic about (possibilities),” Goldman Sachs Chief Govt Officer David Solomon stated on a call with analysts. “Exercise stages keep on being large specifically in expense banking.”

Earnings for each share were $14.93 from $8.98 a yr before, outstripping the $10.18 for every share analysts experienced predicted, according to the IBES estimate from Refinitiv.

Goldman’s worldwide markets company, which now homes the buying and selling organization and accounts for roughly 41{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of general revenue, described profits of $5.61 billion, up 23{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

Together with its rivals, Goldman also cashed in as organizations rushed to refinance debt and promote new inventory, although volatility in world-wide equities marketplaces, pushed by worries above central lender policy tightening, retained buying and selling desks hectic all through the quarter.

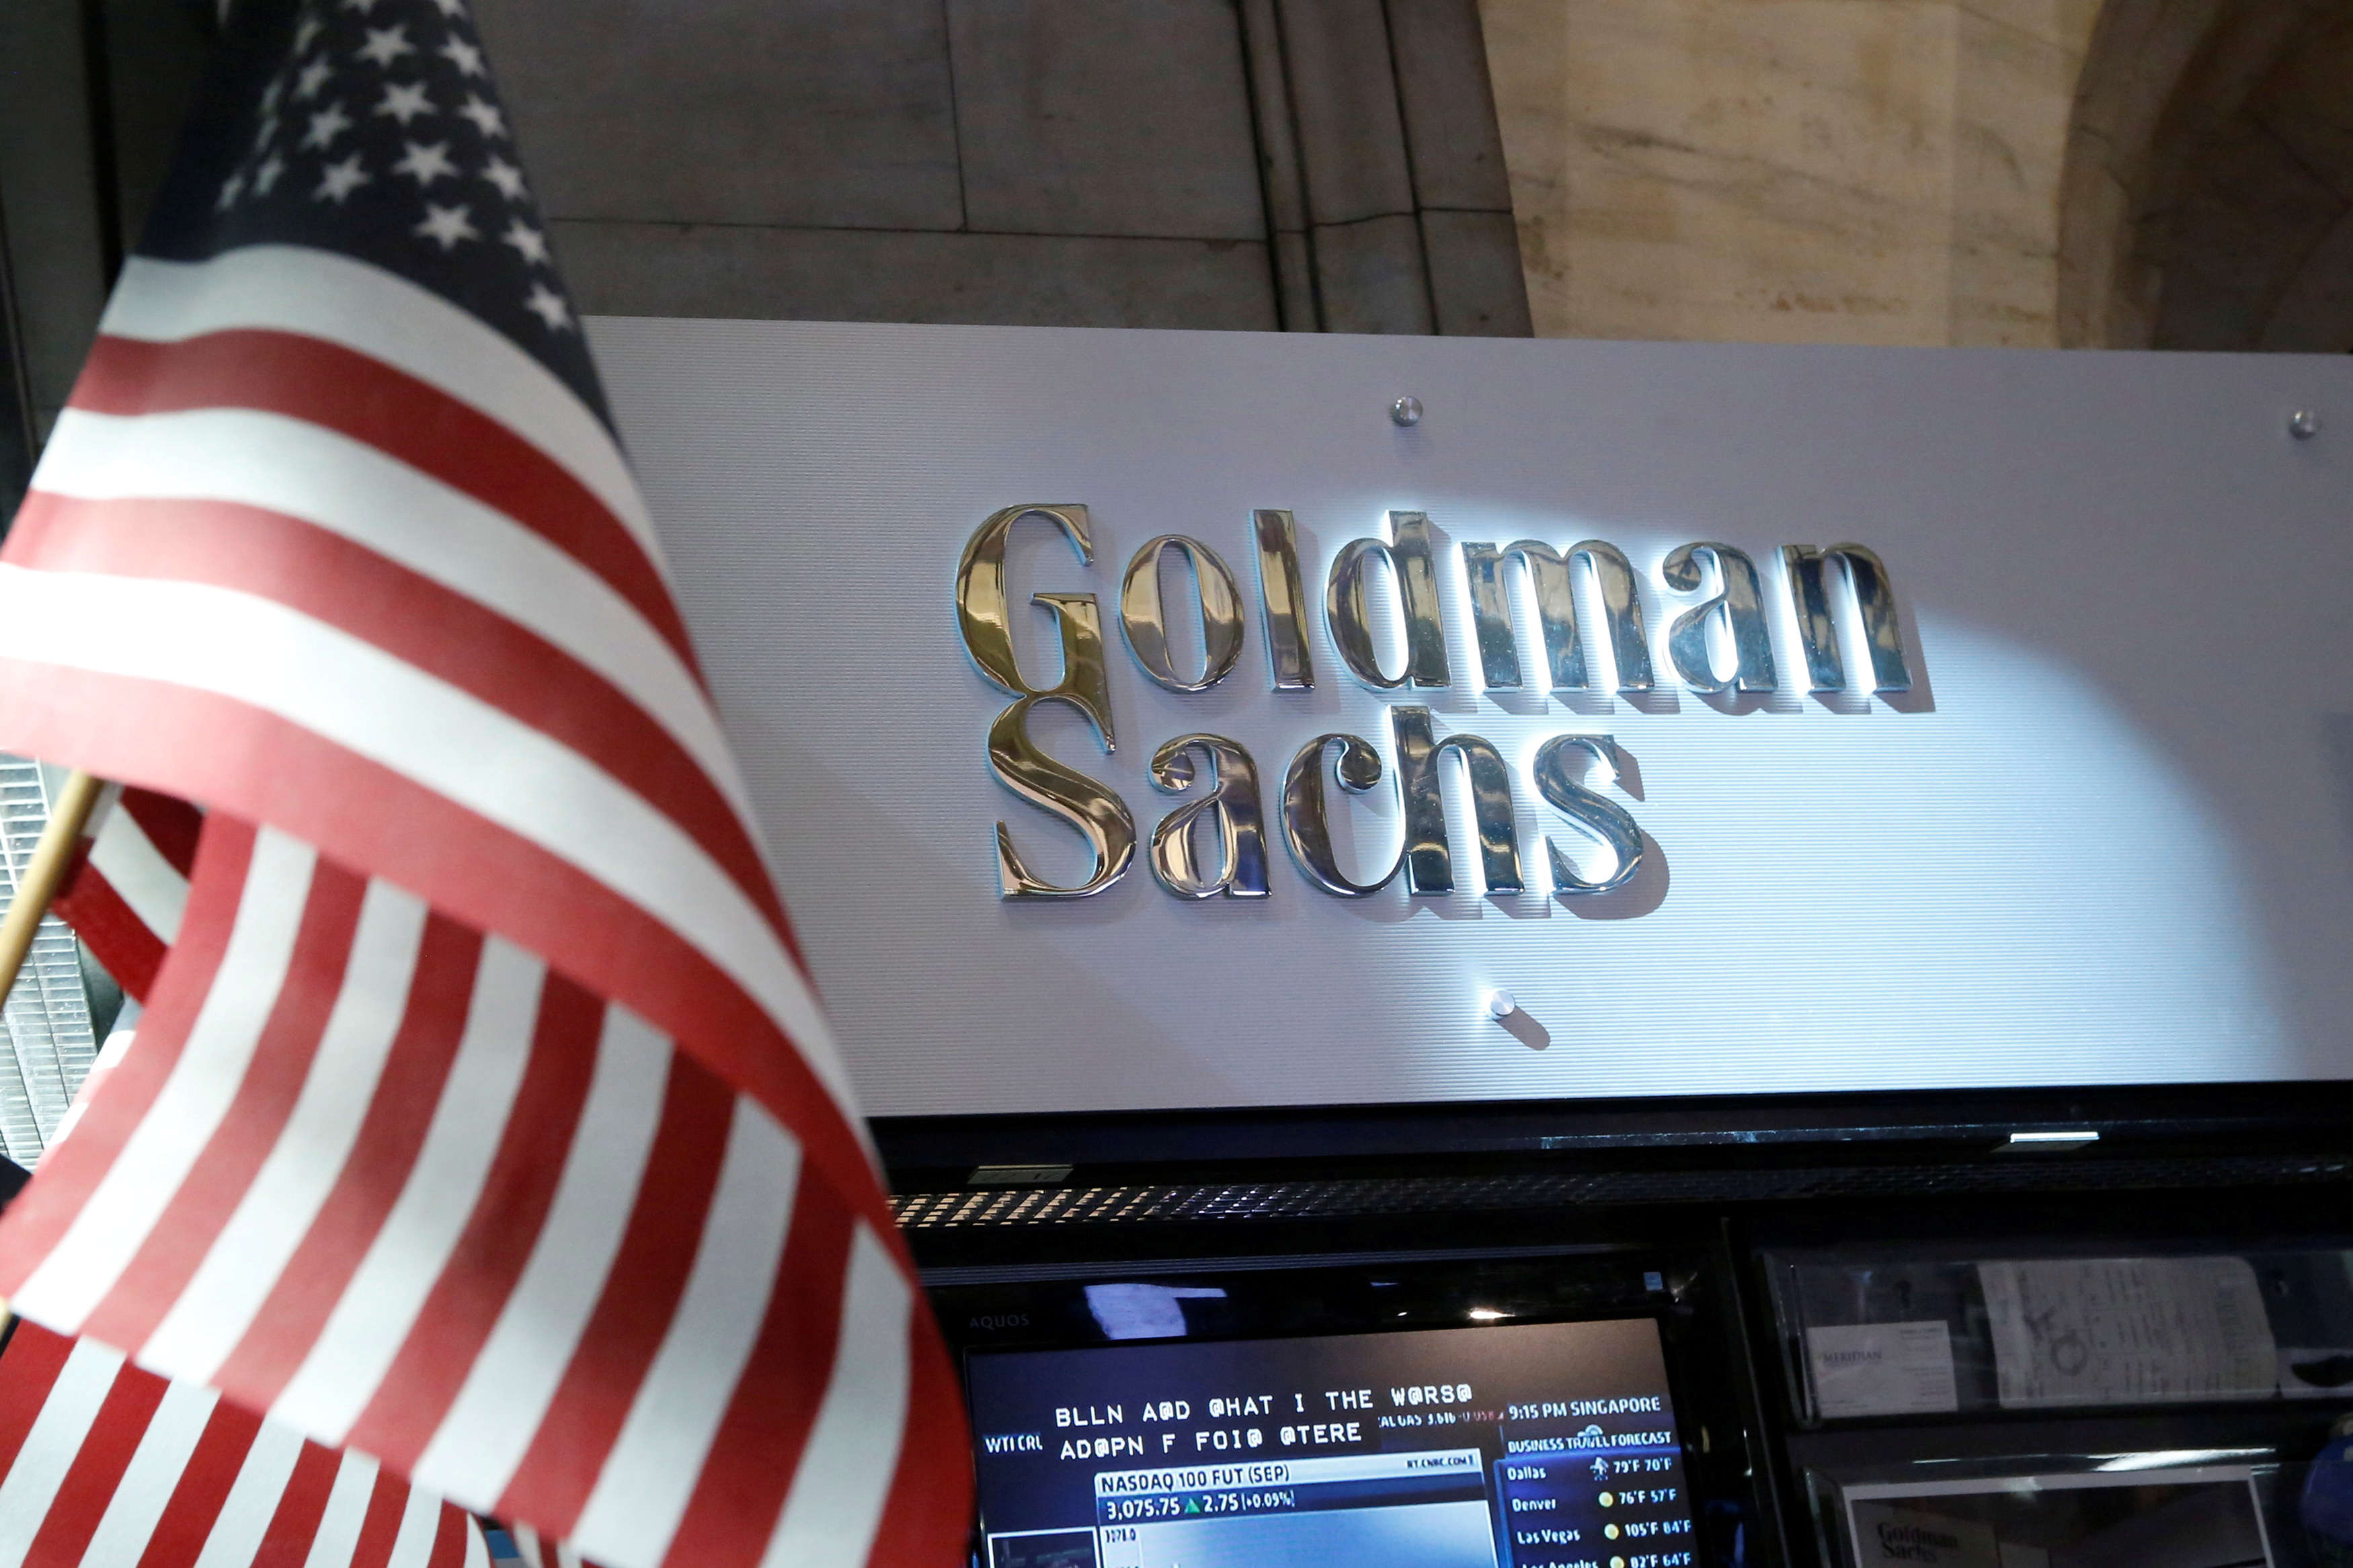
A see of the Goldman Sachs stall on the floor of the New York Stock Exchange July 16, 2013. REUTERS/Brendan McDermid

The bank’s fairness buying and selling profits much more than doubled from past yr to $3.1 billion. That was better than rival Morgan Stanley, which described trading revenue of $2.87 billion and is normally number one in this line of company.

Rival Morgan Stanley (MS.N) reported on Thursday that its 3rd-quarter gain rose 38{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, even though JPMorgan Chase & Co (JPM.N) described a 24{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} rise. go through extra Citigroup Inc. (C.N) and Financial institution of The usa Corp (BAC.N), which have been likewise buoyed by offer costs and equities buying and selling, increased gains by 48{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} and 64{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, respectively. All the banking institutions handily conquer estimates.

Contrary to JPMorgan, Citigroup and Bank of America, which have sizable buyer banking companies, Goldman is seriously reliant on its buying and selling organization and investment decision financial institution.

Consumer Enterprise

Goldman’s customer company, while compact, has been important to its diversification strategy.

As component of Main Govt David Solomon’s method to create substitute revenue streams, Goldman is now doubling down on Marcus, its customer financial institution.

Considering that having above from Lloyd Blankfein in 2018, Solomon has appeared to diversify revenue, with a lot more emphasis on buyer banking, mass-current market prosperity administration and cash administration.

Web earnings in Goldman’s shopper banking device rose 17{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $382 million, reflecting increased credit card and deposit balances.

Full financial loans increased 28{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $143 billion in the quarter from a 12 months previously, a powerful consequence in a blended quarter for bank loan expansion across Wall Road.

JPMorgan stated on Wednesday that financial loans were up 5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} across the lender compared with very last yr, when Citi was broadly flat. go through extra

Financial institution of The us (BAC.N) and Wells Fargo (WFC.N) described declines in bank loan growth year-on-12 months.

Total revenue surged 26{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $13.61 billion in the quarter, handily beating estimates.

Reporting by Noor Zainab Hussain and Anirban Sen in Bengaluru, Elizabeth Dilts and Matt Scuffham in New York Enhancing by Arun Koyyur and Nick Zieminski

Our Requirements: The Thomson Reuters Have confidence in Rules.

Principles for Ethical and Effective Financial Market Regulation

Principles for Ethical and Effective Financial Market Regulation

The 2008 financial crisis is an obvious example of a poorly functioning financial sector—but not because financial markets were deregulated in the 1990s. In fact, the primary causes of the 2008 crisis were excessive government regulation, over-involvement, and poor monetary policy. Financial firms funded too much unsustainable activity largely because of the rules and regulations they faced, as well as the widespread expectation that the federal government would step in to mitigate private losses.

The dominant narrative of that time—that financial market deregulation, including the supposed 1999 repeal of the Glass–Steagall Act, caused the 2008 crash—is dead wrong. The Glass–Steagall Act was not repealed in 1999,REF and at no point during the 20th century was there a substantial reduction in the scale or scope of U.S. financial regulations: In fact, the sheer number of financial regulations steadily increased after 1999.REF For decades, policymakers have appealed to the seemingly special nature of financial firms to heavily regulate them, often in the name of preventing turmoil from spreading to the rest of the economy. Increasingly, financial regulations have focused on risk management conducted by regulatory agencies rather than on disclosure and fraud prevention.

This approach has failed miserably. The U.S. has had 15 banking crises since 1837, a total that ranks among the highest of developed countries.REF Among severe economic contractions in six developed nations from 1870 to 1933, banking crises occurred only in the U.S.REF More recently, the U.S. is one of only three developed countries with at least two banking crises between 1970 and 2010.REF As federal interventions, such as central banking, deposit insurance, and loan guarantees, have become more widespread internationally, banking crises have occurred more frequently.REF

Risks of Misguided Regulation

The high level of misguided regulation is the source of most financial market problems. More intrusive, complex regulation favoring large incumbent firms is not the solution. Even very recent equity market disturbances, such as the controversy surrounding the short-selling of GameStop stock, cannot be legitimately blamed on the failure of the free market.REF

Industry Concentration. The ever-increasing regulatory burden imposed by the banking agencies,REF the Securities and Exchange Commission (SEC),REF the Financial Industry Regulatory Authority (FINRA),REF the Treasury Department’s Financial Crimes Enforcement Network (FinCEN),REF and other federal and stateREF regulators has led to a relentless decline in the number and profitability of small broker-dealers and banks and to increasing concentration in the financial sector. The regulatory costs and regulatory risks are such that small broker-dealers—and banks—have difficulty competing and remaining profitable.REF Regulatory costs do not increase linearly with size. There are massive regulatory-induced barriers to entry and economies of scale that adversely impact small businesses, entrepreneurship, innovation, and competition.REF

System-Wide Uniformity. It is long past the time for the U.S. to move to a less prescriptive regulatory system, one that is based on fraud deterrence and disclosure and in which private actors—not taxpayers—absorb the losses from unwarranted risks. Such an approach would reduce the system-wide risk uniformity that was so problematic during the 2008 crisis and would also reduce the regulatory burden on smaller upstart financial institutions, increasing their competitiveness and reducing concentration in the industry.

Financial enterprises are the arteries through which money from one sector of the economy flows into others.REF Smoothly functioning financial markets result in a more productive and innovative society with more goods and services, more employment opportunities, and higher incomes. They make it easier and less costly to raise the capital necessary for launching or operating a business, to borrow money for buying or building a home, and to invest in ideas that improve productivity and increase wealth.

These companies are not so exceptional, however, that they require rules and regulations to replace the judgment of owners, employees, and investors with those of government bureaucrats. Indeed, financial markets are still markets. The same economic principles that apply to other segments of the economy apply to the financial sector. Across all sectors of the economy, excessive government regulation prevents firms from best serving the needs of their customers and, therefore, society.

Financial firms do have certain distinct characteristics because of the tasks that they perform, but the same is true of companies in all sectors of the economy. The distinct characteristics of any private-sector industry (or individual company) should not dictate the extent to which government officials regulate and direct decision-making. Federal officials have no special knowledge regarding the best way to serve banking customers or investors. In fact, there is strong reason to believe that centralized government decision-making is inferior to decentralized private decision-making by those closer to the situation—and with a personal stake in the outcome of the decision.REF

Seven Core Principles of Financial Regulation

History has already demonstrated that a federally micro-managed financial system does a good job of protecting incumbent firms—to the detriment of the typical American worker and investor. A new market-based approach, one founded on the following seven principles, would be far superior to the current regulatory framework. It would expand economic opportunities and help more people achieve financial security.

1. Market discipline is a better regulator of financial risk than government regulation. Rather than forcing banks to adhere to arbitrary capital standards set by regulatory fiat, policymakers should introduce more market discipline—the process by which customers and investors make financial decisions based on their views of acceptable risk levels—into the financial system. Ultimately, this process will enable market participants to set their own capital rules based on the ability to tolerate risk. While allowing market participants to determine the appropriate capital levels fails to guarantee a stable banking system and macroeconomy, evidence clearly shows that allowing regulators to set statutory capital requirements fails as well. Both theory and evidence suggest that the financial system will perform better when financial firms face more market discipline.REF

2. Government should promote well-functioning capital markets by deterring and punishing fraud and by fostering reasonable, scaled disclosure of information material to investors’ financial choices. The core purpose of securities market regulation is deterring and punishing fraud and fostering reasonable, scaled disclosure of information that is material to investors’ financial choices. Fraud is the misrepresentation of material facts or the misleading omission of material facts for the purpose of inducing another to act, or to refrain from action, in reliance upon the misrepresentation or omission.

Appropriate mandatory disclosure requirements can promote capital formation, the efficient allocation of capital, and the maintenance of a robust, public, and liquid secondary market for securities. The reasons for this are: (1) the issuer is in the best position to accurately and cost-effectively produce information about the issuer; (2) information disclosure promotes better allocation of scarce capital resources and has other positive externalities; (3) the cost of capital may decline because investors will demand a lower risk premium; (4) disclosure makes it easier for shareholders to monitor management; and (5) disclosure makes fraud enforcement easier because evidentiary hurdles are more easily overcome.

The baseline for measuring the benefits of mandatory disclosure is not zero disclosure. Firms would disclose considerable information even in the absence of legally mandated disclosure. It is, generally, in their interest to do so. Firms conducting private placements today make substantial disclosures notwithstanding the general absence of a legal mandate to do so. The reason is straightforward: In the absence of meaningful disclosure about the business and a commitment (contractual or otherwise) to provide continuing disclosure, few would invest in the business—and those that did would demand substantial compensation for undertaking the risk of investing in a business with inadequate disclosure. Voluntary disclosure allows firms to reduce their cost of capital and they would, therefore, disclose information even in the absence of a legal mandate to do so.

Mandatory disclosure laws often impose substantial costs. These costs do not increase linearly with company size. Offering costs are larger as a percentage of the amount raised for small offerings. These costs, therefore, have a disproportionate adverse impact on small firms. Moreover, the benefits of mandated disclosure are also less for small firms because the number of investors and amount of capital at risk is less. Since the costs are disproportionately high and the benefits lower for smaller firms, disclosure should be scaled so that smaller firms incur lower costs.REF

Moreover, mandates for corporate governance or requirements for the disclosure of information that is not material to the financial performance of the firm, including politically motivated Environmental Social Governance disclosure, is not warranted.REF

3. The government should remain neutral with respect to Americans’ financial choices. The federal government should not interfere with the financial choices of market participants, including consumers, investors, and uninsured financial firms. Regulators should also refrain from crafting rules that provide financial incentives for certain types of capital investments over others. Regulators should, on the other hand, focus on protecting individuals and firms from fraud and violations of contractual rights, as well as creating the institutional framework for a vibrant capital market.

It is not a proper function of government to protect people from making poor business or investment decisions or from bad luck. Private markets do a better job of allocating capital than the government, and government regulators do not have better investment judgment than private citizens investing their own money. Public–private partnerships designed to shape financial markets, such as government-sponsored enterprises, abuse this principle.

In practice, they misalign incentives and create rent-seeking opportunities, often leading to economic turmoil. Even offering incentives for one type of investment through tax incentives violates this principle and diverts capital from more productive uses. All regulations directed at restricting investor choice and substituting regulators’ investment judgment for that of investors should be discarded.

4. The cost of financial firm failures should be borne by equity holders, creditors, and managers—not by taxpayers. Financial firms should be permitted to fail, just as other firms are. Government should not “save” participants from failure. Doing so impedes the ability of markets to direct resources to their highest and best use. In fact, the socialization of the risk of loss via government backing increases the willingness to take unwarranted risk, reduces (rather than enhances) stability, increases concentration in the financial industry, rewards politically connected actors, and imposes an unfair burden on customers and taxpayers. Even conveying special status on large financial firms, such as through a systemically important designation, inevitably impedes the functioning of markets and leads to government bailouts that socialize private losses.

5. Speculation and risk-taking allow markets to operate. Interference by regulators attempting to mitigate risk-taking hinders the effective operation of markets, even when regulators favor investments in “real economic interests” versus “purely speculative” investments. Recent regulations aimed at quelling excessive speculation in derivatives markets, for instance, have created a system that concentrates (previously decentralized) risks in a small number of specialized clearing firms.REF

Federal regulators have no special insight into which financial risks are connected to so-called legitimate economic interests—the term is subjective and, therefore, allows regulators to substitute their judgment for those investors risking their own money.

6. The government should preserve citizens’ right to use whichever forms of money they choose. Policymakers rarely think about improving the quality of money with the same competitive market forces that improve other goods and services. These forces push entrepreneurs to innovate and improve products to satisfy customers, and they expose weaknesses and inefficiencies in existing products, thus improving people’s lives. Economists generally acknowledge that private competitive markets produce such benefits, but many view money as an exception that should be provided by the government. Yet the government’s actual record of monetary stewardship is poor, thus showing the importance of preserving citizens’ ability to use whichever forms of money or other digital assets that they choose. Nothing can provide as powerful a check on the government’s ability to diminish the quality of money as allowing competitive private markets to provide it. Suppressing such competition only deprives citizens of beneficial innovations in the means of payments.

7. To promote competition, entrepreneurship, and innovation, regulations should be clear, relatively simple, and straight-forward, and the administrative burden on capital market participants should be moderate. The current high degree of complexity and a high regulatory burden helps incumbent firms and harms innovation, entrepreneurship, and small businesses. It makes U.S. capital markets less efficient, harms productivity and wages, and reduces investor choice.

Conclusion

The dominant narrative remains that financial market deregulation caused the 2008 financial crisis—but that account is dead wrong. To the contrary, the government’s extremely active role in directing financial markets, along with its promises to absorb the losses of private risk-takers, brought about the crash. For decades, policymakers have appealed to the seemingly special nature of financial firms to heavily regulate them, often in the name of preventing turmoil from spreading to the rest of the economy. Even though this approach has failed miserably, financial regulations have increasingly focused on risk management conducted by regulatory agencies rather than on disclosure and fraud prevention.

Even if the 2010 Dodd–Frank Act, Congress’ response to the 2008 crisis, were repealed in its entirety, the highly flawed regulatory structure that weakened financial markets and contributed mightily to the crash would remain. A new market-based approach to financial regulation—one founded on the seven principles described in this Backgrounder—would be far superior to the current framework.

A regulatory approach based on these ideas would focus on fraud deterrence and material disclosure. It would foster a market in which private actors—not taxpayers—absorb the losses from unwarranted risks. This much-improved framework would reduce the regulatory burden on smaller upstart financial institutions, increasing their competitiveness and reducing concentration in the industry, ultimately leading to more economic opportunities and financial security for Americans.

Norbert J. Michel, PhD, is Vice President and Director of the Center for Monetary and Financial Alternatives at the Cato Institute. David R. Burton is Senior Fellow in Economic Policy in the Thomas A. Roe Institute for Economic Policy Studies, of the Institute for Economic Freedom, at The Heritage Foundation.