Rivian Automotive Downgraded by Investment Analysts due to Disappointing Financial Results

Rivian Automotive Downgraded by Investment Analysts due to Disappointing Financial Results

April 15, 2023 – Rivian Automotive (NASDAQ:RIVN), the electric auto producer, has been downgraded by financial commitment analysts Piper Sandler from an “overweight” rating to a “neutral” rating. The report was issued on Friday and has raised some eyebrows in the investment decision neighborhood.

This comes after Rivian Automotive printed its earnings final results for the past quarter of February 28th. The figures disclosed that the enterprise confirmed ($1.73) EPS for the quarter, beating the consensus estimate of ($1.89) by $.16. Even though this appears spectacular at first look, more examination demonstrates that Rivian Automotive had a adverse return on fairness of 37.49{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} and a negative internet margin of 407.24{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

The business’s quarterly earnings was $663 million in the course of the quarter, which was considerably below analysts’ approximated profits of $729.47 million. It must be mentioned that in the course of the same interval in the prior year, the organization attained ($2.43) earnings for every share, indicating some improvement.

In spite of constructive movements in direction of profitability, it appears Rivian however has a way to go prior to buyers are persuaded to fee them “overweight.” Analysts predict that Rivian Automotive will post a disappointing -5.52 EPS for this economic 12 months substantially even worse than previously predicted.

Rivian Automotive styles, develops, manufactures, and sells electrical cars, specially five-passenger pickup vehicles and sports utility vehicles called Experience Vehicles®, emphasizing ease of use and sustainability features with up to 400 miles of driving range for EV motorists.

Just one saving grace could be partnering with Amazon.com to manufacture an electric Supply Van on their platform built explicitly for delivery use by Amazon.com personnel straight targeting fleet functions focused in towns wherever diesel vans normally supply deals through neighborhoods generating air pollution related to minimizing carbon emissions into our environment remains very important.

Rivian is indeed working in an revolutionary market where by technologies is vital to development consequently, there’s continue to a lot opportunity for expansion in the potential. The enterprise have to tweak its strategies, specifically about pricing, enlargement of product offerings, and perhaps a rebranding that would bring in a much more substantial market place share. All matters thought of, Rivian Automotive can bounce back again with sound management and innovation in direction of creating sustainable, inexpensive cars for all.

Offer-facet analysts reduced goal prices for Rivian Automotive amidst disappointing fiscal overall performance


Rivian Automotive, Inc, the electric powered motor vehicle maker, has recently been in the information following numerous promote-aspect analysts decreased their focus on rates for the stock. The decreased targets arrive after Rivian Automotive failed to meet marketplace expectations and suffered a sizeable correction to the conclusion of Q1. Mizuho slash their focus on price on March 9th from $37.00 to $35.00 and set a “buy” rating for the firm. Cantor Fitzgerald also slashed its forecast from $30.00 to $27.00 while assigning an “overweight” score on March 1st.

Evercore ISI and Royal Financial institution of Canada joined in on March 6th and 1st respectively, reducing their cost targets from $35.00 to $25.00 and dropping their concentrate on price tag from $50.00 to $28.00 but nonetheless maintaining an outperform score for Rivian’s shares.

Wells Fargo & Business gave a important downturned prediction by lowering their focus on value on February 24th from $32.00 to just $18. Rivian’s shares opened at just about fifty percent of that worth the inventory opened at only $14.37, down from a twelve thirty day period high of $41.90, which was recorded previous year.

Moreover, Bloomberg.com described that two expenditure analysts have assigned a offer rating even though five many others rated Rivian Automotive as higher than regular or usual about its functionalities while 13 investment decision analysts rate it as acquire stock as a result we can say that inventory has a consensus score of “Moderate Buy” and an ordinary rate concentrate on of $32.50.

Rivian Automotive has launched 5-passenger decide-up vans along with athletics utility motor vehicles which are bought immediately to buyers throughout each business and purchaser markets by leveraging its hottest release of the Rivian Commercial Motor vehicle system in collaboration with Amazon.com.

In recent insider transactions at Riven Automotive documented via SEC filings, CAO Jeff Baker and CFO Claire Mcdonough each marketed important portions of shares last February. Also, 2.34{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of the stock is owned by company insiders.

In spite of the standard downturn of Rivian Automotive’s stock over Q1 2023, some hedge resources just lately improved their stakes in the electric auto firm. Gould Money LLC lifted its position by 175.4{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, while Clearview Wealth Advisors LLC and WFA of San Diego LLC all opened new positions in the enterprise well worth $27,000 and $28,000 respectively all through Q4 2022. Resurgent Money Advisors LLC also acquired a new stake in Rivian Automotive truly worth roughly $30,000 last quarter.

As for the company’s economical performance more than the final calendar year, it delivered reduce than predicted benefits that prompted numerous promote-facet analyst residences to lower their concentrate on price ranges on Rivian’s inventory thanks to this disappointing efficiency predominantly resulting in Rivian Automotive’s correction over Q1 2023 analysts are now contending for variations within just oversupply and competition in EV markets in fact building anticipations tricky to sustain for the marketplace.

Amazon curbs no-fee returns as retail’s ‘laissez faire’ era fades

Amazon curbs no-fee returns as retail’s ‘laissez faire’ era fades

Amazon (AMZN) has designed its e-commerce empire by producing searching reasonably priced and foolproof. You failed to like the pan you acquired on Amazon? No anxieties, you had free returns.

Nonetheless, the days of throughout-the-board absolutely free returns are more than: Amazon is instituting a $1 payment on some returns, marking a notable shift from the company’s early days when the ethos was grow-at-all-prices.

Yahoo Finance spoke to 5 retail experts about this sea modify, and they did agree that this was a lengthy time coming and retail at-big is transferring in this direction.

“I imagine the business must be kissing the ground Amazon walks on for returning the sector to some semblance of financial sanity,” Professor Mark Cohen, director of retail research at Columbia Business School, advised Yahoo Finance. “There’s almost nothing in this lifetime that is totally free, so returns that are absolutely free develop a huge load for vendors. They’re eventually heading from a ‘laissez faire’ view… This type of move had to be unavoidable.”

John Talbott, senior lecturer at Indiana University’s Kelley College of Enterprise, observed that Amazon’s newly-minted return costs are also directed towards a certain form of client.

“I believe this exertion is targeted at buyers that are gaming the system,” Talbott told Yahoo Finance. “By that I necessarily mean, they are regular, testers, and returners… By undertaking this, Amazon is basically taxing the habits of a small section of the overall populace, and remaining greater equipped to provide those that are legitimately buying a product or service or services, and totally intend to use it.”

Amazon Prime boxes are loaded on a cart for delivery, Oct. 10, 2018 in New York. (AP Photo/Mark Lennihan)

Amazon Primary packing containers are loaded on a cart for delivery, Oct. 10, 2018 in New York. (AP Picture/Mark Lennihan)

The knowledge on what returns charge merchants is staggering: In 2022, buyers sent again about 17{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of the items they bought, truly worth $816 billion, for each Countrywide Retail Federation data.

“These returns are these a load for merchants, not only as a logistical expense, but as a provide chain trouble,” Cohen added. “Items will not return to the exact same warehouse, and that goods also typically has to be resold as a distressed item.”

No-return-charge procedures just were not crafted to final, CEO of Merchandising Metrics Jeff Sward instructed Yahoo Finance.

“It was definitely inevitable,” he stated. “‘Free’ grew to become the most highly-priced term in retail. Free of charge delivery and cost-free returns have been brilliant as buyer acquisition equipment, but they now have to have to be looked at as an financial investment in making a shopper base. That financial commitment needs to see some ROI at some level. Free of charge returns supplied a form of basic safety net to get people today snug shopping on the net – mission achieved. The ease and comfort of free of charge returns has place the return rate by the roof, and it is unsustainable.”

‘The whole thought is to adjust client behavior’

Amazon’s return fee hike will very likely change customer actions in some ways — the query is in what way and by how much. In any scenario, changing how some buyers interact with Amazon — specially these vulnerable to screening and returning merchandise — is specifically what the enterprise is hoping for.

“The whole plan is to change purchaser habits, if only subtly,” Spieckerman Retail President Carol Spieckerman explained to Yahoo Finance. “The expenses use when different locations, such as Kohl’s or Whole Meals, are closer. Supplied the plan aspects, Amazon may perhaps not be trying to offset return charges so much as boost the probability that buyers will make impulse buys that gain Amazon and its partner suppliers. The nominal charge isn’t sufficient to infuriate consumers and Amazon’s competitors could even want it were being increased.”

Feed-back Team Principal Brian Numainville agreed, telling Yahoo Finance that fees of significantly less than $2 will most likely not be more than enough to induce a riot, specially due to the fact these costs only utilize in choose situations. Nonetheless, there will be some annoyance to go close to, and the products that individuals essentially acquire might adjust more than time, as well.

“When it could be an irritant for some buyers and several dislike added costs, it is really not very likely that this nominal return cost will bring about a remarkable amount of money of upheaval in buyer behavior, exterior of potentially altering in which some purchasers return Amazon things to match within just the other ‘no-fee’ alternatives,” Numainville said. “A greater challenge that I believe could have a a lot more obvious affect is the ‘usually returned‘ marker on some merchandise pages, which could sway a shopper to avoid obtaining an product, wondering why it is regularly returned. That could change buyer habits absent from these things and end result in various getting outcomes.”

For Columbia’s Cohen, it all goes back again to inevitability: “I think some prospects will be put off a little bit, but I also feel they’ve been waiting around for this working day… Amazon has been quietly disenfranchising shoppers for many years who are criminally involved or just enjoying with them. They have to begin spending consideration their fundamental profitability, and this is a step in the appropriate course for them.”

Anthropologie is another retailer that has instituted some return fees. (Anthropologie website)

Anthropologie is a different retailer that has instituted some return fees. (Anthropologie site)

‘It’s really hard to put the genie back again in the bottle’

In all chance, merchants throughout the board will probable use this as an opportunity to start charge for returns.

“I think the business is going to shift in lockstep with Amazon,” said Cohen. “I assume the transfer will be slow, but other merchants will shift in the course that Amazon is heading, working with Amazon as a protect.”

Upping return charges will remain a fragile dance between firms and their clients.

“Much more vendors are trying to implement return service fees, but all know they will have to tread evenly,” said Spieckerman. “It’s challenging to place the genie back in the bottle, and Amazon introduced it in the very first area.”

The up coming period of e-commerce will likely glimpse instead distinct, as the business model is in flux.

“The lack of profitability in the universe of e-commerce is perfectly acknowledged,” Sward mentioned. “Returns are not the only element in that lack of profitability, but they are a major chunk of it. The e-commerce organization design is in the center of an evolutionary system that’s searching for sustainable profitability.”

But there’s just one matter you can be guaranteed of: The days of indiscriminate totally free returns are around.

“The field is relocating absent from this ‘anything goes, anytime’ philosophy that’s just a killer financially,” Cohen mentioned. “I consider this is the starting of a host of alterations we are likely to see as the field receives on much better footing economically.”

Allie Garfinkle is a Senior Tech Reporter at Yahoo Finance. Comply with her on Twitter at @agarfinks and on LinkedIn.

Read the latest economical and organization news from Yahoo Finance

Obtain the Yahoo Finance application for Apple or Android

Abide by Yahoo Finance on Twitter, Facebook, Instagram, Flipboard, LinkedIn, and YouTube

JPMorgan Chase reports record revenue

JPMorgan Chase reports record revenue


New York
CNN
 — 

JPMorgan Chase

(JPM)
on Friday reported very first-quarter financial gain and earnings that roundly conquer expectations.

The New York-based financial institution posted a financial gain of $12.6 billion or $4.10 for every share. That is up from $8.3 billion, or $2.63 for each share from the very same time period a calendar year right before, or 52{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}. Analysts predicted earnings of $3.41 for every share, in accordance to Refinitiv.

The enterprise also guided net fascination earnings to be about $81 billion in 2023, up $7 billion from its preceding estimate.

With $3.67 trillion in assets, JPMorgan Chase is the premier lender in the United States and a bellwether for the US economic climate.

“The US financial state proceeds to be on frequently healthier footings — shoppers are nevertheless investing and have strong equilibrium sheets, and companies are in excellent condition. However, the storm clouds that we have been monitoring for the earlier calendar year continue to be on the horizon,” CEO Jamie Dimon mentioned in a push release.

Deposits rose to $2.38 trillion all through the first quarter from $2.34 trillion in the quarter ended in December. That will come after past month’s banking meltdown induced a rush into major banks from nervous prospects. Buyers also seemed to funds industry cash as a haven.

A essential position of dialogue immediately after final month’s turmoil has been regardless of whether financial institutions would tighten lending specifications, primary customers to shell out much less as it gets to be far more difficult to borrow money for significant buys like residences and cars and trucks.

But Dimon advised traders in the company’s put up-earnings meeting call that he is not nervous about a credit history crunch after the banking disaster.

“I would not use the phrase[s] ‘credit crunch,’” he stated in response to a problem about irrespective of whether he was concerned that lending would tighten in the bank soon after the collapse of Silicon Valley Lender and Signature Financial institution. “I just search at it as a variety of a thumb on the scale. It just helps make the funding situations a minor bit tighter and raises the odds of a economic downturn.”

Still, firms really should still brace for the probability that curiosity fees keep on being bigger for extended than envisioned, he said. Although the Federal Reserve has signaled that it will pause charges later this 12 months, fairly easing considerations about climber prices, Dimon managed that the financial system isn’t out of the woods just yet.

“People need to be organized. They shouldn’t pray that they never go up. They should prepare for them going up. And if it does not take place, serendipity,” he mentioned.

JPMorgan Chase explained its publicity to place of work space is constrained, as concerns that the $20 trillion commercial actual estate sector is the future shoe to fall right after the banking tumult linger above Wall Road.

“Given the recent target on commercial authentic estate, let me remind you that our office sector exposure is fewer than 10{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of our portfolio and is concentrated in urban dense marketplaces, and approximately two-thirds of our loans are multifamily, generally in provide-constrained marketplaces,” mentioned Jeremy Barnum, main monetary officer.

The commercial authentic estate industry’s woes come just after many years of unbridled expansion run by reduced interest premiums and simple credit score. That upward craze was interrupted by the Covid pandemic’s onset, and then when the Federal Reserve begun climbing desire prices aggressively very last yr to stabilize the economic system. The change to operating from home has eroded the price of structures as workplaces stay vacant or half-empty.

Shares of JPMorgan Chase were up 6.7{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} Friday morning.

‘Fed-is-going-to-stop-soon’ trade peters out in stocks, bonds amid prospect of at least one more rate hike

‘Fed-is-going-to-stop-soon’ trade peters out in stocks, bonds amid prospect of at least one more rate hike

A blend of hawkish remarks by a pair of Federal Reserve officials, good lender earnings experiences, and a rebounding buyer-sentiment studying on Friday are among the the aspects contributing to a different abrupt readjustment in the economic market’s considering about the route of desire charges.

The unexpected readjustment dented the popular look at that the Federal Reserve may well be approaching the conclude of its yearlong amount-hike cycle. All three important U.S. inventory indexes
DJIA,
-.18{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}

SPX,
-.21{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}

COMP,
-.35{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}
completed reduce, although Treasury yields jumped — led by a 39.5-foundation-issue increase in the 1-month T-invoice fee
TMUBMUSD01M,
4.109{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996},
according to Tradeweb. The ICE U.S. Dollar Index
DXY,
+.56{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}
jumped .5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}. And fed funds futures traders boosted the chances of Fed fee hikes in May perhaps and June, while paring their expectations for charge cuts later on this calendar year.

“Everything the marketplace believed as of the close yesterday was contradicted these days,” mentioned Steve Englander, the New York-based mostly head of worldwide G10 Fx study and North The us macro approach for Standard Chartered Financial institution. As he put it, “everything went incorrect in the ‘Fed-is-likely-to-quit-soon’ trade,” while any foreseeable future spillover from the banking-connected strain has the prospective to curtail coverage makers’ fee-hike cycle.

Friday’s information provided a report from the College of Michigan, which confirmed buyer sentiment creeping up and People in america much more nervous about higher inflation. And although retail profits tumbled by more than expected in March, some folks noticed the probable for even further weak point, which didn’t arrive to fruition, Englander said. On major of this, JPMorgan Chase
JPM,
+7.55{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}
and Citigroup Inc.
C,
+4.78{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}
claimed very first-quarter benefits that delighted investors.

See: JPMorgan Chase inventory moves good for the yr immediately after it blasts previous earnings and earnings estimates

Meanwhile, two Fed policy makers stepped into the fold with hawkish responses. Fed Gov. Christopher Waller claimed he sees the require for the central lender to continue to keep boosting rates, whilst Atlanta Fed President Raphael Bostic told Reuters that latest inflation knowledge “are regular with us relocating one particular extra time.”

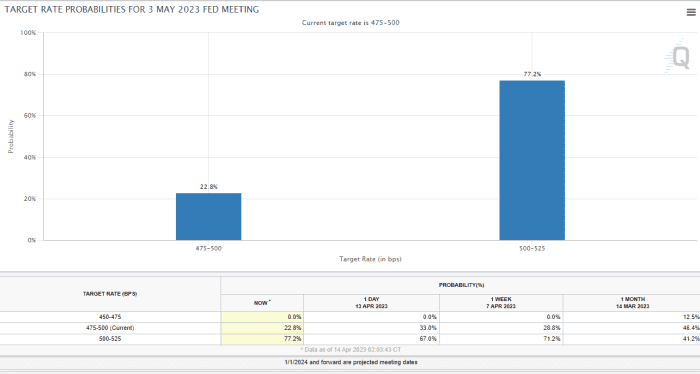
As a end result, fed funds futures traders set a far more than 70{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} prospect on an additional quarter-of-a-percentage-position charge hike in May, which would elevate the Fed’s main curiosity-rate concentrate on to amongst 5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} and 5.25{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, and they boosted the probability of a comparable-size go in June, in accordance to the CME FedWatch Instrument.


Resource: CME FedWatch Device, as of Friday.

“The million-dollar question is, ‘how significantly much more does the Fed have to do?’”  said Rob Daly, director of set earnings at Glenmede Financial investment Administration in Philadelphia. “I’m in the camp that believes it could be just one or two more hikes, but the upcoming problem is, ‘how prolonged do they maintain costs elevated?’”

“Risk assets have remained unbelievably resilient, we’ve witnessed a pretty strong labor industry, and inflation is nonetheless higher,” Daly stated by means of cellular phone. “I do not see any purpose the Fed would be reducing costs whenever before long. The knowledge has been resilient and not always weak enough for the Fed to alter system.”

Visit Pittsburgh disputes audit from Allegheny County Controller

Visit Pittsburgh disputes audit from Allegheny County Controller

An audit by the Allegheny County Controller made public Thursday found the agency responsible for Pittsburgh’s tourism advertising failed to stick to accurate financial management practices, and demands to raise transparency.

Pay a visit to Pittsburgh, which is dependable for tourism advertising in the location, receives much more than 90{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of its funding from tax pounds, according to County Controller Corey O’Connor.

“They’re acquiring taxpayer dollars,” O’Connor explained to WESA. “This is a noteworthy expenditure of taxpayer dollars that wants to be accounted for.”

In accordance to the controller’s report, Take a look at Pittsburgh deposited private and community funds into the exact financial institution account and did not correctly track the use of general public funds, which includes resources obtained from the Allegheny County resort tax.

Stop by Pittsburgh mentioned it disagrees with the conclusions, and claimed the report contains “factual problems, deceptive information and facts and the selective omission of relevant facts.”

The agency’s president and CEO Jerad Bachar said Check out Pittsburgh’s accounting procedure is “in complete compliance with GAAP [Generally Accepted Accounting Principles] and FASB [Financial Accounting Standards Board] guidelines.”

The audit also endorses Stop by Pittsburgh reduce its reserves, which at the moment sit just underneath $5.3 million.

That is larger than reserves in comparable towns like Baltimore, the controller’s office environment stated. Baltimore’s reserves hover around $840,000.

But Bachar explained the reserves provide multiple uses, and aided the business make it via the COVID-19 pandemic.

“We’re fully confident that our methods are quite significantly in tips, very considerably within just appropriate specifications,” he said.

Bachar also insinuated the audit was prompted by political calculations, which O’Connor denied.

“We are looking at straight details. We are not heading to make this stuff up,” O’Connor said. “We are peer reviewed.”

Point out Sen. Wayne Fontana requested the audit in September 2022 mainly because he had “grave concerns” about how Go to Pittsburgh was handling “millions of bucks in community county lodge space rental tax revenues.”

Fontana is the chairman of the board for the Sports and Exhibition Authority of Pittsburgh and Allegheny County, which owns Acrisure Stadium, PPG Paints Arena, PNC Park, and the David L. Lawrence Conference Centre.

He also opposed an more rate on Allegheny County hotel rentals that would have boosted Stop by Pittsburgh revenues.

Bachar mentioned Go to Pittsburgh will take into account some of the controller’s other recommendations.

Browse the comprehensive audit and Check out Pittsburgh’s reaction right here.

AvalonBay Communities, Inc. Receives Hold Rating from Financial Analysts with Growing Interest in Future Growth Prospects

AvalonBay Communities, Inc. Receives Hold Rating from Financial Analysts with Growing Interest in Future Growth Prospects

As of April 14, 2023, the ordinary ranking bestowed on AvalonBay Communities, Inc. (NYSE:AVB) by twenty-1 economical analysts is a “Hold,” studies Bloomberg.com. Though two financial commitment analysts issued a provide ranking, eleven remained neutral and five have rated the enterprise as a acquire. The average 12-month goal rate between brokers that covered AVB in the past yr is $201.21.

AvalonBay Communities, Inc is a actual estate have confidence in that serves as an marketplace leader in producing, obtaining, proudly owning, and operating multifamily communities. It operates less than a few key segments – Proven Communities, Other Stabilized Communities, and Development or Redevelopment Communities.

Shares of AVB opened at $170.07 on Friday, owning recorded a 1-year minimal of $153.07 and achieving its highest level at $258.81 inside of the very same interval. The company’s 50-day uncomplicated going typical registered at $170.62 even though its 200-day straightforward transferring common was recorded at $170.65. At present, AvalonBay Providers has a sector capitalization of $23.80 billion with a value-to-earnings ratio of 20.97 and beta worth of .91.With consideration to valuation ratios like Value-To-Sales(PS) ratio stands at all around 7x calculated based on analyst estimates for FY2024E.The company’s PEG ratio stands at 3.10 indicating that it’s trading fairly expensive in contrast to underlying growth anticipations .The company’s credit card debt-to-equity ratio stood business at .74 symbolizing moderate leverage, while rapid and recent ratios had been registered at healthy stages of above two moments.

In conclusion,it appears that the attention surrounding AvalonBay Firms has seen superior progress potential clients which are reflected in 5 get scores from connected analysts.Based mostly on long term projections,it would be ideal for traders to undertake mindful exploration prior to creating any investment decision decision on AVB stock. With a respectable sized current market capitalization and institutional protection,it’ll be interesting to see how the upcoming number of quarters unfold for AvalonBay Communities.

AvalonBay Communities Gets Sequence of Rankings and Focus on Price tag Revisions from Analysts


AvalonBay Communities, a major true estate financial investment rely on (REIT), has gained a series of rankings and price tag target revisions from a variety of research analysts. Truist Monetary was the first to raise AvalonBay’s rating from “hold” to “buy” and enhanced its value focus on for the inventory by $4.00 to $190.00.

Wells Fargo & Firm adopted accommodate, issuing an “overweight” ranking for the firm with a selling price focus on of $184.00 for each share. Mizuho lifted their goal value on shares of AvalonBay Communities from $179.00 to $188.00 and gave the stock a “neutral” ranking in a research report on Thursday, February 23rd.

Evercore ISI elevated shares of AvalonBay Communities from an “in-line” rating to an “outperform” ranking and established a $194.00 value aim for the company in a investigate observe on Monday, even though JPMorgan Chase & Co decreased AvalonBay Communities’ rating from “neutral” to “underweight”, dropping their value goal for the stock from $206.00 to$197.00.

Also, many substantial traders have a short while ago produced modifications to their holdings of the stock, together with Parkside Financial Lender & Believe in rising its posture in AvalonBay Communities by 100{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, Massmutual Believe in Co.FSB ADV growing its stake by 290{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, Adirondack Retirement Professionals Inc getting a new placement in AvalonBay Communities value $38,000, CVA Family Business LLC boosting its place by 1333{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} and IFP Advisors Inc growing its stake by 51.9{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

AvalonBay Group also introduced information that it had boosted its quarterly dividend payout ratio – which will be compensated out on Monday, April 17th – up from its former payout price by 6 cents for every share or close to $6.60 utilizing annualized values.As per data from December 2022, institutional buyers and hedge money personal the broad the greater part of the company’s shares at 87.30{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

This spree of activity around AvalonBay Communities has understandably designed a good deal of excitement all over the REIT, as traders seem to capitalize on its current gains in rank and profitability projections. As we progress further into 2023, it will be interesting to see no matter if these predictions occur to fruition or if the fortunes of this leading real estate expenditure have faith in will choose another turn for greater or worse.