Loans to Wealth Management Clients Lift Raymond James’ Earnings

Loans to Wealth Management Clients Lift Raymond James’ Earnings

Lending to rich shoppers lifted nevertheless a different brokerage firm’s revenue.

Raymond James Economic

documented that a 82{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} 12 months-more than-year surge in desire profits boosted income through the 2nd calendar quarter and offset declines in other income lines.
Raymond James headquarters


Courtesy of Raymond James

Wealth management corporations have progressively leaned into selling their rich customers home loans, securities-centered loans, and other lending merchandise. Doing so enables advisors to serve clients’ lending and investing needs. At the exact time, wealth managers’ base line is now benefiting from the mounting rate setting.

Raymond James reported curiosity income rose to $374 million for the quarter from $242 million for the similar interval previous 12 months. Full income increased 11{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} 12 months around 12 months to $2.8 billion. 

The company seems established to mature its lending business enterprise. All through the quarter, Raymond James shut its acquisition of TriState Cash Holdings, a Pittsburgh-centered lender and asset manager that specializes in lending to significant-web-worthy of clients. Whilst Raymond James helps make securities-primarily based loans to customers of its advisors, TriState does so through other intermediaries, these types of as RIAs, belief corporations, and other economic establishments. 

Total financial institution financial loans, such as Raymond James and TriState, soared 75{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $41.8 billion, in accordance to the business. CEO Paul Reilly claimed that even if curiosity costs increase, securities-dependent financial loans will continue to be a popular choice and more cost-effective resource of credit history for specified customers.

“SBL financial loans are in demand and rising,” Reilly claimed during an earnings convention call July 28.

Raymond James noted that internet revenue obtainable to typical shareholders fell 3{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $299 million due to elevated expenditures. Organization development prices, for occasion, soared 87{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $58 million.

CFO Paul Shoukry, talking throughout the phone, mentioned the company hosted an advisor meeting and other situations. Personnel are also traveling much more for enterprise as opposed to final year. In addition, Raymond James paid a a person-time reward to reduced-paid staffers to support personnel cope with inflation.

“It’s about using treatment of associates who have done a good career,” CEO Paul Reilly said throughout the contact. “Our turnover is up, but it’s decreased than the industry.”

Raymond James’ client property beneath administration slipped 10{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} from the very first calendar quarter of this calendar year to $1.125 trillion, reflecting down markets. Other wealth administration firms seasoned comparable declines during the second quarter. 

The transfer of independent prosperity administration organization Steward Partners from Raymond James’ broker-dealer to the company’s RIA custody unit caused in general advisor headcount to decline. Raymond James does not include advisors involved with the RIA custody small business in its headcount. The company stated it experienced 8,616 unbiased and personnel advisors as of June 30, down 114 in contrast with March 31.

Generate to Andrew Welsch at andrew.welsch@barrons.com

Sector trends – July 2022: Asset/Wealth Management

Sector trends – July 2022: Asset/Wealth Management

With over 350 deals in the European AWM sector in 2021, M&A consolidation activity is hotter than it has ever been in the past 15 years. Conventional wisdom is now under the microscope—is bigger really better?


Overview

Current Market

  • High activity levels—no signs of slowing down

We Are Seeing

  • Market consolidation rumbles on at pace:
    • Predominantly smaller domestic opportunities—the UK and Switzerland being focal points
    • Healthy sprinkling of medium-sized deals—the UK, the Netherlands and Italy experience the most activity
    • Few market-defining deals (e.g., Amundi’s acquisition of Lyxor AM and Goldman Sachs’ acquisition of NN Investment Partners)
  • Differing bank strategic objectives:
    • Some banks go all-in (e.g., UBS’s acquisition of Wealthfront)
    • Other banks fold (e.g., Danske Bank’s disposal of its Luxembourg WM business)
  • Specialist sub-sector consolidation:
    • Fund management (e.g., Abrdn’s acquisition of Interactive Investor)
    • Financial planning (e.g., Perspective’s quad— acquisitions of Prolific, Evolve, Bowman and Quantum)
  • Tax advisory (e.g., Ludlow’s inside straight draw— acquisitions of Saffron and Charter)

Key Drivers/Challenges

  • Europe’s asset/wealth managers continue to believe consolidation is optimal to:
    • Expand client bases and catchment demographic
    • Tap wider spectrum of asset class offerings
    • Secure expertise of specialist fund managers
  • Replenished M&A war chests of active asset managers, especially those offering sustainable investment products
  • Significant uptick in customer familiarity with low-cost DIY wealth management platforms (e.g., FINVIA, TiFIN and EveryoneInvested)
  • Strong investor appetite for Europe’s asset/wealth managers from:
    • Private equity investors (e.g., Apex’s acquisition of Sanne)
    • Foreign investors (e.g., Federated Hermes’s acquisition of remaining 29.5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of Hermes Fund Managers)
    • Institutional investors (e.g., £1.2 billion LSE IPO of Petershill Partners)
    • Management (e.g., Auréus Group’s MBO)
  • Digital asset class behemoths flex M&A muscle (e.g., CoinShares’ acquisitions of Napoleon Crypto and Elwood Asset Management)
  • Hunt for on ESG-compliant asset class penetration and active portfolio management capability

Trends to Watch

  • Increasing enforcement action and mis-selling claim risk in the ESG arena:
    • Regulators scrutinise asset managers’ sustainable investment disclosures
    • UK asset managers are forced to publish environmental impact data under new Sustainability Disclosure Requirements regime


Our M&A Forecast

Consolidation activity to continue, but early signs that scale and profitability do not necessarily go hand in hand.


Market consolidation

Deal highlight: 

White & Case advised BNP Paribas Asset Management, the largest shareholder of EAB, on EAB’s merger with Evli. 

Deal highlight: 

White & Case advised Catella Group, the Sweden-based fund management business, on the sale of its remaining 30{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} stake in Catella Fondförvaltning to Athanase. 

The wave of fund manager M&A that drove global deal numbers to a record high last year has run into 2022, with the value of transactions in the first four months of 2022 its highest since 2018. (Financial News, May 2022) 

Deal numbers reach record high. There have been 362 M&A deals in the European fund management sector in 2021—comfortably beating the 279 that were struck in 2020. (Financial News, December 2021) 

Investment experts are beginning to question the wisdom of the recent flood of M&A among asset managers since they’re often followed by fleeing funds and falling share prices. (Financial News, October 2021) 

Smaller deals between asset managers are running at the hottest pace in almost 15 years as businesses hunt for tactical acquisitions instead of bigger, riskier purchases. (Financial Times, September 2021)

Larger: 

  • EAB & Evli (Finland): Merger (May 2022)
  • Aviva (UK): Acquisition of Succession Wealth (March 2022)
  • Amundi (France): Acquisition of Lyxor Asset Management (January 2022)
  • Goldman Sachs (Netherlands): Acquisition of NN Investment Partners (August 2021)

Mid-sized:

  • Banca March (Spain): Acquisition of BNP Paribas Private Banking Spain (February 2022)
  • M&G (Switzerland): Acquisition of 90{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of responsibility Investments (February 2022)
  • River&Mercantile & AssetCo (UK): Merger (January 2022)
  • Kingswood Holdings (UK): Acquisition of Metnor Holdings (January 2022)
  • Raymond James (UK): Acquisition of Charles Stanley (December 2021)
  • Schroders (UK): Acquisition of 75{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of Greencoat Capital (December 2021)
  • LGT (Australia): Acquisition of Crestone Wealth Management (December 2021)
  • Schroders (UK): Acquisition of River & Mercantile’ solutions division (October 2021)
  • Cardano (Netherlands): Acquisition of ACTIAM (October 2021)
  • BNP Paribas Asset Management (Netherlands): Acquisition of majority stake in Dynamic Credit Group (September 2021)
  • Max Matthiessen (Sweden): Acquisition of Naventi Fonder (September 2021)
  • Abrdn (UK): Acquisition of EXO Investing (August 2021)
  • Zurich (Italy): Acquisition of Deutsche Bank Financial Advisors (August 2021)
  • Raymond James Financial (UK): Acquisition of Charles Stanley Group (July 2021)
  • Poste Italiane and Intesa Sanpaolo (Italy): Acquisition of 40{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of Eurizon Capital Real Asset (July 2021)
  • Mattioli Woods (UK): Acquisition of Maven Capital Partners (July 2021)

Smaller:

  • Tern (UK): Acquisition of Pires Investments (June 2022)
  • Grupo Mutua (Spain): Acquisition of 24.41{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of Alantra Wealth Management (May 2022)
  • Tatton Asset Management (UK): Acquisition of 50{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of 8AM Global (April 2022)
  • Sienna Investment Managers (France): Acquisition of Acofi Gestion (March 2022)
  • Verso Wealth Management (UK): Acquisition of CDC Wealth Management (March 2022)
  • Magellim (France): Acquisition of Turgot Capital (February 2022)
  • Kingswood Holdings (UK): Acquisition of Joseph Lamb (February 2022)
  • Athanase (Sweden): Acquisition of remaining 30{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of Catella Fondförvaltning (February 2022)
  • Gonet & Cie (Switzerland): Acquisition of Banque Degroof Petercam (January 2022)
  • Decisive Capital Management (Switzerland): Acquisition of Artorius Wealth Switzerland (January 2022)
  • Vontobel (Switzerland): Acquisition of UBS Swiss Financial Advisers (December 2021)
  • Canaccord Genuity Group (UK): Acquisition of Punter Southall Wealth (December 2021)
  • Liontrust (UK): Acquisition of Majedie Asset Management (December 2021)
  • Kingswood Holdings (UK): Acquisition of Metnor Holdings Limited (November 2021)
  • Kingswood Holdings (UK): Acquisition of Money Matters (North East) (November 2021)
  • Primevest Capital Partner (Netherlands): Acquisition of Holland Immo (November 2021)
  • Hottinger (UK): Combination with Edmond de Rothschild’s UK wealth management operations (October 2021)
  • Kepler Cheuvreux (France): Acquisition of Ellipsis Asset Management (October 2021)
  • ODDO BHF Asset Management (France): Acquisition of METROPOLE Gestion (September 2021)
  • Storebrand (Denmark): Acquisition of Capital Investment (August 2021)
  • Titan Wealth (UK): Acquisition of Titan Asset Management (August 2021)
  • REYL & Cie (Switzerland): Acquisition of 40{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of 1875 Finance (August 2021)
  • AssetCo (UK): Acquisition of majority stake in Rize (July 2021)
  • AssetCo (UK): Acquisition of 30{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of Parmenion Capital Partners (July 2021)

JVs:

  • Sienna Investment Managers: French asset management JV with Malakoff Humanis (March 2022)


High investor appetite

Deal highlight: 

White & Case advised Oaktree Capital Management on its acquisition of UK private wealth management and investment businesses, Sanlam Wealth. 

PE firms have been buying up companies that advise individuals on their wealth, surging to a record 223 in 2021. (Financial Times, December 2021)

Financial sponsors (acquisitions):

  • Beka Finance/Gala Capital (Spain): Acquisition of Trea Asset Management (May 2022)
  • Motive Partners and Clearlake Capital (UK): Acquisition of BETA+ (March 2022)
  • Apex Group (UK): Acquisition of Sanne (August 2021)
  • Bonaccord Capital Partners (UK): Minority equity investment in Park Square Capital (January 2022)
  • Oaktree Capital Management (UK): Acquisition of Sanlam Wealth (September 2021)
  • Cinven Partners (UK): Majority (undisclosed) equity investment in True Potential (September 2021)

Financial sponsors (WealthTech funding rounds):

  • Hamilton Lane (WealthTech): Participation in US$47 million Series C funding round for TIFIN (October 2021)

Financial advisers/Investment banks:

  • Stephens Financial Services (Asset management): Acquisition of 20{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of CRUX Asset Management (April 2022)

Foreign investors: 

  • HPS Investment Partners (UK): Equity investment into Nucleus Financial Platforms (March 2022)
  • Agilis (US): Acquisition of River and Mercantile’s US solutions business (January 2022)
  • Federated Hermes (US): Acquisition of remaining 29.5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of Hermes Fund Managers (August 2021)

Market appetite:

  • Petershill Partners: £1.2 billion LSE IPO (September 2021)

MBOs: 

  • Auréus Group (Netherlands): MBO (January 2022)
  • Wergen & Partner Wealth Management (Switzerland): MBO (January 2022)


Differing FI prerogatives

UK investors turned their backs on passive funds in July 2021, favouring actively managed sustainable investment products which chalked up one of their best months on record. (Financial News, August 2021)

Tag-out (disposals): 

  • Julius Baer: Disposal of Fransad Gestion (June 2022)
  • Sovcombank: Disposal of Septem Capital (February 2022)
  • Julius Baer Group: Disposal of Wergen & Partner Wealth Management (January 2022)
  • Société Générale: Disposal of Lyxor Asset Management (January 2022)
  • UBS: Disposal of UBS Swiss Financial Advisers (December 2021)
  • Deutsche Bank: Disposal of Deutsche Bank Financial Advisors (August 2021)
  • BNP Paribas: Disposal of ClimateSeed (July 2021)
  • Danske Bank: Disposal of Luxembourg wealth management business (July 2021) 

Tag-in (acquisitions):

  • Royal Bank of Canada (UK): Acquisition of Brewin Dolphin (March 2022)
  • ANZ (UK): US$50 million equity investment in Pollination (February 2022)
  • Graubündner Kantonalbank (Switzerland): Acquisition of 30{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of Twelve Capital (January 2022)
  • Bank Syz (Switzerland): Acquisition of BHA Partners (January 2022)
  • UBS (US): Acquisition of Wealthfront (January 2022)
  • HSBC (India): Acquisition of L&T Finance’s Indian mutual funds business (December 2021)
  • Banco Desio e Brianza (Italy): Acquisition of 15{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of Anthilia Capital Partners (November 2021)
  • Renell Bank (Belgium): Acquisition of Merit Capital (October 2021)
  • HSBC Asset Management (US): Acquisition of minority stake in RadiantESG (July 2021)
  • Union Bancaire Privée (Luxembourg): Acquisition of Danske Bank’s Luxembourg wealth management business (July 2021)


Financial planning M&A

Financial sponsors:

  • Nordic Capital (UK): Acquisition of Ascot Lloyd (April 2022)
  • Andera Partners (France): Acquisition of (undisclosed) equity stake in Patrimmofi (September 2021) 
  • Lightyear Capital–backed MBO (UK): Acquisition of Wren Sterling from Palatine Private Equity (July 2021)

Trade consolidators:

  • Groupe Crystal (France): Acquisition of CP Conseils Finance (December 2021)
  • M&G (UK): Acquisition of Sandringham Financial Partners (August 2021)
  • Perspective Financial Group (UK): Acquisition of Prolific Financial Services (August 2021)
  • Perspective Financial Group (UK): Acquisition of Evolve Financial Management (August 2021)
  • Perspective Financial Group (UK): Acquisition of Bowman Financial Planning (August 2021)
  • Perspective Financial Group (UK): Acquisition of Quantum Portfolio Management (August 2021)
  • Lloyds (UK): Acquisition of Embark (July 2021)


Fund management M&A

Deal highlight:

White & Case advised JTC, the global professional services business, on its acquisition of Essential Fund Services, the private capital fund administration services specialist.

The corporate and fund services space has seen relatively consistent numbers of transactions involving Europe-based targets over the last few years, and data suggests that the trend will continue. (Mergermarket, July 2021)

  • ZEDRA (US): Acquisition of Atlas Fund Services (April 2022)
  • Apex Group (UK): Acquisition of majority stake in Fund Admin Chain (March 2022)
  • Abrdn (UK): Acquisition of Interactive Investor (December 2021)
  • JTC (USA): Acquisition of Essential Fund Services (December 2021)
  • Apex Group (UK): Acquisition of Sanne (August 2021)
  • Sanne (Isle of Man): Acquisition of PraxisIFM’s funds administration business (July 2021)
  • IQ-EQ (Ireland): Acquisition of Davy Global Fund Management (July 2021)


Tax advisory M&A

  • Ludlow Trust (UK): Acquisition of Saffron Tax Partners (April 2022) 
  • Ludlow Trust (UK): Acquisition of Charter Tax (April 2022)


Debt servicing/NPL management

  • Cerved Credit Management (Italy): Acquisition of Rev (June 2022)
  • Dunya Varlik Yonetim, Hisar Stratejik Yatirimlar Holding & Merkez Alacak Yonetimi Danismanlik ve Destek Hizmetleri (Turkey): Merger (April 2022)
  • Collextion (Italy): Acquisition of Whitestar (April 2022)


Asset management in the digital world

  • Caceis (France): Digital asset custody JV with Taurus (June 2022)
  • CoinShares (France): Acquisition of Napoleon Crypto (December 2021)
  • Afry (Sweden): Acquisition of Trivalo (October 2021)
  • Tatton Asset Management (UK): Fund management JV with Fintel (September 2021)
  • Standard Chartered (UK): Cryptocustody JV with Zodia Custody (July 2021)
  • CoinShares (UK): Acquisition of Elwood Asset Management Services (July 2021)


Digitalisation marches on

  • Amundi: Acquisition of Finventum (June 2022)
  • Moneybox: Successful £35 million Series D funding round led by Fidelity International Strategic Ventures (April 2022)
  • FINVIA: Successful €20 million funding round led by HANNOVER Finanz (March 2022)
  • M&G: UK direct investments JV with Moneyfarm (January 2022)
  • TiFIN: Successful US$47 million Series C funding round led by Hamilton Lane (October 2021)
  • EveryoneInvested: Spare change investment JV with Mastercard (September 2021)
  • Wise: WealthTech JV with BlackRock (September 2021)


Click here to download ‘Financial institutions M&A: Sector trends — Other FS’ PDF


FULL MAGAZINE
Financial institutions M&A: Sector trends

SUBSCRIBE
Stay current on your favorite topics


This publication is provided for your convenience and does not constitute legal advice. This publication is protected by copyright.
© 2022 White & Case LLP


Cetera Welcomes Old Second Wealth Management

Cetera Welcomes Old Second Wealth Management

$150 million practice joins Cetera’s neighborhood for tax industry experts from LPL

Progress means and devoted help attract Chicago-space group to Cetera

LOS ANGELES, July 26, 2022 /PRNewswire/ — Cetera Economical Group, a person of America’s greatest networks of economical industry experts, announced these days that Aged Next Wealth Administration, led by Shahzad Shamsuddin, has affiliated with Cetera Financial Professionals, LLC, which serves tax experts who give wealth management providers. Old 2nd Prosperity Management oversees practically $150 million for shoppers and was formerly affiliated with LPL. The staff is aspect of Old Second Nationwide Bank, which has around 40 branch offices in the Chicago place and serves around 1,500 purchasers.

“Following watchful thought, we are delighted to join the Cetera Fiscal Experts neighborhood,” Shamsuddin mentioned. “The advancement assets and committed, local help will aid our exercise prosper and empower us to much better provide our shoppers for the long expression. We seem ahead to many shared successes for our clients and our apply and are proud to affiliate with Cetera.”

“We welcome Shahzad and his group to the Cetera relatives and look forward to collaborating to aid the team’s purchasers attain their edition of financial wellbeing, “said Ron Krueger, head of Cetera’s group of tax specialists. “As Shahzad and his group carry on to serve clients’ tax and prosperity administration demands, Cetera Financial Professionals is committed to providing the guidance and methods to travel beneficial benefits. Shahzad shares our shopper-1st values and frame of mind, and we are confident that his practice will achieve new heights at Cetera.”

“Shahzad and like-minded monetary industry experts proceed to appreciate the importance of high quality of assistance and operations for their teams, and a lot more importantly – their purchasers,” claimed John Pierce, head of organization growth at Cetera. “Cetera provides best-in-course service and guidance without extensive phone hold out instances or being referenced as a “rep number.”

Shamsuddin represents a person of the newest recruiting wins for Cetera, which not long ago announced document 2nd quarter business development effects. Cetera attracted $3.6 billion in the 2nd quarter of 2022, adhering to various vital additions to its sourcing and engagement group.  

Simply click in this article to study much more about Cetera Financial Professionals.  

About Cetera Money Group®
Cetera Monetary Team (Cetera) is a foremost economical providers agency whose goal is to empower the supply of ideal-in-course monetary suggestions to as several Americans as doable. Cetera empowers its money experienced communities to assistance customers reach their edition of money wellbeing through the Assistance-Centric Practical experience®. Cetera proudly serves unbiased financial gurus, tax industry experts, financial institutions and credit rating unions in delivering broad-ranging money arranging and wealth administration expert services.

Cetera oversees roughly $353 billion in property under administration and $122 billion in assets underneath administration, as of December 31, 2021.

Take a look at www.cetera.com, and comply with Cetera on LinkedIn, Twitter and Fb.

“Cetera Monetary Group” refers to the community of independent retail corporations encompassing, between some others, Cetera Advisors LLC, Cetera Advisor Networks LLC, Cetera Expense Services LLC (promoted as Cetera Economical Institutions or Cetera Buyers), Cetera Monetary Specialists LLC, and Initially Allied Securities, Inc. All firms are users FINRA/SIPC. Located at: 655 W. Broadway, 11th Flooring, San Diego, CA  92101.

People today affiliated with Cetera firms are either Registered Reps who supply only brokerage expert services and get transaction-primarily based compensation (commissions), Expense Adviser Representatives who give only investment decision advisory products and services and get service fees primarily based on property, or both equally Registered Reps and Expenditure Adviser Reps, who can give the two sorts of services.

Supply Cetera Money Team

Financial Management: DOE and NNSA Have Opportunities to Improve Management of Carryover Balances

Financial Management: DOE and NNSA Have Opportunities to Improve Management of Carryover Balances

What GAO Discovered

The Division of Energy’s (DOE) Business office of Environmental Administration (EM) and the National Nuclear Protection Administration (NNSA) oversee the cleanup of DOE’s legacy websites and the procedure of the nuclear protection organization, respectively. Most resources that Congress appropriates to EM and NNSA remain offered for obligation right until they are expended (costed). Balances not obligated or costed can usually be carried more than to future fiscal years, but these carryover balances can accumulate beyond the minimum desired to support plans, tying up resources that could be set to other works by using.

GAO reviewed 5 locations connected to EM’s and NNSA’s administration of carryover balances:

Finances structures and spending budget execution processes. EM and NNSA execute cash dependable with congressional route that buildings their appropriations into courses, projects, and functions (PPA). Nonetheless, the expanding period of continuing resolutions has affected EM’s and NNSA’s capacity to proficiently execute money and has contributed to carryover balances accumulating over and above what might be anticipated.

Amounts and ages of carryover balances at the conclude of fiscal year 2021. EM had about $3.2 billion in complete carryover balances, and NNSA experienced about $10.9 billion. Whilst the the vast majority of these balances have been built obtainable until expended, only 1.4 per cent of the total $14.1 billion was appropriated more than 5 years back, indicating that EM and NNSA have usually ensured that older resources ended up put in just before newer cash.

Methods for determining uncosted balances that warrant increased scrutiny, and the amounts of these balances at the end of fiscal calendar year 2021. DOE and NNSA have applied benchmarks, or thresholds, since 1996 to keep an eye on uncosted balances for working actions. DOE files point out that 12 months-close balances exceeding these thresholds warrant greater scrutiny. At the close of fiscal yr 2021, EM and NNSA experienced about $3.5 billion in such uncosted balances. EM and NNSA also experienced $3.1 billion in uncosted balances for line-product building assignments. On the other hand, according to DOE, line-merchandise construction initiatives are not issue to the thresholds and really should be examined on a circumstance-by-scenario basis.

Drivers of uncosted balances in extra of thresholds, and steps taken to regulate these balances. A amount of drivers contribute to uncosted balances in excessive of thresholds. Some motorists, these as continuing resolutions or larger-than-asked for appropriations, could completely explain an surplus harmony. Nonetheless, other individuals, such as unanticipated changes in function scope or method execution problems or delays, may perhaps not entirely describe an excess equilibrium. EM and NNSA periodically overview these balances and have in some cases taken actions to take care of them, such as searching for to reprogram excess money to PPAs with larger require, decreasing upcoming fiscal years’ price range requests, and modifying contract scope.

Limits to thresholds, and steerage applied to take care of excessive uncosted balances. GAO identified 5 limitations:

  • Thresholds, and how they need to be applied, are not obviously documented, major to cases of inconsistent application.
  • Bases for two thresholds produced just after 1996 are not nicely justified, impacting irrespective of whether they are reputable indicators.
  • EM and NNSA have not periodically reviewed thresholds to ensure that fundamental assumptions—for illustration, that appropriations will be timely—have not changed, influencing their reliability.
  • EM and NNSA have not documented a process to guide assessments of, and justifications for, balances in extra of thresholds, so it is unclear no matter if the businesses continuously determine that balances in excessive of thresholds are warranted.
  • No steering exists on how staff members really should use facts about excessive uncosted balances all through the funds formulation process to make sure that DOE ideas to price tag excessive balances or redirect money to regions of need to have.

The thresholds serve as equipment to watch DOE’s money effectiveness. Consequently, it is crucial that the thresholds operate properly as indicators in identifying balances that warrant greater scrutiny and that DOE plainly documents direction for their use.

Why GAO Did This Research

Congress has expected DOE to publicly report on carryover balances and has shown desire in being familiar with how DOE identifies and displays these balances. A committee report accompanying the Senate invoice for the Countrywide Protection Authorization Act for Fiscal Year 2021 included a provision for GAO to assessment EM’s and NNSA’s management of carryover balances.

GAO examined DOE and NNSA spending budget execution and economic management paperwork and analyzed fiscal facts as of the stop of fiscal year 2021 for each EM appropriation account and NNSA’s Weapons Things to do and Protection Nuclear Nonproliferation appropriation accounts. GAO interviewed agency officers about how EM and NNSA handle excess uncosted balances and take into account them when building foreseeable future funding requests.

Wealth Management Becoming More Attractive to Providers

Wealth Management Becoming More Attractive to Providers

With cost compression and other current market pressures in the defined contribution house, economic planning and prosperity administration opportunities are getting a lot more appealing offerings to recordkeepers, plan advisors and other DC companies.  

In reality, various DC system suppliers are harmonizing their DC and prosperity management businesses to foster further, much more comprehensive interactions with retirement traders that prolong beyond their DC program, in accordance to The Cerulli Report—U.S. Retirement End-Trader 2022: Fostering Detailed Associations

In accordance to the firm’s investigate, about a third (34{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}) of energetic 401(k) contributors name their 401(k) supplier as their major supply of retirement preparing and information, adopted by a economical skilled (16{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}). Many individuals will stand to benefit from a superior-contact, thorough prosperity management romantic relationship exactly where they gain accessibility to additional state-of-the-art money setting up services, a broader expense option set and a lot more adaptable distributions, the study observes. 

“Retirement investors’ fiscal priorities typically change from quick preserving and debt administration fears to lengthier-time period, economic arranging things to consider as they progress by way of their careers and accumulate bigger wealth,” notes Shawn O’Brien, Affiliate Director at Cerulli.  

For contributors who do the job with advisors, the most significant solutions advisors supply are expense range (68{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}), decumulation arranging (61{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}) and retirement accumulation (58{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}), highlighting the need for detailed provider that guides participants by way of every phase of their daily life, the study notes.  

As for whom they rely on to offer tips, Cerulli located that advisors are the most trusted supply of expenditure assistance for the 33{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of members who function with just one, with 53{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} expressing their advisor is “very reputable.” Participants who do not get the job done with an advisor most have faith in expense information presented by their financial institution/credit union and 401(k) company. “Firms that build and increase associations with individuals through their functioning decades provide a easy, seamless transition from DC-focused asset accumulation to a additional holistic, money preparing and advisory encounter as they tactic retirement,” suggests O’Brien.  

Rollover Sector

As these, the option is ripe for retirement program companies, the report implies. Cerulli estimates that far more than $440 billion in DC assets were being rolled into IRAs with the aid of an advisor in 2021, exemplifying the prospective for sourcing wealth management business from the DC sector. Additionally, the huge bulk (86{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}) of advisor-intermediated rollover assets are by way of an existing advisor romance, as opposed to new advisor interactions, the analysis shows. “For wealth managers looking to seize rollovers from DC options, this data underscores the relevance of creating and nurturing associations with participants before in their occupations, yrs prior to possible rollover activities,” emphasizes O’Brien.  

Cerulli anticipates DC recordkeeper and intermediary consolidation—along with ongoing lawful and regulatory pressures—to continue to exert downward strain on fees in the DC current market, building economical planning and wealth administration products and services significantly beautiful to companies from a monetary standpoint. According to the investigation, the solutions are considerably a lot more profitable than pure-enjoy recordkeeping associations, in part due to the fact the wealth administration industry has been mostly insulated from the rigorous price compression expert in the asset administration and recordkeeping industries.

Supplied the desirable economics of prosperity administration relative to recordkeeping and program advisory methods, Cerulli anticipates that far more wealth professionals and DC strategy vendors will develop synergies in between these two organization units by means of strategic partnerships and mergers and acquisitions. 

By harmonizing their DC and wealth companies, companies can reach significant economical benefits for each franchises, O’Brien observes. “Factoring in the predicted ancillary income from converting DC members to wealth management shoppers may perhaps allow companies to offer you a lot more aggressive pricing on the DC side, serving to them earn added mandates,” he notes, noting that better “coopetition” amongst recordkeepers and program advisors could crop up as the two functions work to provide the program but at the same time contend for participant rollovers. 

On individuals points, a current Smart Rhino report, Retirement & Wealth Advisory Q2 2022 Spotlight, observes that curiosity in retirement and prosperity advisory M&A stays high and level of competition is powerful for acquisition targets. The report notes that a lot of of the retirement and prosperity advisory agency acquisitions more than the past five yrs have been executed by CAPTRUST, HUB, OneDigital, NFP, Marsh McLennan Agency, Sageview and most lately Earth Coverage with its PensionMark pickup.

“Each of these Corporations strategically have centered first on setting up multi-disciplinary office hubs inside of every of the main areas, and then filling their advisory talent inside of every single of the U.S. major marketplaces,” the report explains. 

As Markets Waver, Alternatives Hit Their Stride

As Markets Waver, Alternatives Hit Their Stride

A new report from Boston-dependent fiscal markets researcher Cerulli Associates discovered that allocations to specific substitute investment merchandise ticked up sharply this calendar year and that alternative techniques stay top of mind for extra advisors as equity and bond exposures are buffeted by inflation, increasing desire rates and geopolitical turmoil.

Advisor respondents mentioned they allocated an ordinary of 14.5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to choice investments in 2022, with plans to raise that allocation to 17.5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} above two several years. This is up from 10.5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} in 2021, but Cerulli scientists noted that the pool of respondents was most likely skewed in the two cases towards advisors who currently invest in options and that the real allocation to commodities and other possibilities is presently closer to 10{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} across the industry. Even so, the study still indicates considerable growth next many years of relative inertia.         

“Cerulli sees the recent market place ecosystem as a Goldilocks minute for option financial commitment distribution,” the report claimed. “Demand for earnings, inflation security, improved returns, and volatility dampening is coinciding with an increase in supply of goods that can help direct to these respective outcomes.”

Produced in partnership with Blue Vault, an options schooling useful resource for advisors, the choices-concentrated financial investment study was based mostly on a survey of 100 advisors—primarily at unbiased broker/dealers—and interviews with business experts.

Virag Shah, portfolio strategist at Van Leeuwen and Co., a $317 million registered financial commitment advisor centered in Princeton, N.J., said his firm amplified alternate allocations previously this year. “We included commodities,” he stated. “Not just power or oil, but a lot more wide, standard commodities these as metals and agriculture. We added individuals to the portfolio combine along with other items that we previously had formerly.” Shah approximated that, under existing marketplace ailments, firms really should be allocating at minimum 15{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of their portfolio to alternate tactics to see any significant gains.

The scenario is “getting stronger and much better,” he mentioned, to abandon the longstanding 60/40 portfolio allocation standard—one to which Van Leeuwen has under no circumstances adhered.

Minimizing exposure to public markets was advisors’ best purpose for making use of option financial investment merchandise in 2022, cited by 69{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of respondents, with volatility dampening and downside hazard defense a near second with 66{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of advisors. Other described targets contain money generation, portfolio diversification, increased returns, inflation hedging, demonstrating their own observe value propositions and responding to client requests.

“Wealth advisors are remaining reminded that it’s sensible to undertake an overall investment method of using broad diversification, which includes market place non-correlation techniques,” said Stacy Chitty, controlling husband or wife at Blue Vault.

“Advisors are increasingly knowledgeable of these product or service choices as a wave of the two classic and choice managers construct out capabilities and wholesalers access out to make clear the benefits of the exposures,” according to Cerulli Director Daniil Shapiro, who coauthored the report with Cerulli Analyst Wenyi Wei.

Across expense buildings, liquid choice mutual funds continue being the most well-liked, made use of by 68{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of advisors, followed by nontraded REITs (61{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}) and liquid choice ETFs (54{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}). Extra than 50 {21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of responding advisors stated that the illiquidity of other choice products is unsuitable for their purchasers, though also citing products complexity and high administration expenses as their best obstacles to investing in options with severely restricted liquidity. But curiosity in semiliquid selections saw a sharp increase in 2021.

Liquid solutions will continue to be a welcoming entry level,” mentioned Shapiro. But, he added, “tremendous opportunity exists for a lot less liquid solutions.”

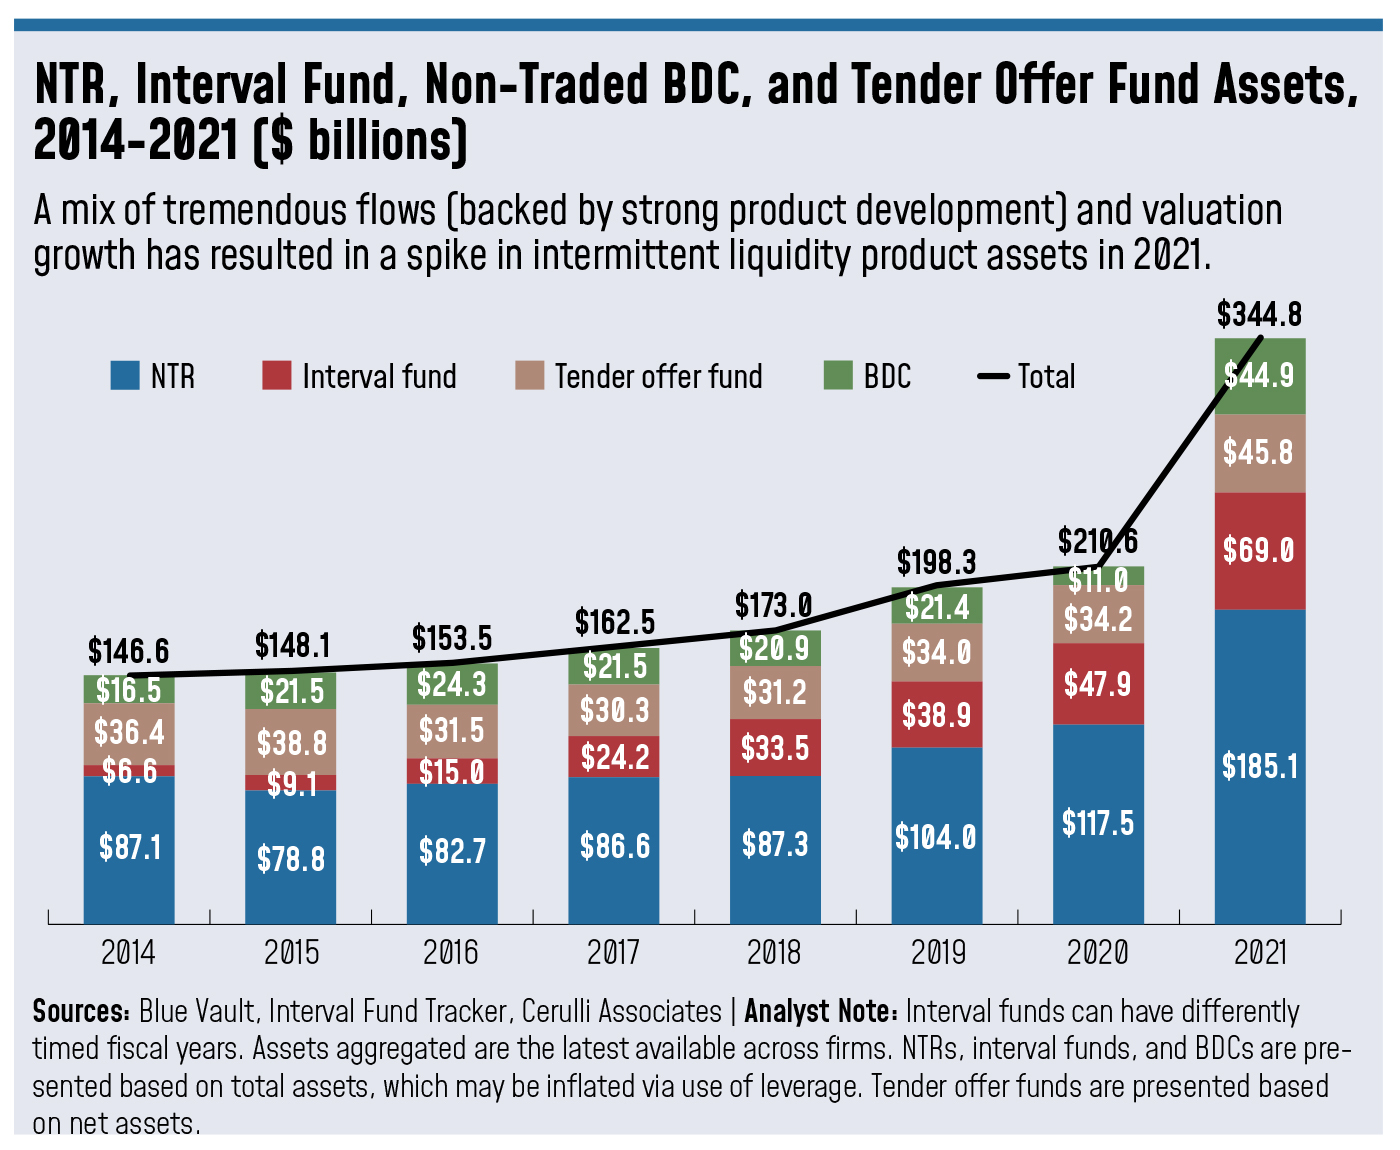
cerulli-alts-report-chart.jpg

Intermittent liquidity product allocations—to nontraded REITs, interval cash, nontraded company development organizations and tender offer you fund property—saw a 63.7{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} calendar year-about-yr improve in 2021, rising from $210.6 billion to $344.8 billion immediately after remaining beneath $200 billion while the previous 10 years.

A new generation of intermittent liquidity products and solutions is proving additional palatable to advisors than an earlier crop that observed temporary growth next the very last sector crisis, according to the report­. This is because of to a few major aspects: crucial M&A transactions (these types of as Franklin Templeton’s acquisitions of Benefit Avenue Companions and Alcentra and Apollo’s acquisition of Griffin Funds) product developments with enhanced consistency, performance and payment constructions and improvements in the distribution landscape, including the expansion of option financial commitment platforms these types of as CAIS and iCapital. Goods from trustworthy asset professionals these as Blackstone, KKR and Apollo are also lending to their escalating acceptance, Cerulli observed.

“Clearly, there is a marketplace prospect for products and solutions that present something concerning the extended-time period lockups of institutionally oriented constructions and the daily liquidity of most stock and bond funds,” stated Shapiro. “Cerulli believes there is a remarkable chance listed here.”

Van Leeuwen’s Shah agrees that intermittent liquidity items have been underrepresented in the industry and are established to see ongoing development above the subsequent five years. “A great deal of folks do not really know that market place that properly still,” he claimed. “I imagine there is a good deal of expansion prospect accessible down the highway.” He mentioned that he would individually like to see additional alternate options offer restricted liquidity, outside the house of the much more frequent real estate vehicles.

When the out there intermittent liquidity solutions have enhanced and “indeed show up to have strike their stride for investor portfolios,” Cerulli continue to suggests watchful analysis of all choice expenditure opportunities to establish suitability and insists that they not be viewed “as a panacea.”

“Firms looking to allocate much more to possibilities will require to be well prepared for special distribution challenges and have specialised personnel on hand to realize these products and solutions and their healthy within portfolios,” reported Shapiro.