Savers Want Better Financial Management. How Can Advisers Reach Them?

Savers Want Better Financial Management. How Can Advisers Reach Them?

A absence of fascination is no longer a excellent excuse. Despite the increase of robo-advisers, app-based mostly individual retirement accounts and very effective “set-it-and-forget about it” concentrate on-date fund approach options, several savers are looking for a good financial adviser, recent analysis reveals.

Fidelity Institutional, the brokerage, custody and adviser solutions arm of Fidelity Investments, unveiled investigate Tuesday noting that practically two-thirds of Millennial and Generation Z traders see doing work with a fiscal adviser as critical to their fiscal results. Meanwhile, a modern study from expenditure researcher YCharts observed that about one particular quarter of people now doing the job with an adviser have regarded switching to a distinct one because the onset of the pandemic, with 22{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} building the soar.

Both investigate experiences link to the businesses releasing them. Boston-based Fidelity declared a new set of instruments for advisers to attain young savers along with its conclusions. YCharts, based in Chicago, promotions in investigate, presentation tools and guides for advisers, asset administrators and investors. But the want for human link from program contributors and day to day savers is real, states Ryan Sullivan, a vice president and running director of utilized insights at Hartford Cash.

“The large challenge right now is finding people’s notice,” Sullivan suggests. “How do you get people’s consideration for retirement price savings? How do you intrigue people today plenty of to have a conversation about how it can profit them and for advisers to get them to give much more assumed to their financial overall health?”

Sullivan, who helps make his business enterprise doing work with registered financial investment advisers and described contribution expense selection companies, states the myriad of new financial resources for individuals generally does not deal with their primary concern of running out of revenue.

“There is this regular news barrage of things to fear about, from industry volatility to inflation to entire world conflict,” Sullivan claims. “The far more advisers can support people today realize this and give them a small more viewpoint, [that] can help them not be afraid to choose that upcoming stage in setting up.”

Know Your Customer

Adviser communications qualified Sullivan claims it is crucial for advisers to transfer outside of basic discussions about the worth of retirement saving and applications. Instead, an adviser really should get started with having to know the client, whether an person or a organization.

“Every adviser would like to be a scholar of the markets,” Sullivan suggests. “They want also to be a scholar of the business enterprise they are doing work with. If your big approach is a development business, find out extra about the industry, the alternatives and troubles they are struggling with. … They require to go around and over the idea that I want to have this plan and I’m hoping to deal with this company’s assets.”

He notes missteps such as an adviser calling a shopper a “small organization,” when in the client’s thoughts, it is not tiny at all. He also takes advantage of the example of an adviser who went out and volunteered with a firm for the duration of their volunteer working day.

“For your even bigger purchasers, this is a distinctive way to exhibit that you practically confirmed up to a thing which is crucial to them that does not make you a dime,” he says.

According to the YCharts study, consumer communication is not just a good-to-have, but a small business differentiator. A lot more than a single-third of 671 economical adviser customers surveyed in December 2022 stated they are contacted infrequently by their adviser, while extra than 88{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} stated they take into consideration their adviser’s frequency and style of conversation when determining to keep their solutions.

“To generate accountability for escalating touch points, define a cadence for customer outreach that increases on recent efforts, but is also achievable,” a YCharts summary proposed.

The business mentioned techniques this kind of as creating a bi-weekly blog put up, emailing a regular monthly publication or contacting substantial-web-well worth clientele at the time a quarter. The survey showed that 73{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of surveyed customers choose e mail communications from their adviser, when 45{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} indicated a choice for phone phone calls and 35{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} like textual content messages.

Following Gen Advising 

Fidelity’s report uncovered that 63{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of traders born in between 1981 and 2012 feel working with an adviser is key to accomplishing financial results, and 60{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} truly feel a heightened have to have to have interaction a economic adviser this yr because of to financial uncertainty. The agency also noted that 57{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of present shopper assets envisioned to pass to the following technology by 2045, which “presents a considerable growth chance for fiscal advisors—and possible looming business enterprise vulnerability for all those who do not prioritize participating with this team.”

The firm’s new toolkit for advisers contains a young trader readiness assessment to see if a organization is utilizing greatest techniques. The assessment contains: building a sustainable technique giving new systems and a digital presence becoming represented by various expertise and society working with modern-day merchandise choices and evolving consumer engagement versions. It also includes entry to a community of assistance providers supplying financial literacy tools and programs.

Hartford’s Sullivan suggests the underpinning of all adviser conversation must be authenticity, not just pitching the “latest and greatest” approaches.

I feel that customers can get a sense when it is not properly-intentioned,” he suggests. “Instead of advisers hoping to be all items to all folks, they should really give assumed to the folks that they would like to commit time with. … That’s where you can find a legitimate affinity for functioning with an individual.”

FINRA Fines Wedbush for Allegedly Not Supervising Customers’ Trades

FINRA Fines Wedbush for Allegedly Not Supervising Customers’ Trades

Wedbush Securities will spend $975,000 for failing to supervise trades funneled as a result of the business and executed by third-occasion broker/dealers, according to disciplinary rates from the Fiscal Sector Regulatory Authority.

Wedbush Securities, a Los Angeles-dependent b/d with about 70 department places of work and much more than 500 registered staff members, offers brokerage, prosperity administration and financial investment banking solutions, according to FINRA’s letter of acceptance, waiver and consent submitted final week.

It also has a checkered record with regulators, in accordance to the FINRA submitting. In 2014, Wedbush agreed to shell out $2.44 million to settle Securities and Exchange Commission charges that it failed to put correct hazard controls in spot for b/d shoppers (including thousands of abroad traders).

A person 12 months afterwards, the firm was fined $1.8 million by FINRA, Nasdaq and the New York Stock Trade Arca for similar lapses. The organization also paid out $1 million to NYSE Arca in early 2019 for again not getting ample threat controls in place to detect likely manipulative trades, according to FINRA.

Partly since of these actions, Wedbush stopped offering industry access products and services to clients in June 2015, according to the FINRA letter. But the company continued to enable some of its digital trading buyers access 3rd-bash platforms that routed customers’ orders to b/ds to execute the trades.

“Wedbush mistakenly believed that it was not required to assessment this buying and selling for any form of perhaps manipulative exercise considering the fact that it was no for a longer period providing industry accessibility,” the FINRA letter alleged. “Instead, the organization considered that the obligation to assessment this investing for possibly manipulative pursuits rested only with the executing broker-dealers.” 

This meant that the company wasn’t conducting supervisory opinions of many trades since it stopped giving direct market obtain in 2015. For that reason, Wedbush was in danger of missing instances of manipulative trading, which include “layering, spoofing, clean product sales, or marking the close or open up,” according to FINRA.

In a person occasion, Wedbush skipped likely layering in early 2017 from an institutional client (layering is when a trader helps make and then cancels trades they never intend to finish to effect share selling prices). The unnamed third-occasion b/d performing with Wedbush caught the probable scenarios of market manipulation that March and informed Wedbush, which subsequently closed the customer’s account, according to FINRA. 

But the regulator slammed the company for not taking actions to detect other customers likely manipulating trading, major to about 90 prospects contacting for additional than 3.4 million transactions with 13.5 billion shares that went unreviewed by Wedbush since 2015. 

The organization also failed to set devices into place to “review for likely layering and spoofing by the firm’s proprietary traders and all firm consumers,” in accordance to FINRA. The firm’s created techniques didn’t contain something requiring opinions for this sort of activity until finally June 2019, but even then, the treatments were being superior created to catch other forms of manipulative trades.

Wedbush’s regulatory skirmishes with regulators include 2018 expenses from the SEC for failing to supervise an staff working a pump-and-dump scheme, as nicely as joint FINRA/NYSE charges that Wedbush didn’t properly supervise 1 of its clearing customers. This is in addition to other fees centered on document fabrication and anti-money laundering-violations in whole, the firm’s mandatory disclosures on BrokerCheck contain 126 distinct “regulatory gatherings.” 

Wedbush did not answer to requests for comment.

In whole, about $82,143 of the $975,000 wonderful will be paid to FINRA, with the remainder heading to a number of other influenced exchanges, which include Nasdaq and the NYSE. The company also agreed to a censure whilst not admitting or denying the accusations included in the settlement.

Exclusive: Goldman Sachs to cut asset management investments that weighed on earnings

Exclusive: Goldman Sachs to cut asset management investments that weighed on earnings

NEW YORK, Jan 23 (Reuters) – Goldman Sachs Team Inc’s (GS.N) asset management arm will considerably decrease the $59 billion of different investments that weighed on the bank’s earnings, an executive told Reuters.

The Wall Road huge strategies to divest its positions more than the next number of a long time and exchange some of individuals funds on its harmony sheet with outside the house money, Julian Salisbury, main financial investment officer of asset and wealth administration at Goldman Sachs, instructed Reuters in an job interview.

“I would be expecting to see a meaningful decrease from the present levels,” Salisbury mentioned. “It can be not likely to zero because we will continue on to make investments in and along with cash, as opposed to individual promotions on the stability sheet.”

Goldman had a dismal fourth quarter, missing Wall Avenue financial gain targets by a huge margin. Like other banking companies struggling as corporation dealmaking stalls, Goldman is permitting go of additional than 3,000 employees in its major spherical of position cuts given that the 2008 economic crisis.

The bank will give even more aspects on its asset approach throughout Goldman Sachs’ trader day on Feb. 28, he mentioned. Alternative belongings can contain non-public fairness or genuine estate as opposed to common investments these kinds of as stocks and bonds.

EARNINGS VOLATILITY

Slimming down the investments on a bank’s stability sheet can lessen volatility in its earnings, said Mark Narron, senior director of North American financial institutions at credit score ranking agency Fitch Ratings. Shedding investments also cuts the quantity of so-termed hazard-weighted belongings that are made use of by regulators to establish the amount of money of money a bank ought to keep, he stated.

Goldman Sachs’ asset and wealth management posted a 39{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} decrease in net income to $13.4 billion in 2022, with its profits from fairness and personal debt investments sinking 93{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} and 63{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, respectively, in accordance to its earnings announced past 7 days.

The $59 billion of alternate investments held on the stability sheet fell from $68 billion a year previously, the benefits showed. The positions bundled $15 billion in equity investments, $19 billion in financial loans and $12 billion in debt securities, alongside other investments.

“Naturally, the environment for exiting belongings was substantially slower in the back 50 percent of the yr, which intended we were ready to understand fewer gains on the portfolio in comparison to 2021,” Salisbury reported.

If the ecosystem increases for asset income, Salisbury stated he anticipated to see “a quicker drop in the legacy stability sheet investments.”

“If we would have a few of normalized a long time, you’d see the reduction taking place,” in that time period, he said.

Private Credit rating

Shoppers are exhibiting keen fascination in private credit score offered sluggish cash markets, Salisbury mentioned.

“Personal credit score is interesting to people due to the fact the returns available are appealing,” he mentioned. “Buyers like the idea of possessing anything a minor far more defensive but high yielding in the latest economic environment.”

Goldman Sachs’ asset administration arm shut a $15.2 billion fund before this month to make junior credit card debt investments in personal fairness-backed companies.

Personal credit belongings throughout the market have a lot more than doubled to about $1 trillion because 2015, in accordance to knowledge service provider Preqin.

Buyers are also demonstrating curiosity in personal equity cash and are on the lookout to get positions in the secondary marketplace when existing investors sell their stakes, Salisbury reported.

The U.S. financial investment-grade primary bond market place kicked off 2023 with a flurry of new specials.

The marketplace rally has “far more legs” for the reason that buyers are prepared to acquire bonds with for a longer period maturities when trying to get better credit high-quality because of the uncertain financial setting, he claimed.

Goldman Sachs economists anticipate the Federal Reserve to raise interest premiums by 25 foundation details each in February, March and May well, then holding regular for the rest of the year, Salisbury explained.

Far more broadly, the “chilling effect” of final year’s fee hikes is starting to amazing economic exercise, Salisbury claimed, citing softer choosing activity and slowing progress in rents.

Reporting by Saeed Azhar Enhancing by Megan Davies, Lananh Nguyen and Lisa Shumaker

Our Expectations: The Thomson Reuters Trust Concepts.

Commentary: Financial management critical in successful city government | Chaska Opinion

Commentary: Financial management critical in successful city government | Chaska Opinion

The up coming subject matter in this dialogue of making a healthful local community lies with the financial scheduling and administration.

It will emphasis on regional authorities financing supplied which is in which we typically determine. What also is critical to recognize is that any elected governance board or council is the strategic arm of the business. They have the obligation for creating the eyesight and priorities of their neighborhood, such as the financial requirements and impacts, along with creating the community knowledge.

Bob Roepke is a previous Chaska mayor and serves on the Community Foundation for Carver County Board.

Advisor-Finder Zoe Financial Launches Zoe Wealth Platform

Advisor-Finder Zoe Financial Launches Zoe Wealth Platform

Zoe Economic, a discover-an-advisor services, is launching the Zoe Prosperity System, a new services furnishing quick account opening for purchasers working with a money advisor and featuring account funding, automated rebalancing and fee-absolutely free fractional share trading, according to the corporation.

“The new system expands the prosperity administration offerings from hiring the advisor to opening investment decision accounts and developing their prosperity even though investing with the advisors,” mentioned Andres Garcia-Amaya, the CEO and founder of Zoe Monetary.

Garcia-Amaya claimed they established themselves aside from other firms in the place by offering a “seamless, integrated expertise.”

“There are guide-gen choices, and other corporations provide a TAMP,” said Garcia-Amaya. “Other platforms have bolted-on ordeals that direct to a disjointed working experience for buyers and advisors. We make the consumer-advisor match a frictionless knowledge and be certain the customer is a person click on absent from investing with a monetary advisor. This is a sport changer for RIAs mainly because it enables them to preserve time on marketing and advertising, operational and expense procedures, ultimately opening up bandwidth to concentrate on deepening client relationships and expanding their small business.”

Zoe Money has skilled exponential development around the past number of decades.

Launched in February 2018, the firm began by building a little network of charge-only economic advisors.

As of May possibly 2021, there were extra than 2,600 unique independent advisors using the direct-gen platform, and clientele that experienced been matched with Zoe Community Advisors account for $410 billion in property under administration.

At this time, advisors making use of Zoe’s lead-gen platform manage $700 billion in AUM representing approximately 500 RIA firms, stated Garcia-Amaya.

With the new prosperity administration system, Zoe Fiscal has partnered with Apex Fintech Solutions to present custody and clearing solutions.

“Unlike existing competitors, Apex Fintech Answers presents APIs for various areas of setting up a prosperity system, e.g. electronic account opening, hard cash and securities transfers, rebalancing and fee-free and fractional investing, among the other people,” mentioned Garcia-Amaya. “With these offerings, we can deliver the client practical experience our clients deserve.”

Olivia Eisinger, who potential customers the advisory channel at Apex Fintech Alternatives, stated they ended up “thrilled to empower electronic challengers of the advisory world like Zoe who are committed to helping advisors streamline their workflows and make scale in their firms.”

“Combining Apex’s contemporary onboarding, servicing and investing capabilities, jointly we have produced a seamless experience for present day advisors and their clientele,” reported Eisinger. “We are very pleased to bring to market a dependable platform backed by a uniquely related ecosystem as we collaborate with Zoe to form the potential of advisory.”

William Trout, director of prosperity management at Javelin Tactic & Investigate, said advisor technologies is pretty common at this stage, but “with its most recent transfer, Zoe is hurrying forward.”

“Advisor matching is indeed a thing. Massive financial institutions like Lender of The usa Merrill and JPMorgan Chase give it. Huntington Countrywide Lender works by using InvestCloud’s Obtain My Advisor instrument to electricity its Advisor Link system. Now a cohort of scaled-down fintechs has emerged to hook up consumers not just to banking institutions, but to independent advisors as well. These data-pushed troubles contain suppliers like SmartAsset, Wealthramp and, of class, Zoe Economical,” said Trout. “The advisor matching course of action offered by competitors tends to be ‘black-box’ and fragmented in terms of each the advisor and end-user working experience. With Zoe Wealth System, the company is giving an all-in-just one answer that weds established-up and execution. It is barely astonishing to see Apex Fintech Answers, the custodian of selection for robo advisors and other electronic assistance providers, helping lead the cost.”

DOD Financial Management: Greater Attention and Accountability Needed over Government-Furnished Property

DOD Financial Management: Greater Attention and Accountability Needed over Government-Furnished Property

What GAO Located

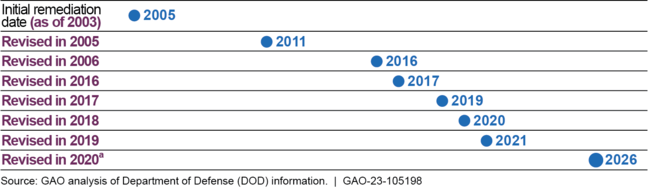
For several years, the Department of Protection (DOD) has struggled to properly account for authorities residence in the possession of contractors, known as federal government-furnished home (GFP). DOD has regularly revised its prepared dates to deal with a GFP-similar content weak point considering that auditors initial claimed it in 2001.

Department of Defense’s Revisions to Remediation Dates for Addressing the Govt-Furnished Residence (GFP) Materials Weak spot

Department of Defense's Revisions to Remediation Dates for Addressing the Government-Furnished Property (GFP) Material Weakness

DOD administration has issued multiple memorandums to remediate the very long-standing GFP-connected material weakness, including a Might 2019 memorandum that directed DOD parts to set up a baseline of GFP belongings. On the other hand, GAO uncovered that DOD did not accomplish its stated objective for the May well 2019 memorandum as a outcome of challenges with (1) an inefficient and incomplete preliminary memorandum distribution course of action, (2) confusion between division officials more than memorandum terminology, (3) components’ logistical struggles to determine and provide requested info, and (4) a absence of successful management review of the components’ development. Moreover, GAO determined problems with the Property Functional Council (Council), which DOD set up in part to oversee initiatives to tackle the substance weak spot. For case in point, the Council did not routinely focus on GFP or the Could 2019 memorandum, and did not regularly meet or incorporate all important participants when it did. Without having documented processes and methods for GFP-connected memorandum advice and the Council’s functions, DOD raises the risk that it will keep on to experience problems with its initiatives to remediate the GFP-related materials weak point.

Whilst DOD has taken measures to tackle the GFP-similar materials weak point, GAO found that division-huge attempts have not been in depth and adequately comprehensive. Creating a comprehensive section-broad strategy, individual from DOD’s overarching fiscal management technique, would guide the division in pinpointing root triggers of deficiencies with common remedies across the departments, and plainly defining specific treatments for reaching responsibilities and assembly concentrate on dates. Without having such a tactic, DOD is at an enhanced hazard that its endeavours to remediate the GFP content weak point will continue on to be inadequate and that it will proceed to skip or force again target remediation dates.

Why GAO Did This Examine

DOD’s lack of accountability around govt property in the possession of contractors has been documented by auditors for a long time. This prolonged-standing problem impacts the accounting and reporting of GFP and is 1 of the motives DOD is unable to generate auditable economic statements. DOD believed the value of its GFP at in excess of $220 billion nevertheless, that sum is very likely drastically understated.

This report, produced in connection with fulfilling GAO’s mandate to audit the U.S. government’s consolidated money statements, examines the (1) difficulties DOD has encountered in division-large attempts to tackle weaknesses associated to its accounting for GFP and (2) extent to which DOD has formulated a office-broad system to handle the GFP-relevant content weak point.

GAO reviewed related audit reports, memorandums issued by DOD administration, DOD system paperwork, and Council assembly documents interviewed officers and analyzed armed service section reports.