How to Become a CFA

How to Become a CFA

The chartered financial analyst, or CFA, designation is often viewed as the gold standard in investment management. For financial industry, Home Garden USA.

The chartered financial analyst, or CFA, designation is often viewed as the gold standard in investment management.

For financial industry professionals whose aspirations lie in analysis, you can’t do much better than the chartered financial analyst marks, which demonstrate knowledge of investments, portfolio management and other aspects of wealth planning. “It is slowly becoming the ‘college degree’ of investment management,” says Bryan Lee, a CFA who is the chief investment officer at Blue Zone Wealth Advisors, “meaning, for some companies, it is a must-have to even attempt to work there.”

Here’s what to know about earning the CFA as a financial certification — and what it’s like to work as a CFA.

[SUBSCRIBE: Get the weekly U.S. News newsletter for financial advisors. ]

What Is a Chartered Financial Analyst?

A chartered financial analyst is a financial professional who’s earned professional marks denoting expertise in investment management. Given by the CFA Institute, the chartered financial analyst program teaches the fundamentals of investment management, from asset valuation and analysis to portfolio management and wealth planning.

Investment management is an evolving ecosystem affected by valuation, politics, economics, accounting, ethics and behavioral science, says Taylor Royal, a CFA and partner and financial representative with Royal Wealth Partners, a Northwestern Mutual private client group. “The CFA charter is the differentiator in finance and dives deep into each of these topics.”

[READ: MBA or CFA: Which Is Better for Financial Advisors?]

How to Become a CFA

To become a CFA, you’ll need to pass a three-part sequential CFA exam that includes multiple-choice and essay questions. It is considered one of the hardest professional exams in the industry. The average pass rate on each part ranges from 42{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to 54{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}. From 1963 to 2021, only 45{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of applicants passed all three exam parts. Candidates report studying for more than 320 hours on average in preparation for each exam.

Depending on when you register, the CFA program can cost between $700 and $1,000 — or more if you need to reschedule your exam date.

You must also complete at least 4,000 hours of relevant work experience over a minimum of 36 months. To be relevant, that work must be “directly related to the investment decision-making process producing a work product that informs or adds value to that process,” according to the CFA website. You can complete this work experience before, during or after passing the exam. But applicants won’t be able to use the CFA designation until they’ve met all these requirements, which also include submitting two to three professional references who can comment on their work experience and professional character.

“The CFA program was a major commitment of time, money and brainpower,” Royal says. “I began studying for each level at least six months in advance of each test and spent countless nights and weekends preparing for each exam.”

Be prepared to turn down a lot of social events while you’re preparing for the CFA exam. “I always tell people there is only one way to approach the program, and that is to go all in,” Lee says. “I have seen past co-workers take multiple years to pass different levels, and it can really be draining.”

He chose to tackle the program as quickly as possible, so while he felt like he was making a lot of sacrifices at the time, he was able to complete the program efficiently by passing each exam on his first attempt. “Looking back, I think that was key to keep my motivation high and remain disciplined and focused,” he says.

He also recommends sticking to a study schedule and taking as many practice exams as possible. But don’t forget to get enough sleep and exercise, so you don’t get burned out. “Understand why you are going through the process and make sure you use that as motivation to get through the difficult and frustrating weekends that you are studying all day while your friends are out having fun,” he says.

To help him get through the exam, Jim Grefenstette, a CFA with DJM Financial, a Northwestern Mutual private client group, joined a study group. The group members met regularly to review topics and hold each other accountable. Grefenstette says having that study group was critical to his progress.

“For any aspiring CFAs, my advice is to come at the work with passion and know that the designation can open doors to a wide variety of successful and fun careers in finance,” he says.

[READ: What to Know About Working as a Freelance Financial Planner.]

What Do CFAs Do for Work?

CFAs hold a variety of careers across all sectors of the financial industry, from asset management and private wealth management to insurance and commercial or investment banking.

You’ll also find CFAs in emerging sectors like financial technology. CFAs typically work as research analysts or investment consultants or strategists. They may work in portfolio management or risk analysis and management. CFA charterholder portfolio managers reported a base salary of $126,000 in 2019 and a total compensation of $177,000, according to the CFA Institute.

As a CFA, Royal advises sophisticated professionals who have earned their wealth in technology or as business entrepreneurs and managers. He says the CFA credential has helped him demonstrate his ability to meet his clients’ unique financial needs while showing his commitment to higher ethical standards.

Grefenstette chose to get his CFA while working as an analyst for an equity mutual fund. “I wanted to both improve my analytical skills, so I could do my job better, and be able to communicate my qualifications to my fund shareholders, so that they could have more confidence in our fund’s investment process,” he says.

He says he never could have progressed in the field without the skills he developed and honed through the CFA program. “An analyst, to a large extent, must make decisions or judgments based on incomplete information most of the time, as the variables in finance are often as qualitative as they are quantitative,” he says. “I think that aspect makes my job fun every day.”

The CFA charter can also be beneficial to professionals who aspire to work in a more analytical role. It allows them to be heard in the room and demonstrate that they have the required background and drive to advance within the company, Lee says.

“Having a CFA opens the door to more opportunities and allows for growth in your career,” he says. “If your company doesn’t value the designation, it can help you to find somewhere else that will — and will compensate you for your hard work completing the program.”

More from U.S. News

6 Pros and Cons of Choosing a Fee-Only Financial Advisor

14 Things to Know Before Becoming a Financial Advisor

8 Ways Financial Advisors Connect With Millennial Investors

How to Become a CFA originally appeared on usnews.com

Visit : https://homegardenusa.com/

Overcoming the Three Biggest Threats Facing Wealth Management

Overcoming the Three Biggest Threats Facing Wealth Management

By Christine Mar Ciriani, CEO, Non-public Banking & Wealth, InvestCloud


Unprecedented inventory marketplace gains have both of those produced alternatives for wealth supervisors to demonstrate their benefit although also shining a mild on the road blocks wealth managers need to have to conquer. Increasing demand for hybrid suggestions, purpose-dependent preparing and shell out-for-effectiveness charge constructions have emerged since of this unique problem.

Retaining a close romance with buyers is paramount to not only offering the most effective service, but also recognizing which worries they are struggling with, so wealth supervisors know how to assist clear up them. The 3 most important troubles that hold leaders of prosperity management corporations awake at night time are in reality the exact same a few topics that are also producing a wave of consolidation in the sector.

We are talking about commoditisation, cost compression and competitiveness.

Though there is no established option to solving all these difficulties, technological innovation has tremendous probable in mitigating their effects.

Commoditisation and Competitors

Prosperity professionals have been known for giving exceptional shopper provider, customized investment advice and tips. But components of the value chain are remaining witnessed by purchasers as a commodity. With self-directed platforms like Robinhood and e-Toro shifting to zero fee on the net trading and elevated variety of one-spouse and children workplaces, clients have escalating possibilities for increasing and protecting their wealth.

As marketplaces go on to continue to be solid, shoppers will change to much more self-directed investing and glance for electronic instruments to manage their investments. An escalating proportion of significant-net worthy of purchasers are actively making use of a WealthTech business to handle their wealth. Wealth administrators who are not able to offer acceptable electronic platforms might drop to new, digital players. In parallel, the potential to deliver incremental advisory help at scale when lessening guide engagement will be a differentiator.

A persuasive and empathetic customer portal experience is critical in wealth management as the electronic-to start with competitors is presently employing it. Neo and challenger banks with a electronic-first philosophy are projected to get to a $471 billion market size by 2027, with digital prosperity administrators anticipated to capture $16 trillion by 2025.

How can prosperity mangers consider benefit of this progress and guarantee they retain these belongings beneath administration? How can they continue to offer hyper-personalised assistance at scale and profitably engage shoppers across segments?

Harnessing electronic through details analytics to study far more about clientele is one stage to tackling this. And engineering with state-of-the-art analytics, equipment mastering and conclusion idea has opened a new frontier to getting equipped to change shopper engagement and investment general performance.  

Cost Compression

The rise of passive funds and robo-adviser applications are driving down expenses that a wealth supervisor has traditionally been capable to charge.

A rise of regulatory alterations and know-how adoption has intended an greater need to have for wealth professionals to understand how they can offer their shoppers additional value and show differentiation from their competitors.

Engineering-pushed hyper-personalisation will be important in reaching loyalty and progress in the prosperity management landscape through 2021 and past. Specially in a globe the place a lot less than 50 {21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of superior-net-well worth persons – no issue their age – say their prosperity administration company understands their distinctive demands.

Electronic equipment can aid in capturing information about their shoppers that goes significantly further than finances. From wellbeing and family to physical property and lifetime objectives. This data is essential in demonstrating that relationship supervisors fully grasp their shoppers individual and evolving requirements. Furthermore, it has the prospective to create increased income as clientele have shown they will spend for benefit.

The most current developments in technological know-how – together with machine studying, artificial intelligence equipment, and the application of behavioural science – automate substantial facets of suggestions provision for romance managers, permitting advisers to quickly and intuitively foster deep client associations, and aim on adding price by providing personalised and related investment decision recommendations to their consumers.

Technological innovation also allows increase what wealth supervisors have generally been known for – client servicing. Exploration, documentation and confirmations can be shared digitally and advisers can service a number of cilents by way of a shared portal. Ultimately, this conjures up self-assurance for the client wich of program translates into loyalty insit’s more difficult to transform fiscal establishment when the adviser is integral to extra facets of a client’s monetary lifetime.

Advanced Analytics, Gamification and Final decision Idea

In prosperity administration, data has generally been used to push choices. But now there is a substantially wider breadth of facts to leverage, ranging from a customer’s electronic footprint to alternative facts resources coming from structured and unstructured information. This makes it possible for banking institutions to use AI and Equipment Mastering to offer value-added assistance and suggestions.

This aids wealth supervisors meet the soaring desire for customized investing, enhancing the capability for advisors to concentrate their time on schooling and guidance instead than on making financial investment suggestions, particularly when consumers are on the lookout to extend investments into sustainability, crypto-belongings and direct investments. As an illustration, wealth supervisors can design and style sustainable investing techniques leveraging information to aid provide precise details on companies’ ESG impression and investments.

When improving client engagement, gaming and choice concept can also assistance inspire purchasers to interact, unlock engagement and present more details which can present further personalised servicing. Embedding these procedures in setting up out enhanced shopper electronic portals can make sure clientele continue to be linked and engaged.

A Successful Components

The way buyers interact with and control their prosperity has experienced to alter in purchase to press again against the threats of rate compression, commoditisation, and competition. The driving power is greater digitisation – some thing continue to below-made use of by advisers. 

Wealth administration continues to be an exclusive, hugely-personalised assistance. But it is not possible to capture new options at the similar time as servicing existing shoppers devoid of working with engineering. Digital is the essential to supporting broader shopper collaboration, servicing, and furnishing really personalised investment decision assistance.

It’s undeniable that the previous 12 months and a 50 percent has compelled companies to adapt to technology—both spurring present tech on, and becoming the catalyst for new tech to emerge and fix problems. Prosperity professionals who have deemed reworking their digital journey to delight their shopper are the ones who are long term-proofing their business enterprise. The moment that is reached, the concentration is then on furnishing price beyond investment effectiveness in conditions of service encounter and complete customer wellness.

Combining a genuinely intuitive, personalised service, with a intelligent electronic strategy designed upon gamification and decision principle is the answer to a lot of of the big challenges dealing with the sector. Prosperity supervisors that have been ready to adapt and apply technological know-how to their existing ways of doing work will occur out on best.


Financial Advisor IQ – Content Page

Financial Advisor IQ – Content Page

Advisors may well want to drop asset administration from their work responsibilities and as an alternative focus on what they do very best: advising clients.

At the very least which is according to some people today in the marketplace.

Target Monetary Companions’ founder, chief executive officer and chairman, Rudy Adolf, is unequivocal about what he thinks of advisors who actively control their clients’ portfolios.

“If corona has taught us everything, it’s the worth of suggestions and the depth of assistance. We are not asset professionals. We are prosperity structurers,” Adolf explained last week at Financial institution of The usa Securities’ 2021 Banking and Financials Conference, Get Auto Tips.

“Yes, we also take care of nicely about $300 billion. But at the main this is a prosperity structuring enterprise and, in occasions of crisis, this is a service that is critical for the clients that we are serving,” he added.

Adolf’s comments are regular with the sights of business analysts from Morningstar and Cerulli Associates.

Asset management is not a apply the place advisors can generally provide a whole lot of price, “especially if they are attempting to do active allocation or select actively managed money or personal stocks,” according to Amy Arnott, a portfolio strategist at Morningstar.

“For the vast majority of money advisors, it would make sense to outsource financial commitment administration. That frees up a lot more of their time and power to spend with customers and to genuinely devote much more time accomplishing economic setting up, which is where by they can increase important benefit,” she informed FA-IQ.

Scott Smith, director of assistance relationships at Cerulli, agrees. Advisory corporations “fare better by concentrating their advisors’ initiatives on client-experiencing things to do relatively than hands-on day-to-day portfolio management,” he told FA-IQ.

“Advisors do an great job of determining clients’ certain choices, concerns and objectives but really should additional regularly use these to match [the clients] to third-get together managed model portfolios than actively taking care of client portfolios them selves,” he explained.

There are, immediately after all, outsourcing choices for advisors, which include things like turnkey asset management systems and product portfolios, Arnott mentioned. But advisors ought to still make certain that they have an understanding of how the outsourced portfolios are currently being created, no matter of which selection they pick out, he additional.

There are occasions, nonetheless, when advisors could double up as asset professionals, in accordance to Morningstar’s Arnott. For case in point, this would operate for clients with “very advanced portfolios” that may well have a concentrated place in organization stock or a ton of shares with unrealized gains, she said.

“Those are cases the place money advisors can insert a lot more value by helping with tax management and tax planning or trying to diversify concentrated positions over a interval of several years and serving to the client come up with a technique to do that,” she said.

Tactical Allocation

Cerulli’s Smith cautions advisors from tactical allocation specially, declaring that they won’t be able to outperform asset managers provided the other needs of becoming an advisor.

“Having advisors split their time among attempting to operate portfolios, assemble property, produce relationships and attempting to compete against tens of countless numbers of financial commitment specialists doing this total-time, it’s just not a successful proposition long time period for the large greater part of advisors,” he reported.

Though an advisor “can make a guess and win” in the limited phrase with tactical allocation, the trouble is that they “have to guess when to get in and when to get out constantly,” according to Smith.

“Unless you have some sort of outside edge both as a result of your training, which is not likely, or some variety of inside information and facts, you’re not likely to gain extended term against professional gurus executing this on a entire-time basis with the likes of the most significant sset supervisors in the globe backing them,” he said.

Do you have a information idea you’d like to share with FA-IQ? E-mail us at editorial@financialadvisoriq.com.

Visit : https://ahjedlvjmxsd.com/

“What Is Your Company’s Maintenance Capex”?

“What Is Your Company’s Maintenance Capex”?

How considerably of the company’s financial investment is recovered through revenue? What expenditure would it take to market the quantity of solution we pushed out this year? How a lot of our financial commitment will direct to advancement through acquisition of new prospects?

A person of the to start with factors enterprise professors instruct in an introductory finance class is how to prepare the funds price range. The teacher dutifully asks learners to venture how a capital outlay – this sort of as a device in a factory – could produce long run money inflows and likely revenues. Following a extended discussion about the correct price of a machine to subtract from its opportunity funds return, students arrive at a net present price (NPV) of that investment decision. When students program how a lot to commit in their opportunity business enterprise, they look at the NPV with the price tag for paying for the equipment. The decision rule is that if the NPV of the exceeds the first buy cost, the investment decision is a go.

But even nevertheless this elementary thought is a main tenet of financial commitment, it is routinely misused, distorted or basically ignored, as illustrated under.

How a great deal of the PP&E and intangible expenditure is recovered through profits?

This is a query that rarely will get requested. But the question is simply just a logical extension of the NPV analysis to justify an original financial investment. Section of the dilemma is a rising obsession with marginal pricing, specifically because the advent of the World-wide-web. The prevailing concept is that the product rate merely requires to go over the variable prices, due to the fact elevated volume will sooner or later allow for a organization to enjoy economies of scale from network outcomes and spend for the fixed charges incurred to set up the community outcomes. As I have penned prior to, investors can hardly ever check this narrative since fiscal statements do not break down a firm’s cost composition into fastened and variable charges.  Even additional worrying, how quite a few CFOs talk to/know the part of the preset fees employed to create productive ability ended up recovered from the sale of every marginal item?

Non-GAAP earnings that include back productive capability fees

Numerous providers use non-GAAP metrics that add again successful potential expenses this sort of as depreciation and restructuring. But there’s a challenge: these non-GAAP metrics in essence assume that capacity expenditures are zero and the business can have on in its merry means devoid of producing investments. Whichever happened to the idea of recovering the hard cash outlays by way of long term revenues?

Charging servicing capex, not depreciation, to the profits statement

The right issue for an trader to request is this: “What is the annual price of productive ability that we need to charge versus revenues these types of that capability costs sustains the revenue generated by the organization?” Some call this quantity “maintenance capex.” Warren Buffett, in his 1986 letter to shareholders, defines routine maintenance capex (my label, not his) as “the normal yearly amount of money of capitalized expenditures for plant and equipment, etcetera. that the business enterprise requires to thoroughly retain its long-phrase aggressive place and its unit quantity.” The remaining capex, labeled “growth capex” should really preferably be capitalized as an asset on the harmony sheet.

I speculate no matter whether CFOs undervalue the authentic expense of successful ability, primarily upkeep capex which, in convert, indicates that reported margins are not sustainable. As an analyst, what can you do to estimate routine maintenance capex? Study by our graduate scholar, Venkat Peddireddy, suggests that the maintenance capex of a enterprise, outlined purely as PP&E (home, plant and devices) outlays, not intangibles, is approximately 20 {21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} increased than the reported depreciation variety. Of system, that amount varies by field. But, if you want a fast and filthy adjustment, enhance described depreciation variety by 10-20 p.c and compute the subsequent tax-modified influence on web profits.

Audit companions I have chatted with are skeptical of the Peddireddy analyze. They believe that that various absolutely depreciated property are even now remaining used by corporations. They issue out that numerous PP&E merchandise (not automatically the evident applicant, authentic estate) are basically composed up in order cost allocations when the acquirer accounts for the thing to consider paid out to the focus on organization in an M&A transaction. My worry is that the audit companions overlook the pressures imposed by technological obsolescence on firms. If your competitor has a shiny new item, you have to get that item or hazard losing market share in the product or service marketplace. Also, targets that produce up these types of belongings are self-chosen in that they are not your “normal” firm that the Peddireddy analyze considers. In truth, the target business, whose invest in price allocations are remaining reviewed, have been acquired likely to handle technological obsolescence feared by the acquirer. Moreover, is the create up of absolutely depreciated property at the focus on corporation a way to justify possible overpayment for the target?

Just one way to resolve this puzzle is for the CFO to report their routine maintenance capex amount in their MD&A or in their financial statements.

How numerous CEOs explicitly imagine about servicing capex?

How lots of organizations really report their upkeep capex selection? Very couple. A person could chalk that up to secrecy and an effort and hard work to hide proprietary facts from opposition. I marvel how a lot of CFOs even know their servicing capex range. Inquiring that dilemma, in particular for intangibles this kind of as R&D and selected factors of SG&A, is even trickier.  A nicely-regarded analyst shared the adhering to story with me: “I was with a CEO yesterday and requested him if he would be equipped, if only crudely, to allocate his SG&A among servicing and discretionary paying. He mentioned he’d have to feel about it a whole lot!”

How substantially should really Netflix commit on material creation to just retain its marketplace share in the U.S.? How much need to Amazon invest on technologies to preserve growing? Could the supply chain fiasco we face now have been prevented if extra of us in the C-suite experienced requested, “What expenditure would it consider to sell the quantity of item we pushed out this calendar year?” Or even more simple, “What is our servicing capex number?” These are hard but essential inquiries that will need to be questioned more typically in meeting phone calls and board rooms.

The SEC can take care of the valuable daily life and depreciation disclosures

The crux of the difficulty is the extremely uninformative disclosure that firms offer on the helpful lives of their house plant and products. I have reproduced the practical life footnote from Residence Depot’s 10-K for the fiscal calendar year finished 2020:

Notice the ranges of useful life for properties and leasehold advancements (5-45 several years) and for home furniture (2-20 several years). How is an investor intended to know the genuine handy lifestyle of these belongings if the ranges are this broad? And, to make issues worse, corporations report just one mixture depreciation number. Depreciation is hardly ever, if ever, broken out by asset class for most organizations.

At some point when organizations choose impairments or restructuring rates partly as a outcome of overoptimistic handy lives and reduce depreciation numbers assumed earlier, they persuade investors to only incorporate back again these “non-recurring” merchandise again to earnings. Is not an asset impairment or a restructuring cost related to belongings basically “catch-up” depreciation?

The difficulty with intangibles

We are fortunate to get at minimum some granular disclosure for tangible belongings. Disclosure is far more opaque for internally produced intangible assets. It is significant to put some value of intangibles on the balance sheet for the easy rationale that a zero selection on the balance sheet is ipso facto immaterial. Auditors pay less awareness to a zero-asset amount. So do regulators. If the watch puppies are not concentrated on a number, why would supervisors have incentives to disclose much more info on intangibles. I have pointed out how Amazon spends $42 billion on technology and written content but devotes a grand full of 300 phrases in its 10-K conveying what that money is put in on.

Summary

In sum, when you take into account investments for effective capability, both of those tangible and intangible, for corporations make confident you know the answers to three thoughts: (i) what is the legitimate handy daily life of these ability investments? (ii) what is routine maintenance capex, each for intangible and tangible belongings? And (iii) what is the advancement capex amount?

Suggestion for the SEC: you should make companies disclose some thing shut to the legitimate financial existence of an asset, equally intangible and tangible.

Visit : https://marylandheightsresidents.com/

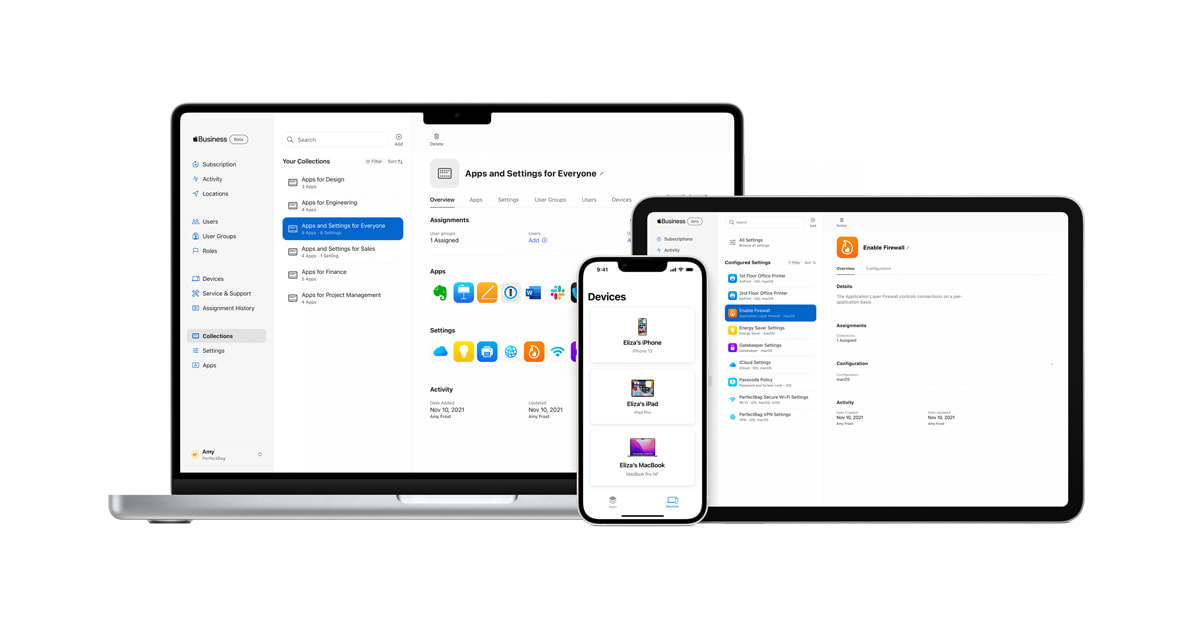
Apple introduces Apple Business Essentials

Apple introduces Apple Business Essentials

Oran Hall | How to improve poor personal financial management | Business

Oran Hall | How to improve poor personal financial management | Business

Problem: I have an difficulty of inadequate money administration, and I am trying to get some assistance if that is probable. I am searching forward to your reaction.

– Shawn

Money ADVISER: You have taken two really crucial measures in the procedure of setting up financial steadiness in your lifestyle: acknowledging that there is an problem of inadequate fiscal management and searching for tips on how to correct the dilemma.

I am not certain what brought you to the place of recognising the difficulty as there are many purple flags you could have noticed. I remember being questioned some time back by an employer to support some employees to strengthen their economic administration.

Management arrived to the summary that the workforce had been not managing their funds well due to the fact they had been inquiring often for income improvements, shelling out a sizeable portion of their earnings by income deduction to assistance loans or the two.

There are numerous other signs that show that you have a fiscal-administration dilemma. In this article are some illustrations:

• You are using an growing total of your money to repay personal debt

• You are depending on overdraft services to pay back recurring bills

• You are utilizing hard cash developments on your credit score card to pay back other charges

• You are likely to make only the minimum amount payments on your credit rating card

• You are borrowing to shell out fundamental expenses – utility costs, for instance

• You are shelling out payments late or not at all

• You are borrowing from Peter to fork out Paul

• You have regular dollars flow difficulties

• The personal debt collectors are contacting you

• Your surplus cash are not currently being applied efficiently to generate and

• You are taking too substantially possibility with your cash.

Some may perhaps argue that personalized economical problems are because of to individuals not earning enough – even that they are underpaid. The truth of the matter, nevertheless, is that there has to be a harmony concerning money and expenditure irrespective of the circumstance. If there is a deficit, in particular if it retains recurring, there is a dollars-management challenge.

If there is this sort of a difficulty, priority issues like saving, investing, and the schooling of the small children may possibly be neglected. The constant worrying that this scenario often leads to could lead to overall health issues, bad overall performance at do the job, poor inter-particular relationships and severe household pressure, possibly even the split-up of people.

I can only be normal in my response to you, not figuring out the exact nature of your problem and what has brought on it, but hope that the options you seek out will emerge from my reaction.

The traditional reaction is to say make a price range – a realistic one particular that aligns shelling out with present-day earnings. This is important, for a lot of make a finances, but it does not replicate meaningfully how they receive and commit dollars.

Others make a budget but do not adhere to it. It is just a meaningless work out due to the fact they do not keep track of their shelling out, they do not create their priorities, they invest in impulsively, and they borrow over and above their capacity to pay out, for illustration.

A spending budget is a expending system that need to demonstrate how revenue is attained and used, having into account expenses that are periodic, not just common, and it can make it less difficult to workout regulate.

The finances need to stability from the starting, that is, when it is designed. Or else, it is a squander of time. Hold it in line by monitoring your spending, and be individual. Steer clear of rushing to acquire much too a lot way too quickly. What you can afford to pay for is what you can afford to pay for.

In some cases there is the argument that revenue complications occur thanks to emergencies. Each and every effort must be manufactured to build up a fund for emergencies, and this can be hard for some offered the degree of their cash flow.

If you are in personal debt, achieve out to your lenders and see if they are eager to access an lodging with you about how you can honour your debt. Investigate the likelihood of debt consolidation, which might allow for you to have just one personal debt above a longer time.

Place away your credit rating card if you have just one and it is contributing to your dilemma. As credit card credit card debt is extremely highly-priced, make it your precedence to do away with it. If you have to make severe adjustments to how you live, so be it.

If you have an asset, such as a vehicle, which you can’t afford, promote it. In actuality, it could make feeling to sell belongings to lower personal debt if need to have be.

Very good monetary administration involves that you use your money resources sensibly. So, set your money in risk-free establishments, use your surplus cash to generate, commit properly, diversify, get assets that are of great quality and keep them well.

Your initially workout is this: document your money, all your fees, your money owed and commitments. Set up your priorities and develop a prepared prepare to repair service your economical problem step-by-move, and adhere to it slavishly.

All the very best.

– Oran A. Corridor, writer of ‘Understanding Investments’ and principal creator of ‘The Handbook of Particular Monetary Planning’, delivers own economical organizing assistance and counsel.finviser.jm@gmail.com