Despite the Fed’s big rate hike, most banks won’t pay much in interest

Despite the Fed’s big rate hike, most banks won’t pay much in interest

Jerome Powell, Federal Reserver Governor.

Katie Kramer | CNBC

The Federal Reserve just lifted its benchmark interest fee by fifty percent a percentage issue, its biggest these transfer in a lot more than two a long time, as it seeks to tame inflation.

The central bank’s actions indicate that, in an period of sharply growing charges for anything from foods to fuel, the price of cash alone is increasing. Borrowers — individuals searching for home loans or carrying credit rating card debt — will shortly be paying out bigger prices on people financial loans.

But on the other aspect of the equation, depositors who keep their personal savings at financial institutions are not likely to experience the added benefits whenever shortly. That’s due to the fact the steps taken to avert financial disaster in 2020 left the U.S. banking sector awash in deposits, and most loan providers have tiny motive to attract extra, in accordance to analysts.

“The greatest banks in distinct are sitting down on a mountain of deposits. The last thing in the environment they’re likely to do is increase what they’re shelling out on these deposits,” said Greg McBride, chief money analyst at Bankrate.com. “The significant dominant banking franchises that have branches and ATMs from coastline to coastline, they’re not heading to be pressured to boost their rates.”

Again in 2020, the U.S. unleashed hundreds of billions of pounds in stimulus to little organizations and families, propped up markets with bond-purchasing programs and took costs to in the vicinity of zero. A great deal of that dollars identified its way to banking institutions, which soaked up around $5 trillion in new deposits in the past two several years, in accordance to Federal Deposit Insurance Corporation details.

At the exact time, the industry’s lending did not preserve rate, meaning banking institutions experienced much less areas to deploy the hard cash. Regardless of paying out out paltry interest, the industry’s lending margins were squeezed, hitting a document small past year. The typical nationwide determine compensated for discounts has hovered at all over .06{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, according to Bankrate.com. At JPMorgan Chase, the largest U.S. lender by assets, most retail accounts paid out a miniscule .01{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} once-a-year proportion yield as of April 29.

Lagging hikes

In former charge-mountaineering cycles, banking institutions were normally slow to increase costs paid to depositors, at least at initially, to permit them time to to start with lend out cash at bigger fees. That dynamic is not information to any person who tracks the marketplace: In reality, it really is the greatest variable in the expense case for banking companies, which have a tendency to reward from fatter lending margins as the Federal Funds price rises.

But there is discussion amongst analysts about no matter whether exceptional elements of the current instant will pressure financial institutions to be more responsive to growing charges. The end result will have implications for hundreds of thousands of American savers.

The industry’s deposit beta, a expression that actions how responsive a bank is to variations in the prevailing fee, is very likely to be small “for the initially several Fed rate hikes” mainly because of “excess liquidity” in the fiscal program, JPMorgan banking analyst Vivek Juneja stated in a May well 4 notice. (The bigger a bank’s deposit beta, the far more sharply it’s boosting premiums.)

But the steep level of hikes anticipated this cycle, higher opposition from fintech companies and broader price consciousness will final result in bigger deposit betas than the former tightening cycle, Morgan Stanley analyst Betsy Graseck said in a March 14 notice. That cycle lasted about a few several years as a result of 2018.

“Buyers possible will be much more conscious of rate hikes provided faster pace and fintech’s emphasis on costs as a way to obtain prospects,” Graseck wrote. “This could force incumbent banks to increase their deposit premiums far more swiftly.”

In addition, the Customer Financial Defense Bureau has stated that it will be viewing how the sector reacts to growing fees all through this cycle, raising the pressure on banks.

`Move your money’

A further unidentified is the effect that the Fed’s so-referred to as Quantitative Tightening will have on banking companies. That’s the reverse of the central bank’s bond acquiring packages on Wednesday the Fed affirmed its steering that it will cut down bond holdings by as a lot as $95 billion a thirty day period.

That could sluggish deposit expansion much more than financial institutions assume, escalating the odds that they will be compelled to elevate charges this 12 months, Graseck said.

While huge loan companies like JPMorgan, Financial institution of America and Wells Fargo usually are not very likely to significantly hike their payouts at any time before long, online banking institutions and fintech corporations, neighborhood loan providers and credit history unions will be extra responsive, boosting premiums this 7 days, according to McBride. Representatives for the 3 banks failed to promptly comment.

Just as the banks perspective the costs they pay savers purely as a organization conclusion, savers should do the same, he stated.

“Place your money where you are likely to get a much better return, it truly is the only totally free lunch in finance,” McBride mentioned. “Transferring your income to one more federally insured monetary institution gives you additional yield with out acquiring to consider on any extra risk.”

Wealth Management Divisions To Big Banks: ‘You’re Welcome’

Wealth Management Divisions To Big Banks: ‘You’re Welcome’

Wealth administration divisions ended up vivid spots in an usually tough very first quarter for Wall Street’s most significant banks. The models generally outperformed though the money establishments as a entire typically did not.

The golden age of economical information, fueled by expenses tied to growing property, may possibly not last way too a great deal for a longer time, having said that. The Federal Reserve has strategies to elevate fascination premiums and to give up purchasing property finance loan-backed and Treasury bonds, and that could spell the close of what analyst Dick Bove phone calls “nirvana” for the units.

“You’ve experienced the ideal of all achievable worlds for the wealth management firms around the final handful of a long time, but I don’t feel it’s likely to continue on,” mentioned Bove, a senior analysis analyst at New York-based broker-supplier Odeon Cash Group. “The sport is likely to alter and thus I would count on more than the upcoming several quarters and many years you’re heading to see more durable environments and reduce returns for this business enterprise.”

Wall Avenue struggled in the first quarter of the year, with the S&P 500 down 4.95{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} in that time, a drop that has nonetheless to ease. Across the board, wealth administration models did superior than the banks’ other divisions.

At the major bank in the U.S., JPMorgan Chase, net income was $31.6 billion, down 5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} year in excess of year. In the firm’s wealth management division, net income was up 6{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} to $4.3 billion.

CEO Jamie Dimon cited the war in Ukraine among the brings about for the disappointing efficiency. “Our emphasis this quarter remained on helping our shoppers navigate challenging marketplaces and unpredictable situations, which provided doing the job with governments to apply economic sanctions of unprecedented complexity,” he claimed.

Morgan Stanley also noticed a fall in net income, down 5.73{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} 12 months more than 12 months with wealth management down fewer than 50 {21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} a proportion place. CEO James Gorman identified as the effects “strong … in the facial area of marketplace volatility and financial uncertainty,” including that wealth administration “proved resilient.”

Web income at San Francisco-based mostly Wells Fargo was down around 5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, but prosperity and financial commitment management was up 6{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} calendar year above yr.

Citigroup net revenues have been down 2.5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} yr around calendar year while the firm’s private banking and wealth management performed much better with revenues down a extra reasonable 1.5{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}.

Lender of The us essentially saw income advancement of 1.8{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} in the to start with quarter as in comparison with the exact period previous yr. Merrill Lynch’s wealth administration led the cost with 10.2{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} income advancement yr about 12 months for a record profits of $5.5 billion.

At Goldman Sachs, consumer and prosperity management net revenues had been $1.62 billion, 19{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} larger than the to start with quarter of 2021 and a shiny spot compared with an in general internet earnings fall of 27{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} yr about yr.

“You can see from our earnings, the progress of the prosperity organization 12 months in excess of calendar year,” Goldman CEO David Solomon instructed investors on the firm’s earnings get in touch with. “We proceed to be concentrated on that chance. And I’d just highlight that which is a process that usually takes time. … We see it as a quite huge option. I assume we have an aspirational model in the prosperity space.”

The toughness of prosperity management at these monetary establishments is not a product or service of dumb luck. Wall Road has invested closely in it, starting up with Lender of America’s buy of Merrill Lynch 14 many years back during the top of the fiscal crisis. Considering the fact that then, Morgan Stanley purchased E-Trade and Eaton Vance and Goldman Sachs obtained United Capital, which is now Goldman Sachs Particular Financial Administration.

HDFC Bank’s $40 billion deal may face regulatory hurdles over insurance, analysts say

HDFC Bank’s $40 billion deal may face regulatory hurdles over insurance, analysts say

Folks wait around to enter HDFC bank in Kolkata, India November 11, 2016. REUTERS/Rupak De Chowdhuri

Sign-up now for No cost endless accessibility to Reuters.com

MUMBAI, April 5 (Reuters) – India’s most significant personal loan company HDFC Bank’s (HDBK.NS) $40 billion acquisition of its largest shareholder could experience regulatory hurdles owing to the stake it would give the financial institution in the insurance plan sector, analysts stated.

Sources explained to Reuters very last yr that the Reserve Lender of India, which functions as regulator for the fiscal field, desires financial institutions to limit ownership stakes in insurance organizations. browse additional

HDFC Bank’s acquisition of HDFC Ltd (HDFC.NS), introduced on Monday, will develop an entity with a merged harmony sheet well worth $237 billion and will contain the target’s insurance policies and other money subsidiaries.

Register now for Cost-free unlimited accessibility to Reuters.com

HDFC Everyday living and HDFC ERGO are amongst the top lifestyle and common insurance plan firms in the non-public sector, and analysts say the RBI is not likely to be comfortable with the sizing of the insurance operations the deal will give the financial institution.

HDFC Bank’s management mentioned on Monday that they have requested the regulator for clarity on complying with its principles, but analysts feel it may not be easy to arrive by.

“Considering there are good deal of subsidiaries that will need to be merged, there could be some regulatory overhang, particularly in the insurance business the place the central bank is not pretty snug with banks escalating their stake,” claimed an analyst at a domestic brokerage residence.

HDFC Lender did not straight away respond to a Reuters request for remark on Tuesday. The RBI also did not react to a request for remark.

A person way of folding the subsidiaries into HDFC Bank could be to produce a holding organization composition, but that could have a negative affect on the harmony sheet in the brief expression, analysts said.

“If a holding organization structure is enforced then the equation improvements. Value goes up as stamp responsibilities and taxes will go up,” Macquarie said in a take note on Tuesday.

In the brief expression, return on equity (RoE), a key economical metric, will also go down as a end result of meeting specified regulatory demands, the Macquarie observe stated.

As a shadow bank – a finance enterprise outside the scope of classic banking regulation – HDFC Ltd has a better expense of resources as opposed to the bank.

Put up merger, the entity could as a result in the brief term also see a bigger value of money, which could have an affect on its margin, stated a portfolio manager at a retail brokerage agency.

“Owing to this and other ambiguities relating to the offer and the performance, the inventory may possibly not see a major valuation re-rating promptly,” he extra.

HDFC Lender shares fell as significantly as virtually 3{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} on Tuesday, while HDFC Ltd slipped additional than 2{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}. Equally stocks experienced surged around 10{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} on Monday.

If it clears the hurdles to a deal, HDFC Financial institution will shrink the hole in sizing with point out-operate loan company and bigger rival State Bank of India (SBI.NS), and pull additional away from friends this kind of as ICICI Financial institution (ICBK.NS) and Axis Lender (AXBK.NS). go through a lot more

Sign up now for Absolutely free unrestricted obtain to Reuters.com

Reporting by Nupur Anand Editing by Jan Harvey

Our Criteria: The Thomson Reuters Believe in Ideas.

As Wall Street banks embrace crypto, start-ups look to lure top finance talent

As Wall Street banks embrace crypto, start-ups look to lure top finance talent

Wall Street has been beefing up hiring for digital asset groups. But some workforce are strolling away from identify-brand name establishments in search of much more hazard, and probably, much more reward.

JPMorgan Chase, Morgan Stanley and Goldman Sachs are between the companies with dedicated groups for cryptocurrency and its underlying blockchain know-how. JPMorgan has a person of the biggest crypto teams, with far more than 200 personnel operating in its Onyx division. The JPM Coin digital currency is staying utilised commercially to ship payments about the planet.

Umar Farooq, the CEO of Onyx by JPMorgan, reported the crew has to fret about compliance and preserving the bank’s manufacturer and frequently moves slower than your normal crypto start-up. But when products are released, they access “a scale that a fintech can only desire of.”

“There are not quite a few spots wherever you can roll out a new platform and that platform can go from actually nothing at all to transacting a billion bucks of trade a working day in a several months,” Farooq told CNBC. “That kind of scale can only be achievable when you operate at a business like JPMorgan Chase. The upside of that scale is way extra essential than whatsoever downsides could exist by advantage of much more rules or controls.”

When it comes to choosing, Farooq explained it’s a blend of present JPMorgan personnel and competing for expertise with get started-ups and even larger tech businesses. From initial-12 months analysts to senior administration and controlling administrators, there is a better curiosity in generating the move to crypto, he explained.

A ‘Wall St’ sign is noticed above two ‘One Way’ signs in New York.

Lucas Jackson | Reuters

Economical expert services firms included 3 situations as lots of crypto employment final year than in 2015, in accordance to modern information from LinkedIn. In the initially half of 2021, that rate jumped by 40{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}. Banking institutions on a crypto choosing spree integrated Deutsche Financial institution, Wells Fargo, Citigroup, Capital 1, Barclays, Credit history Suisse, UBS, Lender of America and BNY Mellon.

The crypto growth on Wall Avenue coincides with a lot more funding and using the services of in the start-up entire world. Crypto and blockchain corporations lifted a history $25 billion final year, an eightfold raise from a calendar year previously, according to CB Insights details.

Farooq claimed that even with the get started-up growth, JPMorgan has noticed “limited attrition.” People leaving have been individuals “seeking to get started their personal organization as opposed to seeking to depart and go do a thing equivalent.”

On the other hand, JPMorgan did eliminate a person of its optimum-profile crypto deputies last calendar year. Christine Moy is on back garden leave just after departing her role as running director and world wide head of crypto and metaverse at Onyx. She has still to announce her next go.

“After above a half-10 years laying the foundations for blockchain-based mostly infrastructure throughout financial marketplaces and cross-border payments, creating new organizations that have already scaled into the $USD billions at J.P. Morgan, I am looking to obstacle myself additional by locating new possibilities to generate price and drive influence for the Web3/crypto ecosystem from a new angle,” Moy advised CNBC in an electronic mail.

Leaving Wall Road

Other top rated crypto executives who left Wall Street not too long ago expressed some irritation at how very long it requires to get jobs going in just a massive economic establishment.

Mary Catherine Lader, chief functioning officer at Uniswap Labs, left her work as a taking care of director at BlackRock final calendar year. Her foray into crypto started out as a side job within the asset administration company.

“It surely was not my principal task,” Lader mentioned. “It was type of a pastime, as it is for so several folks on Wall Street, and it unquestionably was not anything that at the time I was considering about, due to the fact it was early levels of adoption.”

At Uniswap, Lader is now doing work on an rising decentralized cryptocurrency trade. She claimed she couldn’t go up the opportunity to function on the upcoming wave of innovation.

“This know-how is so vital to the upcoming of finance that it failed to truly feel like a danger at all,” Lader stated. “I was unhappy to leave the men and women I experienced loved operating with for many a long time. I have tremendous regard for the agency, but it did not really feel like a hazard. Which is a good factor about in which we are in Website3.”

Justin Schmidt, former head of digital asset marketplaces at Goldman Sachs, created a very similar occupation transform last year. He joined institutional crypto buying and selling platform Talos and explained the risk in a identical way, contacting the decision “multidimensional.”

“Inherently, you happen to be getting a model hazard — Goldman is just one of the storied establishments of Wall Avenue,” Schmidt reported. “You are also getting a hazard by staying someplace more standard, and I incredibly firmly imagine that this is a generational improve and there is a generational chance here.”

Cryptocurrency commence-ups and banking institutions describe a change in the hunt for prime talent. Many are seeking beyond top rated candidates with MBAs, and as a substitute thinking about individuals with a lot less traditional resumes. Lader and Schmidt reported some of their most effective crypto hires have been self-taught engineers or crypto influencers they initial interacted with on Twitter.

“I consistently am meeting men and women who are 23 years previous, who are as smart about marketplaces as individuals I labored with on Wall Road for years,” Lader reported. “Individuals who frankly had no interest in money products and services, who would by no means definitely examine or consider doing work on Wall Avenue, are fired up to get the job done at UniSwap Labs and businesses like us.”

Evli Bank’s demerger and the remaining company’s merger with Fellow Finance have been registered; Evli Plc’s listing application has been approved and trading in shares will commence on April 4, 2022

Evli Bank’s demerger and the remaining company’s merger with Fellow Finance have been registered; Evli Plc’s listing application has been approved and trading in shares will commence on April 4, 2022
Evli Bank Plc

Evli Bank Plc

EVLI PLC Stock Exchange Launch 2 APRIL 2022 AT 4.00 PM. EET

NOT FOR PUBLICATION OR DISTRIBUTION, IN Full OR IN Part, Directly OR INDIRECTLY, IN OR INTO AUSTRALIA, SOUTH AFRICA, HONG KONG, JAPAN, CANADA OR SINGAPORE, NEW ZEALAND, THE UNITED STATES OR ANY OTHER JURISDICTION Exactly where These PUBLICATION OR DISTRIBUTION WOULD VIOLATE Applicable Laws OR Policies OR WOULD Have to have Supplemental Paperwork TO BE Done OR REGISTERED OR Need ANY Evaluate TO BE Carried out IN ADDITION TO THE Needs Beneath FINNISH Regulation. SEE “Critical Detect” Beneath.

Evli Financial institution Plc and Fellow Finance Plc announced on July 14, 2021 that they have agreed in a mixture settlement of an arrangement whereby Evli Lender will demerge via a partial demerger into a new asset management group Evli Plc (“Evli”) (the “Demerger”) that will be outlined and a corporation that will have on Evli Lender Plc’s banking companies and into which Fellow Finance Plc will merge (the “Merger”).

The Demerger and the Merger have been registered with the trade sign-up maintained by the Finnish Patent and Registration Business on the helpful date of April 2, 2022. Pursuing the completion of the Demerger Nasdaq Helsinki Ltd (“Nasdaq Helsinki”) has approved the listing application relating to the course B shares of Evli. Investing in Evli’s 9,364,289 course B shares to be admitted to investing on the official listing of Nasdaq Helsinki beneath the trading code EVLI (ISIN code: FI4000513437) will begin on April 4, 2022.

The Evli shares issued as demerger consideration have been registered on the book-entry accounts of Evli’s shareholders these days on April 2, 2022. Recipients of the demerger thing to consider shares may perhaps trade Evli’s class B shares as from Monday, April 4, 2022.

EVLI PLC


Further more information:

Juho Mikola, CFO, Evli Plc, tel. +358 40 717 8888, juho.mikola@evli.com


Evli in short

We see wealth as an engine to generate development. We attract on our heritage, wide know-how and Nordic values to expand and handle wealth for institutions, firms and private people in a accountable way.

We are the foremost asset manager in Finland* featuring a wide range of solutions including mutual money, asset administration and funds marketplaces expert services, alternate financial commitment solutions, fairness analysis, share plan design and administration as well as Company Finance services. Responsible investing is integrated in each and every investment decision decision and our abilities is greatly acknowledged by our purchasers. Evli has Finland’s very best know-how in dependable investment decision.**

Evli Group employs about 290 professionals and Evli has a total of EUR 17.5 billion in client property less than management (web 12/2021). Evli Plc’s B shares are mentioned on Nasdaq Helsinki Ltd.

*Kantar Prospera External Asset Administration Finland 2015, 2016, 2017, 2018, 2019, 2021, Kantar Prospera Private Banking 2019, 2020 Finland **SFR Scandinavian Fiscal Investigate Institutional Investment decision Expert services Finland 2021

Distribution: Nasdaq Helsinki, most important media, www.evli.com


Critical Recognize

This launch is not an offer you of shares in the United States and it is not meant for distribution in or into the United States or in any other jurisdiction in which this kind of distribution would be prohibited by applicable law. Evli’s shares have not been and will not be been registered underneath the U.S. Securities Act of 1933, as amended (the “Securities Act”) or the securities regulations of any state of the United States, and could not be offered, bought or delivered in or into the United States, besides pursuant to an relevant exemption of, or in a transaction not topic to, the Securities Act.

This launch does neither constitute an present to provide nor a solicitation of an present to invest in any securities by Evli in the United States or any other jurisdiction in which this kind of giving, solicitation or sale would be unlawful. This release ought to not be forwarded, distributed or sent, specifically or indirectly, in full or in aspect, in or into the United States or any jurisdiction in which the distribution of this launch would breach any relevant legislation or regulation or would involve any registration or licensing within such jurisdiction. Failure to comply with the foregoing limitation might consequence in a violation of the Securities Act or other applicable securities legislation or polices.

This release incorporates “forward-searching statements” that are dependent on existing strategies, estimates, projections and anticipations and are not assures of long term overall performance. They are based mostly on selected expectations and assumptions, which, even even though they feel to be acceptable at current, might convert out to be incorrect. Shareholders need to not count on these ahead-looking statements. Neither Evli nor any of their respective affiliate marketers, advisors or associates or any other human being undertakes any obligation to assessment or verify or to launch publicly any revisions to any forward-searching statements to reflect events that come about or circumstances that arise soon after the day of this launch.

Russian banks turn to China to sidestep cutoff from payments systems

Russian banks turn to China to sidestep cutoff from payments systems

Russian banking companies that have been slice off from worldwide payments networks are turning to China’s point out-owned UnionPay process as the country tries to sidestep boycotts by Western enterprises for its invasion of Ukraine.

Visa Inc. and Mastercard Inc. stated they are suspending their Russian functions, creating it challenging for Russians to acquire items from overseas. The moves by the two corporations go over and above sanctions issued towards quite a few Russian banks.

The logo for Mastercard is displayed on a screen above the investing flooring of the New York Stock Trade. ( AP Picture/Richard Drew, File / AP Newsroom)

Sberbank, Russia’s greatest bank by property, Alfa Lender and Tinkoff Financial institution reported Sunday they ended up working on the chance of issuing cards powered by China’s UnionPay. One more Russian financial institution, Gazprombank, explained clients can do cross-border transactions by obtaining playing cards that use UnionPay or Japan’s JCB process.

CHARITIES Struggle TO Provide HUMANITARIAN Help INTO UKRAINE

The workarounds clearly show Russia may well significantly count on China in the experience of isolation by the West. It wasn’t distinct no matter whether the transfer signaled a change toward higher cooperation between China and Russia to support Moscow uncover alternate ways to link to the world-wide financial procedure.

UnionPay is ubiquitous in China and expanded globally as Chinese traveled abroad, typically to acquire luxury merchandise. UnionPay playing cards are acknowledged in stores in 180 nations around the world and areas, and on line in above 200 nations and locations, in accordance to the company’s web site.

Besides its card community, China has been establishing its individual global payments technique as an alternate to the widely applied international community identified as Swift. That method, though, stays dependent on Swift for most of its transactions.

SWIFT

SWIFT (Society for Worldwide Interbank Economical Telecommunication) symbol displayed on a cellular phone display and coins are noticed in this illustration photo. (Photo by Jakub Porzycki/NurPhoto by means of Getty Pictures / Getty Pictures)

Beijing officials have opposed the Russian sanctions, when in the West, various corporations are heading further than them, stopping enterprise dealings even with non-sanctioned entities. It is not crystal clear how Chinese corporations will respond. Spokespeople for UnionPay and Japan’s JCB couldn’t be reached for remark.

Visa and Mastercard equally said Saturday that they have been chopping ties with Russia in response to its attack on Ukraine. Amongst the debit and credit playing cards issued in Russia, Visa and Mastercard playing cards accounted for 74{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of payment transactions in the country in 2020, according to the Nilson Report, a trade publication.

The shift dealt a different blow to Russia, which has observed many Western organizations lower solutions to the state in excess of the past week. Some Russian financial institutions have been sanctioned by Western nations, which means men and women and organizations there are forbidden from dealing with them. But various Russian financial institutions keep on being cost-free to do small business all-around the environment.

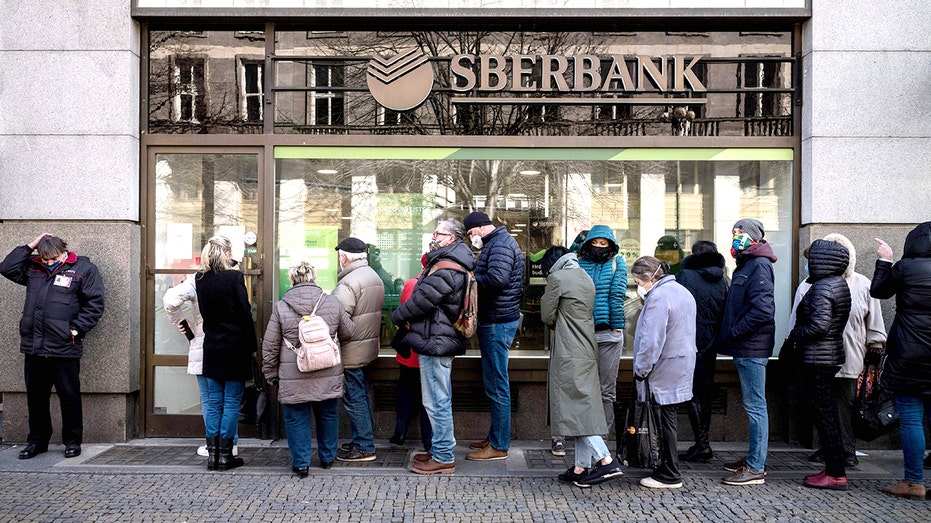
People queue outdoors a department of Russian state-owned bank Sberbank  (Photo by Michal Cizek/AFP by means of Getty Visuals / Getty Photographs)

The U.S. and the U.K. have moved to minimize Sberbank off from U.S. dollar and U.K. pound accessibility, but companies and people today are continue to authorized to offer with the financial institution.

Russian cardholders will still be equipped to use Visa and Mastercard cards inside Russia due to the fact the transactions will travel about Russia’s payments procedure, termed Mir. But they won’t be capable to use the playing cards overseas, besides in a handful of nations around the world that aid Mir, which include Turkey, Vietnam and Armenia.

RUSSIA-UKRAINE WAR: ARIZONA AMMO Firm TO Send out 1 MILLION ROUNDS OF AMMO TO UKRAINE

Alfa Lender reported Sunday that its customers’ Visa and Mastercard playing cards will deal with limitations on their use exterior Russia beginning March 10. It urged consumers overseas to withdraw funds in the meantime.

However, Alfa Bank stated it would go on to difficulty cards hooked up to both equally Visa and Mastercard, presented it has quite a few million in inventory. “We hope that the intercontinental payment programs will return to our country. Then the cards will immediately begin performing all over the world,” it mentioned.

Click on Here TO Examine Extra ON FOX Business