Wall Street’s Green Push Exposes New Conflicts of Interest

The booming company of green finance is being led by an unlikely team of corporations that sits at the coronary heart of the fiscal procedure.

The large companies that audit the books, level the bonds, advise on proxy voting and categorize the world’s companies are expending billions to enhance their local weather-relevant functions. That could accelerate the shift away from fossil fuels but could also make a new established of conflicts of interest for industries that struggled to handle them in the previous.

In the earlier two yrs, U.S. companies in the monetary-solutions sector have put in a lot more than $3.5 billion buying inexperienced-scores providers and information companies, a evaluation by The Wall Avenue Journal observed. The Big 4 audit companies are also going into the environmental, social and governance, or ESG, arena. PricewaterhouseCoopers final year mentioned ESG was a aim of its $12 billion investment decision approach.

When the United Nations past yr asked the finance market to back its programs to slash carbon emissions, lots of banking companies had to be cajoled into signing up. Fiscal-expert services corporations eagerly jumped in, in accordance to individuals involved in the effort and hard work.

These corporations are betting on significant income as providers, responding to calls for by regulators and investors, seek out to lessen their carbon emissions and better disclose their ESG techniques. The corporations have bought up smaller sized corporations to bolster their choices.

The market for serving to businesses with company ESG reporting by itself is well worth an believed $1.6 billion globally, and forecast to boost by 21{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} a calendar year in excess of the up coming 6 several years, according to U.K.-centered research company Verdantix. “The progress fee across several spots of ESG qualified products and services is incredibly powerful,” stated Kim Knickle, a investigation director at Verdantix.
PricewaterhouseCoopers has mentioned the ESG arena is a emphasis of its $12 billion expense system.


Picture:

Krisztian Bocsi/Bloomberg Information

In quite a few circumstances, corporations that charge or consider firms on issues like weather chance also sell companies to assistance providers tackle these problems. Numerous of the firms delivering these rankings, these types of as credit rating raters and auditors, are by now taking care of deep conflicts of interest since they are compensated by the firms they choose. Conflicts of curiosity in the credit rating-ratings field were being a single trigger of the money disaster, according to lawmakers.

A person new set of probable conflicts springs from the prevalent practice of advertising ESG ratings together with consulting and other providers.

Institutional Shareholder Companies, the nation’s largest shareholder advisory organization, sells to buyers its local weather-threat ratings for countless numbers of organizations. It also sells to all those firms tips on how to boost people scores.

“Improve ESG Ratings,” the Rockville, Md.-centered agency says in its pitch to the around 5,000 companies it addresses. “Stand out between companies that you contend with for capital.”

The financial-companies firms’ various ESG products and services build very clear possible conflicts of interest, in accordance to Anant Sundaram, a finance professor at Dartmouth College’s Tuck Faculty of Business. “They make money flows by providing their services…to the very corporations they are intended to be unbiasedly scoring and ranking,” he mentioned.

SHARE YOUR Ideas

Do you imagine economic-solutions providers see eco-friendly finance as a organization chance? Why or why not? Sign up for the discussion underneath.

ISS’s typical counsel, Steven Friedman, claimed the organization, owned by German stock exchange operator

Deutsche Börse,

has taken actions to handle opportunity conflicts of curiosity in its ESG perform, which includes a firewall separating its rankings and company-advisory units. “ISS does not and will not give preferential treatment to any corporate issuer,” Mr. Friedman included.

ESG raters commonly get most of their profits from expense corporations, which package deal together top rated-scoring organizations to develop inexperienced-branded solutions that are offered to buyers. That generates an incentive to hand out substantial ESG scores, said Hans Taparia, a company professor at New York University.

“If the raters were being to be rough on firms, there wouldn’t be any merchandise to produce for investors,” Mr. Taparia reported.

Fund-rankings company

Morningstar Inc.

offers out functionality awards that are available only to providers that pay back it for an ESG assessment.

Morningstar’s Sustainalytics unit sells businesses an “ESG Possibility Score License” for an undisclosed sum. “Showcase that you are rated by a world’s primary ESG Rating agency,” its web site states. Only companies that obtain the license are suitable to most likely get a “Top-Rated ESG Badge.”

Badge winners involve

Freehold Royalties Ltd.

, a Canadian organization with a portfolio of oil-and-gasoline homes. The business is not major rated by everybody. It is categorised as a “poor” ESG performer, with a score of 23 out of 100, by ratings-organization Refinitiv, owned by

London Inventory Exchange Group.

A Freehold Royalties spokesman declined to comment.

A Sustainalytics spokeswoman said Freehold Royalties is rated a small ESG risk—and therefore scores well—because it earns most of its money from possessing land on which oil and gas are produced, instead than from drilling wells. She included that Sustainalytics views its management of potential conflicts of interest as “crucial to the independence and integrity” of its scores.

Regulators are commencing to glance at prospective conflicts of curiosity in the largely unregulated ESG sector. The Intercontinental Firm of Securities Commissions, an umbrella group of finance watchdogs, last yr highlighted the many expert services available by numerous ESG-scores firms.

It encouraged its customers, which include the U.S. Securities and Exchange Fee, think about necessitating ESG rankings and facts firms to “identify, disclose and, to the extent achievable, mitigate potential conflicts of fascination.”

An SEC spokeswoman declined to remark.

Ratings firms are pushing back in opposition to possible new polices. The “presence of any…potential conflicts does not necessitate regulation of ESG details,” Morningstar explained to IOSCO regulators previous calendar year.

Scores huge

Moody’s Corp.

advisable to IOSCO that any new policies should really let corporations to show how they tackle conflicts, “rather than build slim prerequisites.”

Moody’s, which previous year paid $2 billion to get weather and organic disaster analysis company Chance Administration Options Inc., sells ESG assessments of businesses to buyers. Moody’s also sells equivalent assessments to the organizations them selves, stating it can support them “seize new possibilities for benefit creation” from climate-modify.
Moody’s claims it has safeguards to safeguard the independence and integrity of the credit history rankings system.


Image:

Michael Nagle/Bloomberg Information

Credit-scores firms’ sales of ESG providers create a even more, troublesome, established of opportunity conflicts, in accordance to Jeffrey Manns, a legislation professor at George Washington College.

Providers may possibly experience pressured to purchase ESG consulting solutions from a credit history-score agency to preserve a fantastic marriage with that company and safeguard their credit rating, he claimed.

Yet another possibility is that credit history-ratings corporations might be a lot more hesitant to downgrade businesses that fork out them major fees for credit history rankings and, now, for ESG services, according to Mr. Manns. “Rating agencies have no curiosity in biting the hands that feed,” he stated.

A Moody’s spokesman said the organization has safeguards to defend the independence and integrity of the credit history ratings process. “Our credit score scores are not influenced by commercial issues throughout any factor of our company, which includes ESG,” the spokesman included.

Rival credit-scores giant

S&P World wide Inc.

has professional passions in enterprises that can influence companies’ ESG scores. It also concerns these scores and sells ESG info reporting, auditing and chance-management providers to organizations.

S&P is part-proprietor of a San Francisco-based mostly company known as Xpansiv that runs the Aviation Carbon Exchange, a marketplace that makes it possible for airlines to purchase and market carbon credits. Airlines’s use of such credits to manufacturer their functions as sustainable has been criticized by environmental teams, between other individuals.

An S&P spokeswoman said the firm is committed to the independence and objectivity of its products and solutions and services. S&P has “controls in location to detect and take care of real, opportunity, or perceived conflicts of passions,” the spokeswoman additional.

Create to Jean Eaglesham at jean.eaglesham@wsj.com

Copyright ©2022 Dow Jones & Firm, Inc. All Legal rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8

Why the stock market hates the idea of rising interest rates

Traders work on the flooring of the New York Inventory Trade at the opening bell Jan. 25, 2022.

TIMOTHY A. CLARY | AFP | Getty Pictures

The specter of mounting curiosity premiums is spooking the stock industry.

The Federal Reserve, the U.S. central bank, is envisioned to increase its benchmark charge a number of periods this calendar year to tame stubbornly substantial inflation. Fed chair Jerome Powell affirmed that chance on Wednesday.

The move would boost borrowing fees from in close proximity to zero — in which they have been since the beginning of the Covid pandemic — for firms and consumers.

The forecast has triggered shares to nosedive in January.

The S&P 500 index is down about 9{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} for the yr. At one particular level this week, the basket of U.S. stocks dipped beneath 10{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} — the 1st time which is transpired because the first pandemic turmoil of March 2020. The index closed down .2{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} Wednesday soon after Powell’s remarks, erasing before gains.

Cooler economic climate

Why does the stock marketplace treatment?

Broadly, the causes seem to be twofold: A slowdown of the U.S. overall economy and the prospect of other investments like bonds starting to be additional attractive relative to shares.

When the Fed raises its benchmark interest fee, financial institutions and lenders tend to raise borrowing expenses, also. Mortgages, credit score cards and other debt develop into pricier, lessening buyer shelling out and demand from customers. Firms also shell out far more to finance their functions.

Additional from Personal Finance:
What the Fed’s approach to raise desire prices indicates for you
Why new dad and mom might qualify for yet another $1,400 stimulus look at
3 good reasons to retain your will or estate prepare updated

Broadly, this dampens the outlook for corporation earnings and reduces investor enthusiasm for getting their stock.  

“A tightening of financial plan will place strain on economic action,” according to Blair duQuesnay, a accredited financial planner and expenditure advisor at Ritholtz Wealth Administration, who is centered in New Orleans. “And it is really by layout.”

Too significantly, also fast?

Traders be concerned an intense Fed reaction may well slam the brakes on the financial system — even though Powell has sought to reassure the coverage reaction will be “nimble.”

Nervousness in excess of that final result is the key purpose for market place jitters, according to CFP Lee Baker, founder of Apex Economical Solutions in Atlanta.

“What are the trickle-down outcomes if the Fed raises prices also considerably, far too fast? If it slows down the economic climate, what does that do to [company] earnings? You just form of follow that domino,” Baker stated. “If you happen to be speaking about earnings, you’re chatting about stocks.”

(This dialogue is relative to a wide basket of U.S. stocks. It really is not legitimate that all organizations essentially suffer if premiums rise. Some may well do greater — like a lender, for case in point, that charges additional to lend.)

Shares get rid of luster

If fees rise, buyers may perhaps see much more benefit in bonds, certificates of deposit and other property assumed to be significantly less dangerous than stocks.

Yields in those conservative assets have been relatively paltry since the 2008 money crisis, which led to a extended time period of rock-bottom curiosity charges to spur the economic climate.

It’s possible [stocks] should really sell off in spite of something else.

Blair duQuesnay

CFP and financial commitment advisor at Ritholtz Wealth Management

Investors searching for returns ended up basically “pressured” into shares, Baker said.

The worth proposition might adjust, if bond yields and CD premiums go upward in tandem with the Fed’s benchmark charge.

Other elements

Even though it would seem to engage in the biggest part, Fed policy just isn’t the only detail putting buyers on edge.

For one, you can find the prospect of war in between Ukraine and Russia. Those geopolitical tensions gasoline more uncertainty — for illustration, how could possibly the strength sector be impacted if battling breaks out?

The inventory selloff may well be a great detail, impartial of what is creating it, duQuesnay said. The Federal Reserve is speaking about increased desire costs due to the fact the overall economy and labor marketplaces are sturdy a reduction in inventory selling prices may also tether lofty firm valuations extra to fact, she stated.

“If you acquire away all the outside news and facts about the inventory market, it’s absent up double digits for a few many years in a row,” according to duQuesnay. “It’s possible it should sell off irrespective of anything else.”

Pregnant man, pregnant person emoji coming to Apple iPhones

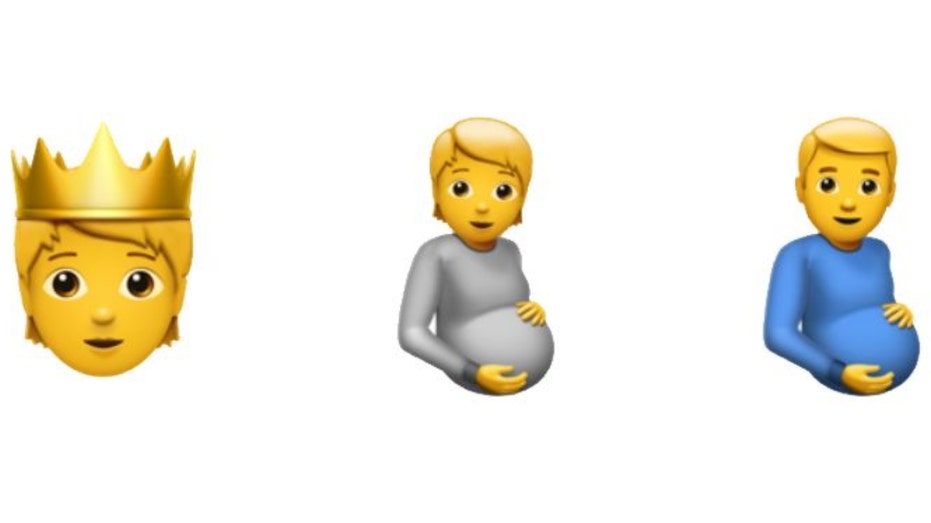
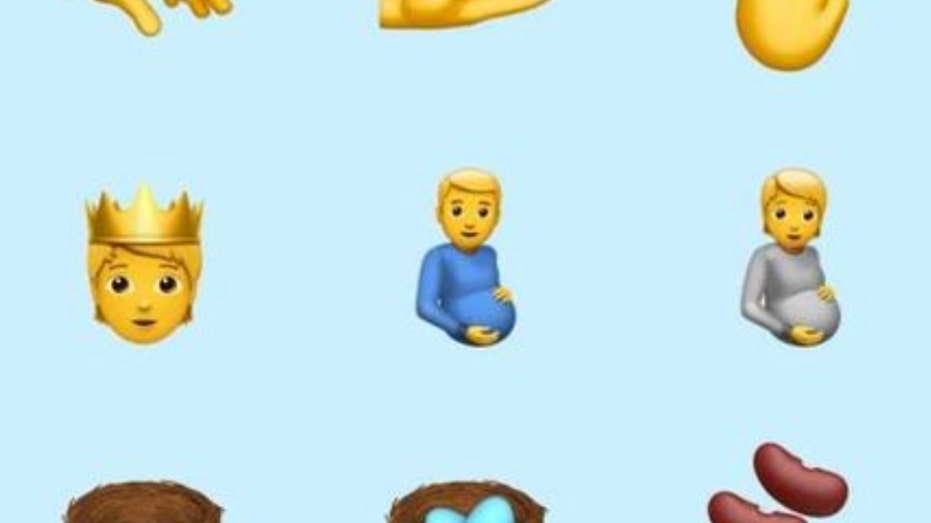
A “pregnant male” emoji and “expecting man or woman” emoji are coming to Apple iPhones with its most current update, iOS 15.4 sparking controversy. 

The pregnant emoji are not new for some, considering the fact that they arrived as component of an update that emoji-encyclopedia Emojipedia announced in September 2021. Nonetheless, Apple’s edition of the emoji were introduced Thursday as section of iOS 15.4 beta — a voluntary technique update Apple iphone consumers can decide on to put in.

The update will arrive to all Apple iphone people later this year. 

Pregnant man emoji Apple iOS 15.4 (Emojipedia blog)

Expecting particular person and pregnant male emoji for Apple iOS 15.4. (Emojipedia blog site)

The force to consist of anyone in pregnancy has erupted in controversy, with some cultural commentators arguing that the effort to make the biologically distinct phenomenon all-inclusive erases factors that make women distinct from men and even dehumanizes gals. 

To voice worries with Apple: (408) 996–1010

Emojipedia confronted some criticism when it very first declared the expecting gentleman and expecting particular person emoji in September of final 12 months. The enterprise explained in a web site write-up that the new figures “might be employed for illustration by trans adult males, non-binary people, or females with short hair—though, of program, use of these emoji is not restricted to these teams.”

APPLE HITS NEW QUARTERLY Revenue Document Irrespective of Provide CHAIN Troubles

The emoji can also be applied as a “tongue-in-cheek way to display a foodstuff newborn, a extremely comprehensive stomach brought on by having a huge meal,” Emojipedia’s Jane Solomon wrote.

Pregnant man emoji Apple iOS 15.4 (Emojipedia blog)

Expecting gentleman emoji Apple iOS 15.4. (Emojipedia weblog)

Equally new pregnant emoji also come in 5 different pores and skin tones. When picking an emoji, buyers can hold their finger on the icon till it shows diverse pores and skin tone options.

Emoji initial arrived to Apple in 2016, when the expecting lady emoji was launched.

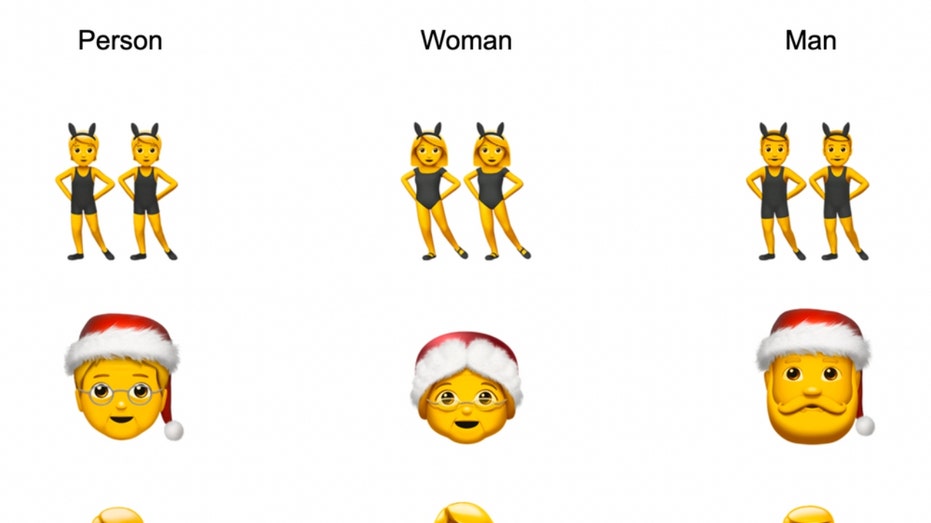
Emoji creators have “created an work to be inclusive with gender, specially in current a long time. The strategy has different based on the predicament, though the general aim is to standardize inconsistencies in legacy decisions,” Solomon wrote.

Inclusive emojis (Emojipedia blog)

Inclusive emojis (Emojipedia website)

According to wellbeing web-site Healthline.com, people today who had been born biologically female but establish as guys are transgender males who can give start simply because they have the reproductive organs required to do so — primarily individuals who do not choose or have stopped taking testosterone. The identical goes for these who determine as non-binary.

It is unclear how many males have gotten pregnant or delivered toddlers in the United States. At the very least 22 adult males in Australia gave delivery in 2018, The Each day Mail documented, citing the country’s Medicaid facts.

GET FOX Enterprise ON THE GO BY CLICKING Right here

Apple did not instantly respond to an inquiry from FOX Business.

UBS launches program aimed at minority clients with $1M+

A single of the biggest prosperity administrators is attempting to have interaction a client segment spanning as lots of as 2 million men and women who are portion of groups that have historically been excluded by the industry.

Launched on Jan. 25, The UBS Wealth Administration United states Multicultural Investors Strategic Customer Section is offering the firm’s roughly 6,200 money advisors analysis, entry to new racial equity investing goods and discussion guides for prospective customers who are Black, Latino or Asian American and have at least $1 million in investable belongings. The new program joins existing kinds aimed at females, small business owners, mounting generations, and athletes and entertainers, stated Melinda Hightower, the head of the new consumer phase.

It comes as significant wealth administrators, advisors and academic researchers look for far more information about affluent and higher internet value clients from underrepresented groups. In some circumstances, the possible shoppers may well not even be knowledgeable of financial commitment opportunities that could construct generational wealth. The obstacles to accessing them contain the industry’s lack of representation of women and minorities as well as outright racist actions or business-wide tactics.

Melinda Hightower, UBS Global Wealth Management.

Melinda Hightower is the head of the multicultural investors strategic consumer section with UBS Worldwide Wealth Management.

UBS

Many of the new packages released above the past pair of many years in wealth management have revolved all-around philanthropy or striving to achieve new groups of customers by means of the “same way of carrying out enterprise,” claimed Hightower.

“Inclusion was unquestionably not central to that practical experience, and they are just heading to the new viewers and indicating, ‘Here we are.’ So you might be getting a bunch of sick-fitting merchandise,” she mentioned in an interview. “We are pondering that the improve has to come about within the way that we present investment assistance, and so that’s what we’re critically centered on.”

Hightower stated extra details would be out there in coming months about the racial fairness investing items coming to UBS, alongside with insights from polling her staff has conducted with the customer segment it estimates to be in between 1 million and 2 million Us citizens. The team will supply academic assets to advisors focused on topics such as linking portfolios to a legacy past one’s rapid family and the central great importance of setting up generational prosperity. The corporation aims to expand conversations all through client meetings and prompt advisors to check with about legacy specially, according to Hightower, who claimed that “preserving generational wealth” and making ready younger individuals for that transfer are the clients’ principal economic ambitions.

While driving transform in wealth administration over the lengthy time period will get time, it is probable if shopper-experiencing advisors in branches take steps within their methods when executives intently study what their companies could be carrying out as an business, said Dana Wilson, CEO of Transforming How Individuals Prosper (CHIP), a economical services marketplace for Black and Latino industry experts and possible clients. The business recently released its personal quarterly magazine as portion of its endeavours to improve the visibility of minority advisors and clients. There are “always a lot of skipped options in that stereotype” when corporations or advisors presume that working with Black and Latino clientele suggests lessen account measurements, Wilson reported.

“It’s not that folks you should not have dollars. We have it, we just have not had the entry and the possibility to be equipped to have all those discussions and to be equipped to have it make perception to our lives,” Wilson reported. “It’s a nice detail to wander into a area and say, ‘Oh, this is one thing that is for me. … It is definitely just about shifting the dynamics and breaking down some of those people boundaries.”

Wilson praised the preference of Hightower to guide the outreach to the customer section at UBS, the place Hightower says some advisors are presently tapping into it correctly and taking part in her team’s exploration for other planners. A former personal banker with J.P. Morgan Chase who served clients that are aspect of the phase, Hightower argues that advisors of all backgrounds can make the expertise superior for any shopper by trying to get far more engagement over and above their regular base. The company’s purpose is not to build a silo for selected persons, she claimed.

“It’s a little something that is vital to any person for whom inclusion is crucial,” Hightower explained. “In get to keep on being appropriate, economic institutions ought to genuinely consider be aware and operate to be as inclusive as feasible.”

Solar industry in Colorado, across US expected to shine in 2022

Government and financial analysts are predicting what marketplace reps say they see occurring on the ground: 2022 is likely to be a major calendar year for solar vitality.

The U.S. Vitality Info Administration said it expects just about 50 percent of new electrical power building ability to be solar. The company expects to see around 46 gigawatts of new utility-scale solar power extra in the U.S. in 2022.

1 gigawatt of solar energy is ample to provide about 750,000 properties.

The money solutions corporation S&P World-wide Platts mentioned most new building ability will come from photo voltaic energy this yr, followed by wind vitality.

“I think we’ll have a bumper yr. Desire is not abating in any way,” reported Mike Kruger, president and CEO of the trade group Colorado Photo voltaic and Storage Association.

Utilities, including Xcel Energy, Colorado’s largest service provider of electrical power, and smaller sized utilities these as the Platte River Electrical power Authority, are adding new assignments this yr.

“Rooftop photo voltaic desire is up so significantly that my men just can’t hold up,” Kruger mentioned.

Immediately after using a dive when the coronavirus pandemic started out in 2020, the photo voltaic market regained floor, according to the Photo voltaic Electrical power Industries Association. Photo voltaic power produced up 54{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996} of all new electric producing capacity in the initial 3 quarters of 2021, in accordance to a the latest report released by the group.

Nonetheless, ongoing provide-chain troubles and selling price will increase led study agency Wood Mackenzie, which geared up the report, to scale again its outlook for expansion in 2022 by 33{21df340e03e388cc75c411746d1a214f72c176b221768b7ada42b4d751988996}, or a lower of 7.4 gigawatts.

As a result of the third quarter of 2021, Colorado experienced sufficient installed solar capacity to ability 438,842 houses, in accordance to the SEIA’s details. There were being 6,771 work opportunities in the business and 347 solar firms in the point out.

Along with other industries, the photo voltaic power sector is also struggling to find people to fill openings.

“I actually communicate to companies each and every working day that are selecting,” Kruger mentioned. “There’s an installer on the West Slope who’s managing three crews and he reported if he could, he would go to six crews in the spring when the snow melts.”

Kruger said the solar association will keep a job truthful during its regional convention, which operates Monday through Wednesday in Denver.

Tariffs and the large bounce in shipping-container costs are other hurdles facing the photo voltaic strength sector for the reason that quite a few of the photo voltaic panels are produced in China. Reuters claimed Thursday that President Joe Biden is taking into consideration extending the Trump-era tariffs on solar panels, with some alterations, in an hard work to stimulate domestic output.

The tariffs are thanks to expire Feb. 6.

A market crash will depend on which bit of the equation investors got wrong

The writer is editor-in-main of MoneyWeek

For individuals baffled by the current market this yr, I have a suggestion. Spend in the Simple Historical past of Monetary Markets course operate by the Edinburgh Organization Faculty (you can do it on-line — no want to come to chilly Scotland). Just one of the modules focuses on the heritage of excessive sector valuations — what leads to them and what crashes them.

The 1st point to be aware is that, when we enjoy to converse about bubbles, periods of excessive valuation in the stock marketplace don’t actually materialize incredibly typically. Of the 29 company cycles in the US due to the fact 1881 only a several have ended in 1, according to Professor Russell Napier. But, when each has experienced its individual peculiarities, the standard driver has been significantly the very same: the ability of buyers to feel certainly in a little something that normally turns out to be unattainable. Specifically that, thanks to some “marvels” of technology, company income will keep higher (and likely increase) indefinitely and that interest prices will also remain minimal indefinitely.

In most cycles traders do not think this. They suppose cyclical normality — that quick financial progress will direct to capability constraints and then to inflation and level rises, some thing that would sluggish both of those financial development and crimp corporate income — bringing down valuations. We like to assume of equities as all sorts of matters: correct now, for illustration, all much too many buyers consider of them generally as advantage signalling autos (witness the now collapsing bubble in renewable vitality shares).

But extended phrase, equities are not seriously about emotions or demonstrate ponying: they are about the net existing value of all upcoming cash flow streams discounted at whichever the discounted amount is at the time. That’s it. So price reduction charge up, value down (ordinarily when inflation hits about 4 for each cent).

A right bubble can then only create if traders do not think cyclical normality but alternatively take care of to persuade themselves (from all historic working experience) that it is achievable for a higher-revenue, reduced-inflation setting to be permanent. This generally ends terribly. Think 1901, 1921, 1929, 1966, 2000, 2007, briefly 2020 and potentially correct now.

The only issue is how rapidly it finishes terribly. The crucial point below, says Napier in his lectures, is which little bit of the equation investors have been acquiring incorrect. If it is the belief that fascination costs will hardly ever increase, you have a tendency to get a lengthy drawn out bear marketplace (from 1966, when it would have been challenging to envision the inflation of the late 1970s). If it is extra the perception that company earnings will continue to be significant eternally, it tends to be shorter and sharper (2020 was a mini typical of this style of crash).

So in this article we are. Inflation has been negligible for a long time. US company income have been really significant and increasing for many years: they strike yet yet another record high in the third quarter of 2021. And of training course, as a final result, US stock marketplace valuations strike bubble stages some time ago: by the close of very last calendar year the cyclically adjusted cost-to-earnings ratio was knocking at about 40, extra than double its extended-term typical. Buyers have once again been believing far too several difficult matters right before breakfast — one thing they could possibly be starting off to realise.

So here’s the issue: which bit have we acquired most incorrect this time all over. Is it the price reduction rate or company earnings? The low cost price feels like the noticeable just one, though increasing curiosity rates obviously hit corporate margins as well.

Low-cost labour and globalisation extensive back made inflation no a lot more than a distant nightmare for more mature investors and a thriller to more youthful kinds. Most therefore fell for the nonsense from central financial institutions past calendar year that the quick-mounting inflation they were observing was transitory. And even these that thought it may well very last over and above, say, Easter however believed that central banking companies would keep off raising prices irrespective.

So the actuality that superior growth (US gross domestic product grew by 6.9 per cent in the final quarter of 2021) truly can slam into ability constraints and create inflation costs starting up with sevens is turning out to be a terrible shock — as are the indications that central financial institutions could possibly basically do a little something about it.

The Federal Reserve, beneath tension from the inflation by itself and potentially also from polls suggesting that stated inflation is not assisting President Joe Biden, is now changing tune (no extra “transitory”). There is even, suggests Aegon Asset Administration, “a sensible likelihood of 7 rate hikes this 12 months, a person at every single meeting”. Illusion-shattering stuff.

It also leaves investors with tiny option: as lengthy as the Fed retains this line they should really certainly not acquire dips but provide rallies — at least when it arrives to their most expensive holdings (we can argue about whether the likes of Peloton, down 80 per cent in six months, is however highly-priced or not). In inflationary moments, benefit currently starts off to look like it may well be worthy of a lot more than possible price tomorrow (a fowl in the hand is truly worth a whole lot more than an electrical flying auto in the bush).

With that in brain, it is well worth noting that the FTSE 100, with its moderately valued income making stocks, is outperforming the S&P 500 — so considerably so that it is now on monitor to have outperformed about a 12-month time period by the stop of this month. Which is a thing it has not performed for a entire calendar year since May perhaps 2017. But it is a swap I suspect most Simple Heritage of Money Markets learners ended up completely ready for.